In the automotive sector, MLCC is generally used in power system, safety system, comfort system, entertainment system and so forth. That intelligent driving functions prevail in cars brings strong demand for MLCC. As the intelligentization, networking and electrification of vehicles is galloping, it is expected by industry insiders that MLCC use in cars will soar by folds. In the era of intelligent connected battery electric vehicle (BEV), a single vehicle requires as 6 times MLCCs as that for a current common internal combustion engine.
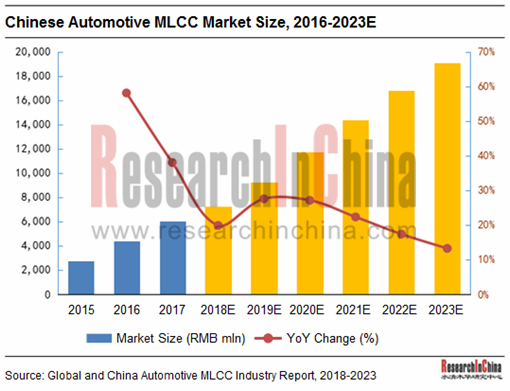
In recent years, electrification of cars is gathering momentum worldwide, and battery electric vehicle (BEV) output keeps soaring year after year, coupled with a steady rise in output of hybrids/PHEVs and smart fuel-efficient models as well as common internal combustion engines going intelligent, all of which serve as a spur to the demand for MLCC. As estimated, the Chinese market size of automotive MLCC will report RMB19.053 billion in 2023 (as compared with RMB6.044 billion in 2017), showing a CAGR of 21.1% between 2017 and 2023.
The well-known automotive MLCC vendors are mainly from Japan, South Korea, Europe & America, and Taiwan (China), of which Japanese companies consist of Murata, TDK, Taiyo Yuden, Kyocera, etc.; South Korean peer refers to Samsung Electro-Mechanics; and Taiwanese counterparts are Yageo and Walsin Technology.
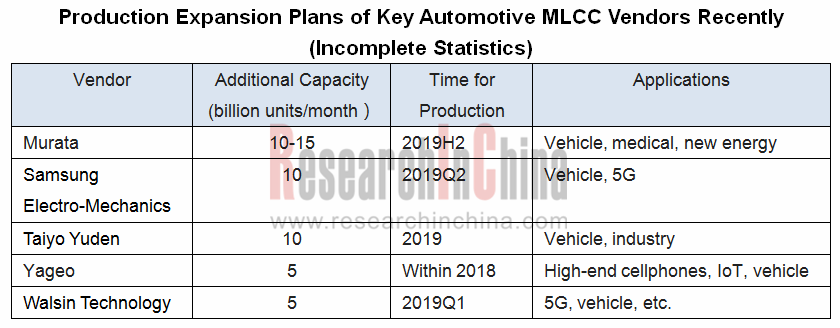
Currently, Murata is the vendor boasting the most market shares worldwide (29%; about 40% in the automotive MLCC market), with the production capacity of 960 billion units/year for the moment. Murata has slashed production of low-end MLCC and related delivery has drawn to an end over the past two years. In 2018, Murata invested $660 million for expanding production of MLCC for medical and automotive use and mass-production is anticipated in 2019.
Samsung Electro-Mechanics has sprung up and has been in the second place worldwide since it outperformed Japan-based TDK in 2009. Impacted by the explosion of Samsung NOTE7, Samsung Electro-Mechanics has tightened control on the quality of products and cut shipments over the recent years, while it planned to invest the additional 10 billion units/month MLCC for cars and 5G products.
TDK canceled product orders involving 700 million MLCCs in 360 models in 2017, and has transferred to focus on medium- and high-end products.
Chinese MLCC vendors has been developing apace over the recent years but are still engaged in supply for consumer electronics. Few companies like Fenghua Advanced Technology have rolled out the products in line with AEC-Q200 criterion. Due to weak strength, Chinese players are still hard to pose a threat to the MLCC giants from Japan, South Korea and Taiwan (China).
The report highlights the following:
 MLCC industry overview (definition, classification, policies, etc.);
Global and China MLCC markets (market size, production capacity, industrial chains, competitive landscape, etc.);
Global and China automotive MLCC markets (market size, production capacity, competitive pattern, etc.);
Eleven automotive MLCC vendors including Murata, Samsung Electro-Mechanics, Kyocera, Taiyo Yuden, TDK, KEMET, Fenghua Advanced Technology, Walsin Technology, Yageo, HolyStone and Chemi-Con (profile, financials, hit products, R&D, manufacturing bases, technical features, etc.);
Eight manufacturers in the upstream of MLCC, including Sakai Chemical Industry, Ferro, Prosperities Dielectrics, Shandong Sinocera Functional Material, Nippon Chemical Industrial, SHOEI, Sumitomo Metal Industries, and ESL.
Automotive Microcontroller Unit (MCU) and Application Scenario Research Report, 2026
Automotive MCU Research: Increased demand for redundant security drives ASIL D-compliant MCU shipments to exceed 100 million units
In a vehicle EEA, MCUs are widely distributed in various functional ...
China Intelligent Cockpit Patent Analysis Report, 2026
Intelligent Cockpit Patent Research: Cockpit AI, In?vehicle Health, and Infotainment Are Upgrade to Scenario?based and Proactive Functions
From a patent perspective, this report explores the cutting?...
Research Report on Application of VLA Large Model in Automobiles and Robots, 2026
Research on Automotive and Robot VLA: Hybrid Architectures Become Mainstream, VLA Integrates with General World Models, and Reinforcement Learning Serves as Core Engine
Vision?Language?Action (VLA) m...
China Charging Infrastructure (Supercharging, Battery Swapping, V2G, etc.) and High-Performance Supercharging Battery Research Report, 2026
Charging and battery swapping research: as 5C+ supercharging vehicle models go into mass production, the pace of OEMs self-building supercharging networks quickens
800-1000V high-voltage platforms ar...
China Passenger Car Electronic Controlled Suspension Industry Report, 2026
Electronic Controlled Suspension Industry Research: As the First Year of Full Active Suspension Unfolds, Three Technical Routes Race Forward
1. Penetration Rate Surges Three Times, and Electronic Con...
Intelligent Driving SoC Research Report, 2026
Research on Intelligent Driving SoCs: Competition Focus Shifts to L3/L4 Embedded Hardware, and Computing Power of Flagship Vehicle Models Exceeds 1,000 TOPS
In terms of intelligent driving system in...
Automotive AI Large Model Technology Research Report, 2026
Automotive AI Large Model Research: Competition Shifts from "Who Has the Stronger Model" to "Who Boasts Higher Link Efficiency"
ResearchInChina released the Automotive AI Large Model Technology Resea...
Intelligent Vehicle Cockpit Domain Controller Research Report, 2026
Cockpit domain controller research: L3 AIDV intelligent cockpit domain controllers are entering a boom period
Driven by multiple factors such as the continuous evolution of the automotive central int...
Automotive Acoustic System (Audio, Multi-Channel) Industry Report, 2026
Automotive Acoustics Research: Multiple Channels, AI Tuning, and Self-Developed Algorithms Drive the Transformation of High-End Cockpit Sound Fields
I. Automotive Audio Hardware Solutions with 6–9 S...
Autonomous Driving Sensor Chip Research Report, 2026
Research on Autonomous Driving Sensor Chips: Deeply Perceiving the Physical World, Sensor Chips Are Playing A “Leading Role” in Intelligence
In 2026, the autonomous driving sensor chip industr...
Passenger Car Corner Module and Wheel‑Side Control System Research Report, 2026
Wheel-side control research: the “last mile” chassis innovation
Wheel-side control dismantles the traditional drive, braking, steering, and suspension control of the chassis from a "centralized" styl...
Embodied Artificial Intelligence (& Humanoid Robot) MCU Research Report, 2026
Research on Humanoid Robot MCUs: Evolution from General-Purpose Control to High-Value Dedicated Chip Solutions Integrated with Edge AI Functions
MCU (Microcontroller Unit) refers to a compact integra...
Intelligent Vehicle Zone Control Unit (ZCU) Research Report, 2026
ZCU Research: Cross-domain integrated ZCUs are becoming the edge computing nodes of the next-generation zonal architecture
Currently, the mainstream zonal architecture is mainly the quasi-central + z...
Automotive Cybersecurity and Data Security Research Report, 2026
Cybersecurity & Data Security Research: Intelligent Connected Vehicles Enter the Era of “Systematic Offense-Defense and AI-Defined Security”.
Centering on the panorama of intelligent connect...
Report on Breakthrough Strategies of OEMs and ADAS Tier 1 Suppliers for Overseas Layout of Intelligent Driving, 2026
Regulatory Breakthrough, Local System Establishment, OEMs Competing for NOA Layout: Overall Trends of China’s Intelligent Driving Overseas Layout in 2026
Research on overseas intelligent driving layo...
OEMs and Tier1s’ Intelligent Cockpit Platform (Hardware and Software) Innovation Strategy Research Report, 2026
Intelligent Cockpit Platform Research: multi-dimensional cockpit system architecture reconstruction for multi-agent collaboration and proactive intelligent services
The intelligent cockpit software s...
Automotive AIOS Research Report, 2026
Automotive AIOS Research: Mass Production Solutions Are Implemented
Mass Production Solutions Are Implemented on A Small Scale.
In 2026, AIOS starts small-scale implementation, helping to improve v...
Automotive Telematics Service Provider (TSP) Research Report, 2026
TSP Research: Leading providers collectively turn to AI agents to provide all-scenario active services
Telematics Service Providers (TSPs) are the core hub of the telematics industry chain, connectin...