Global and China Automotive Domain Control Unit (DCU) Industry Report, 2018-2019
Electronic control unit (ECU) serves as an automotive computer controller. Automotive electronic controller is used to receive and process signals from sensors and export control commands to the actuator to execute. Microprocessors, the core of an automotive ECU, embrace micro control unit (MCU), microprocessor unit (MPU), digital signal processor (DSP) and logic integrated circuits (IC). The global ECU leaders are Bosch, Denso, Continental, Aptiv, Visteon, among others.
As vehicle trend to use more electronics, ECU is making its way into all auto parts from anti-lock braking system, four-wheel drive system, electronically controlled automatic transmission, active suspension system and airbag system to body safety, network, entertainment and sensing and control systems. Vehicles’ consumption of ECU then booms: high-class models use 50-70 ECUs on average, and some even carries more than 100 units.
When the one-to-one correspondence between the growing number of sensors and ECUs gives rise to underperforming vehicles and far more complex circuits, more powerful centralized architectures like domain control unit (DCU) and multi-domain controller (MDC) come as an alternative to the distributed ones.
The concept of domain control unit (DCU) was initiated by tier-1 suppliers like Bosch and Continental as a solution to information security and ECU development bottlenecks. DCU can make systems much more integrated for its powerful hardware computing capacity and availability of sundry software interfaces enable integration of more core functional modules, which means lower requirements on function perception and execution hardware. Moreover, standardized interfaces for data interaction help these components turn into standard ones, thus reducing the spending on research and development or manufacture. In other words, unlike peripheral parts just playing their own roles, a central domain control unit looks at the whole system.
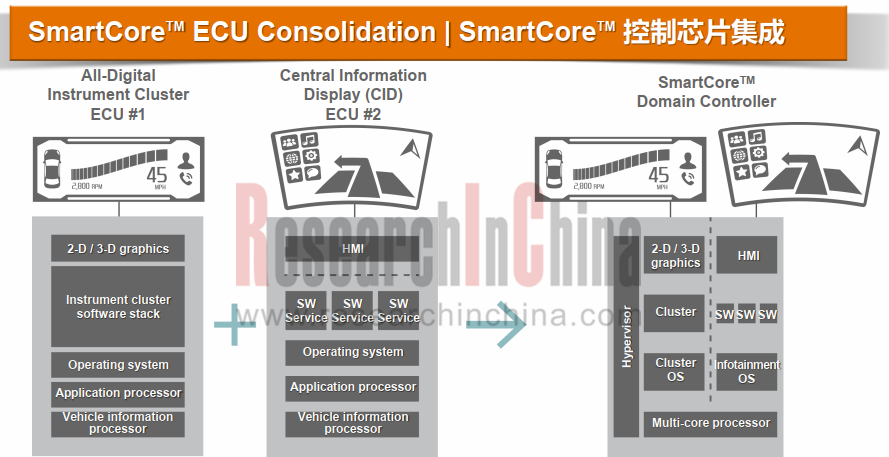
Figure 1: Visteon integrates instrument ECU and head unit ECU into SmartCore cockpit domain controller
Autonomous vehicle requires domain controllers not only to be integrated with versatile capabilities such as multi-sensor fusion, localization, path planning, decision making and control, V2X and high speed communication, but to have interfaces for cameras (mono/stereo), multiple radars, LiDAR, IMU, etc.
To complete number crunching, a domain control unit often needs a built-in core processor with strong computing power for smart cockpit and autonomous driving at all levels. Solution providers include NVIDIA, Infineon, Renesas, TI, NXP and Mobileye. The scheme that powerful multi-core CPU/GPU chips are used to control every domain in a centralized way can replace former distributed automotive electric/electronic architectures (EEA).
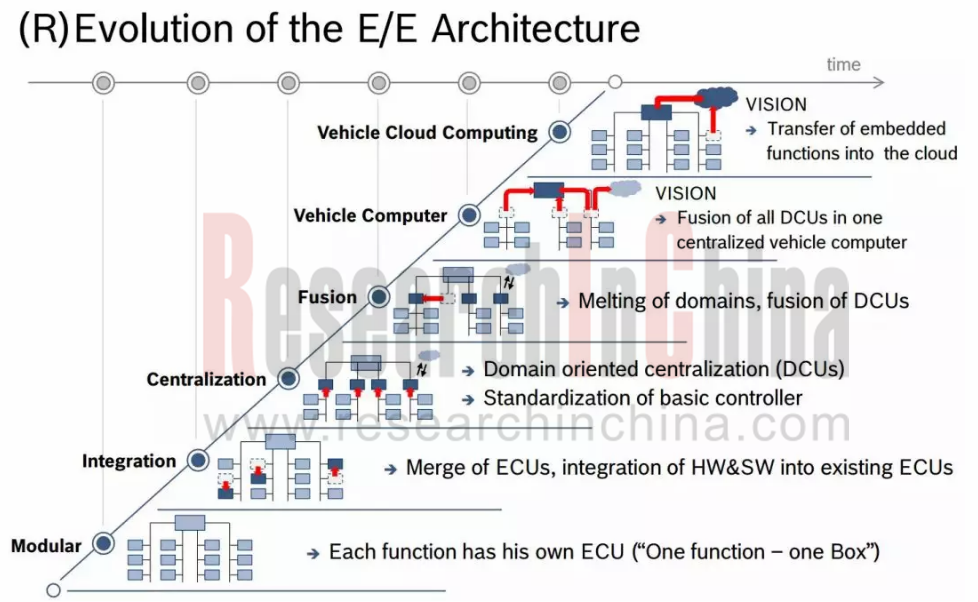
Figure 2: evolution of Bosch E/E architecture. It has six layers, i.e., Modular,Integration, Centralization, Fusion, Vehicle Computer and Vehicle Cloud Computing. DCU is applied to the third layer (Centralization), and MDC the fourth (Fusion).
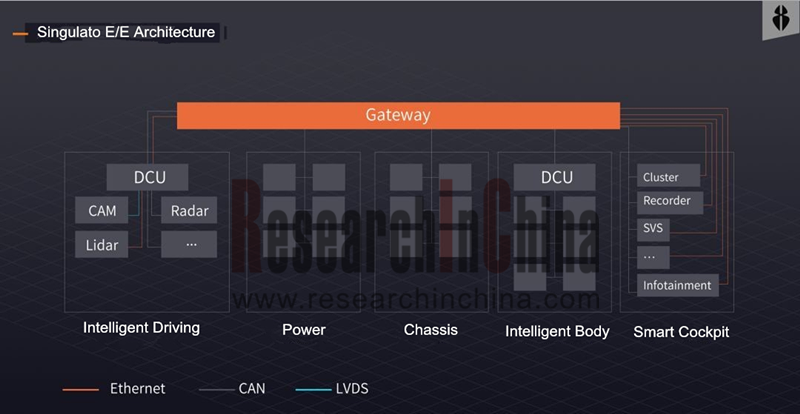
In current stage, most new vehicles adopt DCU-based E/E architectures. In Singulato iS6’s case, a DCU + automotive Ethernet based network topology is used to divide E/E architecture into 5 domains: intelligent driving, smart cockpit, body, chassis and power; an integrated design allows fusion of all sensor data into the intelligent driving domain controller which is in charge of data processing and decision making to implement ADAS functions such as adaptive cruise control, lane keeping and automatic parking. All imply that automakers need to develop their own ADAS/AD systems.
The study by “Cool Wax Gourd”, a technical expert’s Twitter-like Sina Weibo account, shows that: the evolution of three generations of Tesla models from Model S to Model X to Model 3, is actually a process of functional redistribution, namely, developing capabilities based on those from suppliers; Model S E/E architecture has been a fifth-layer one (Vehicle Computer) at the start.
As automotive E/E architectures evolve, there is a big shift in relationship between OEMs and automotive electronics suppliers, too. The trend for integrated automotive electronic hardware leads to the smaller number of electronics suppliers and the more important role of DCU vendors.
Being generally integrated with instrument clusters and head unit, a cockpit domain controller for instance, will be fused with air conditioner control, HUD, rearview mirror, gesture recognition, DMS and even T-BOX and OBU in future.
An autonomous vehicle that generates 4TB data an hour, needs a domain control unit to have some advanced competencies such as multi-sensor fusion and 3D localization.
Central gateway closely tied with domain controllers, takes charge of sending and receiving key security data, and is directly and only connected to the backstage of automakers. Through OTA updates to domain controllers, carmakers can develop new capabilities and ensure network security for faster deployment of functions and software.
DCU vendors and automakers will deepen their partnerships in research and development.
Desay SV argues that: tier-1 suppliers and OEMs will collaborate in the following two ways in the area of autonomous driving domain controller:
First, tier-1 suppliers are devoted to making middleware and hardware, and OEMs develop autonomous driving software. As tier-1 suppliers enjoy edges in producing products at reasonable cost and accelerating commercialization, automakers are bound to partner with them: OEMs assume software design while tier-1 suppliers take on production of hardware and integration of middleware and chip solutions.
Second, tier-1 suppliers choose to work with chip vendors in solution design and research and development of central domain controllers, and then sell their products to OEMs. Examples include Continental ADCU, ZF ProAI and Magna MAX4.
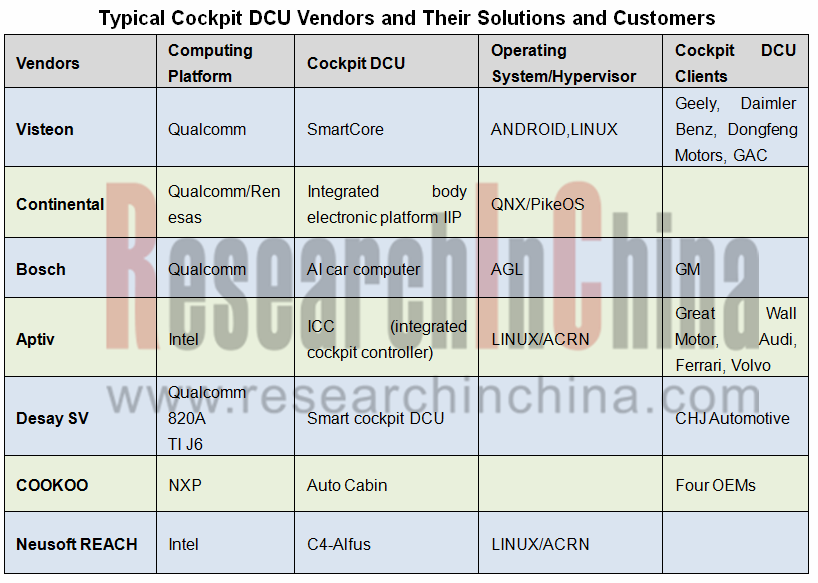
It can be seen from the two tables below that there is a tendency towards cooperation between controller vendors and OEMs, domain controller suppliers and chip vendors, in both cockpit and autonomous driving domain controllers.
Typical Autonomous Driving DCU Vendors and Their Customers and Partners
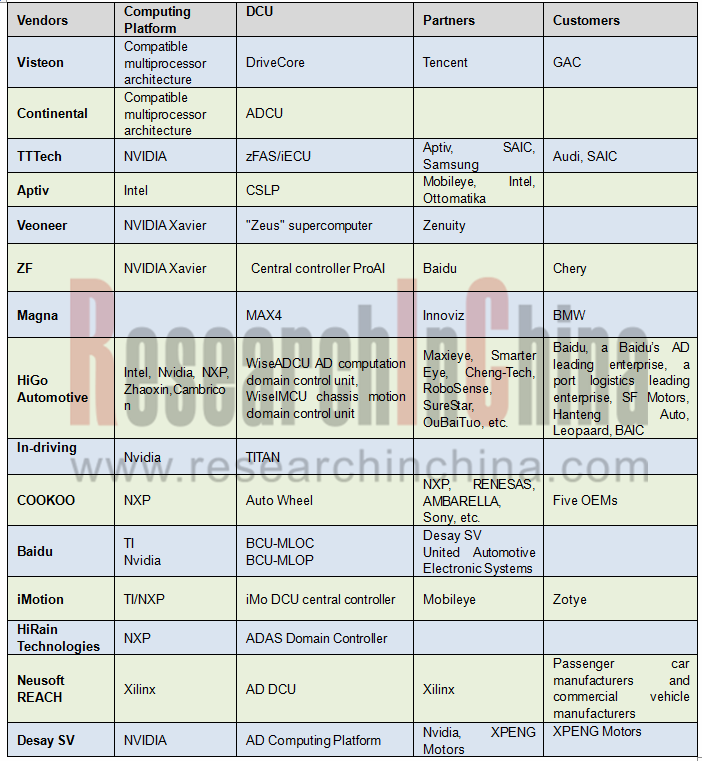
DCU, as a kind of OEM automotive electronics, usually takes over two years from design to mass production and launch. Most of the above suppliers are still researching and developing DCU. Aptiv and Visteon are far ahead of peers and have mass-produced DCU.
The global automotive DCU (cockpit + autonomous driving) shipments will exceed 14 million sets in 2025, with the average annual growth rate of 50.7% between 2019 and 2025, according to ResearchInChina.
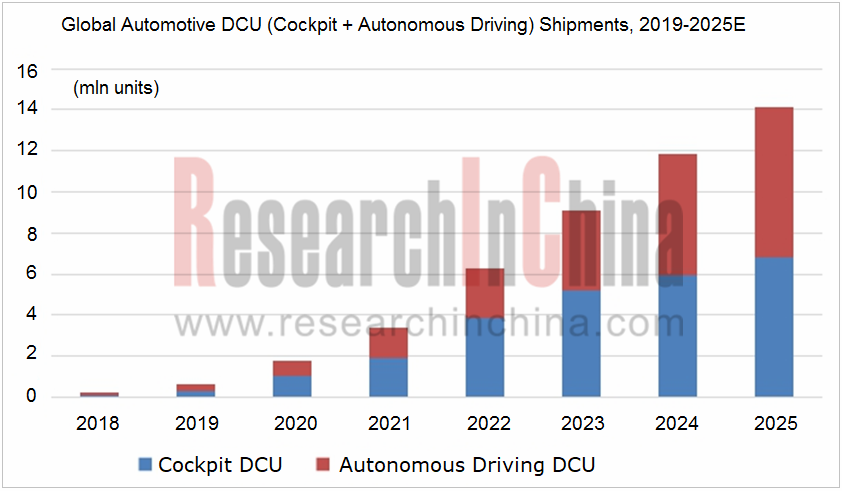
Throughout the DCU industry, Chinese companies have emerged strikingly in the past two years, such as Desay SV, Baidu, Neusoft, HiGO Automotive, COOKOO, In-driving, iMotion, etc., all of which now takes emerging and non-first-tier traditional automakers as their key clients.
Autonomous Driving Domain Controller and Central Computing Unit (CCU) Industry Report, 2026
Autonomous Driving Domain Controller (ADCU) Research: One-Chip CCU solutions are quickly available in vehicles
In China's passenger car market, autonomous driving systems involved in mass production ...
Automotive EMS and ECU Industry Research Report, 2026
Automotive EMS Research: The boundaries between EMS providers and Tier1 suppliers are becoming blurred, and the supply chain model is evolving from a linear chain to a networked structure
Mainstream ...
Automotive Microcontroller Unit (MCU) and Application Scenario Research Report, 2026
Automotive MCU Research: Increased demand for redundant security drives ASIL D-compliant MCU shipments to exceed 100 million units
In a vehicle EEA, MCUs are widely distributed in various functional ...
China Intelligent Cockpit Patent Analysis Report, 2026
Intelligent Cockpit Patent Research: Cockpit AI, In?vehicle Health, and Infotainment Are Upgrade to Scenario?based and Proactive Functions
From a patent perspective, this report explores the cutting?...
Research Report on Application of VLA Large Model in Automobiles and Robots, 2026
Research on Automotive and Robot VLA: Hybrid Architectures Become Mainstream, VLA Integrates with General World Models, and Reinforcement Learning Serves as Core Engine
Vision?Language?Action (VLA) m...
China Charging Infrastructure (Supercharging, Battery Swapping, V2G, etc.) and High-Performance Supercharging Battery Research Report, 2026
Charging and battery swapping research: as 5C+ supercharging vehicle models go into mass production, the pace of OEMs self-building supercharging networks quickens
800-1000V high-voltage platforms ar...
China Passenger Car Electronic Controlled Suspension Industry Report, 2026
Electronic Controlled Suspension Industry Research: As the First Year of Full Active Suspension Unfolds, Three Technical Routes Race Forward
1. Penetration Rate Surges Three Times, and Electronic Con...
Intelligent Driving SoC Research Report, 2026
Research on Intelligent Driving SoCs: Competition Focus Shifts to L3/L4 Embedded Hardware, and Computing Power of Flagship Vehicle Models Exceeds 1,000 TOPS
In terms of intelligent driving system in...
Automotive AI Large Model Technology Research Report, 2026
Automotive AI Large Model Research: Competition Shifts from "Who Has the Stronger Model" to "Who Boasts Higher Link Efficiency"
ResearchInChina released the Automotive AI Large Model Technology Resea...
Intelligent Vehicle Cockpit Domain Controller Research Report, 2026
Cockpit domain controller research: L3 AIDV intelligent cockpit domain controllers are entering a boom period
Driven by multiple factors such as the continuous evolution of the automotive central int...
Automotive Acoustic System (Audio, Multi-Channel) Industry Report, 2026
Automotive Acoustics Research: Multiple Channels, AI Tuning, and Self-Developed Algorithms Drive the Transformation of High-End Cockpit Sound Fields
I. Automotive Audio Hardware Solutions with 6–9 S...
Autonomous Driving Sensor Chip Research Report, 2026
Research on Autonomous Driving Sensor Chips: Deeply Perceiving the Physical World, Sensor Chips Are Playing A “Leading Role” in Intelligence
In 2026, the autonomous driving sensor chip industr...
Passenger Car Corner Module and Wheel‑Side Control System Research Report, 2026
Wheel-side control research: the “last mile” chassis innovation
Wheel-side control dismantles the traditional drive, braking, steering, and suspension control of the chassis from a "centralized" styl...
Embodied Artificial Intelligence (& Humanoid Robot) MCU Research Report, 2026
Research on Humanoid Robot MCUs: Evolution from General-Purpose Control to High-Value Dedicated Chip Solutions Integrated with Edge AI Functions
MCU (Microcontroller Unit) refers to a compact integra...
Intelligent Vehicle Zone Control Unit (ZCU) Research Report, 2026
ZCU Research: Cross-domain integrated ZCUs are becoming the edge computing nodes of the next-generation zonal architecture
Currently, the mainstream zonal architecture is mainly the quasi-central + z...
Automotive Cybersecurity and Data Security Research Report, 2026
Cybersecurity & Data Security Research: Intelligent Connected Vehicles Enter the Era of “Systematic Offense-Defense and AI-Defined Security”.
Centering on the panorama of intelligent connect...
Report on Breakthrough Strategies of OEMs and ADAS Tier 1 Suppliers for Overseas Layout of Intelligent Driving, 2026
Regulatory Breakthrough, Local System Establishment, OEMs Competing for NOA Layout: Overall Trends of China’s Intelligent Driving Overseas Layout in 2026
Research on overseas intelligent driving layo...
OEMs and Tier1s’ Intelligent Cockpit Platform (Hardware and Software) Innovation Strategy Research Report, 2026
Intelligent Cockpit Platform Research: multi-dimensional cockpit system architecture reconstruction for multi-agent collaboration and proactive intelligent services
The intelligent cockpit software s...