Global and China Automated Parking and Autonomous Parking Industry Report, 2018-2019
Automated parking system (APS) or automated parking assistant (APA) can measure the distance and angle between vehicle body and surroundings, collect sensor data to work out operation flow whilst automatically tuning the steering wheel, brake and throttle to pull into the parking space. Automated parking system can be divided by technical grades into semi-automatic parking (automatic steering only), fully automated parking (inclusive of automatic steering and automatic forwarding & reversing), autonomous valet parking (AVP), among others.
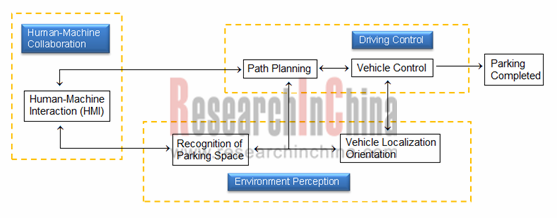
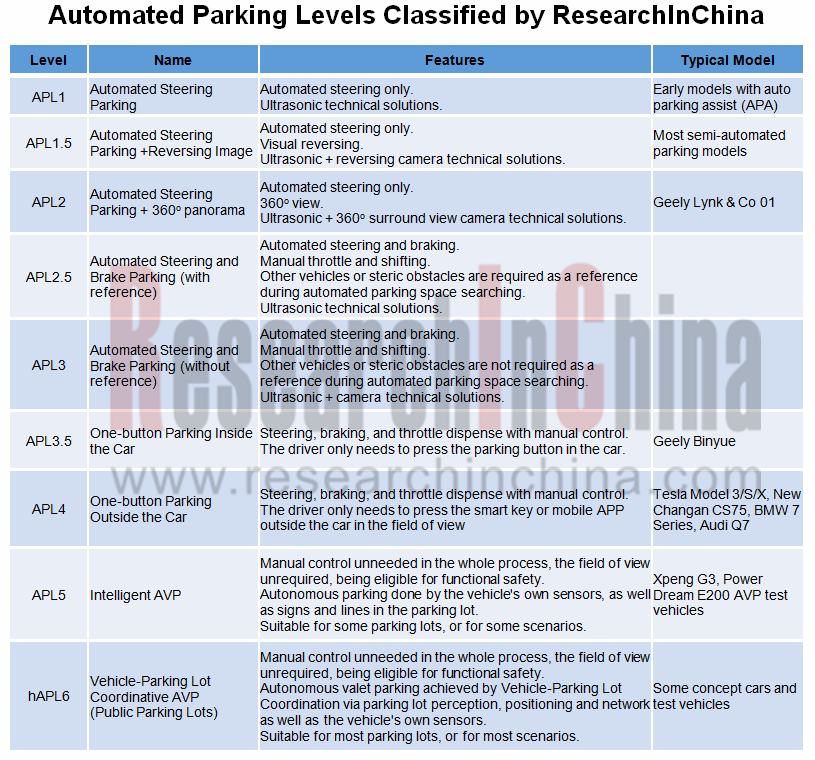
Automated parking system is generally composed of environment perception system, central control system (path planning system) and execution system (vehicle control system). Taking the diversity of automated parking systems into account, ResearchInChina recently rolled out the Global and China Automated Parking and Autonomous Parking Industry Report, 2018-2019 where all automated parking systems are classified into nine levels including APL1, APL1.5, APL2, APL2.5, APL3, APL3.5, APL4, APL5 and APL6. (See the table below)
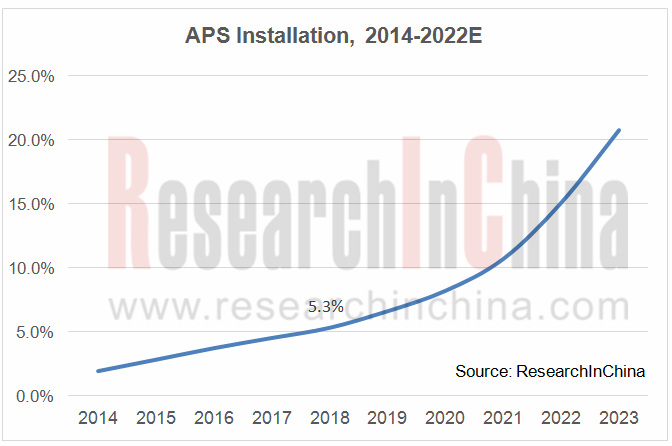
According to ResearchInChina, the APS configuration rate of passenger vehicles in Chinese market was 5.3% in 2018, a not high figure due to technical immaturity shown as follows:
In the mass-produced vehicle models with APS, the automated parking system still desires to be improved in real experience and is faced with system recognition error and the occurrence of scratches.
Most APS renders ultrasonic sensors for monitoring parking spaces, but ultrasonic sensors are vulnerable to surface stains & defects, raindrops, ice, snow, etc., and thus fail to be brought into full play.
Recognition of parking space and the process of automated parking are subject to environmental factors. The currently mass-produced APS system, for example, usually cannot recognize well lids, pits or loose kerbs, tiny objects on the parking space, among others.
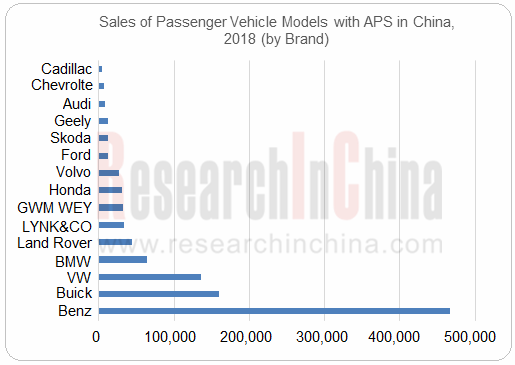
The current best-selling models with APS function are primarily from foreign automakers like Benz, Buick, Volkswagen, BMW and Land Rover as well as China-made premium brands LYNK&CO, Great Wall Motor’s WEY, etc.
As automotive intelligence technologies and sensor technologies in particular are developing apace, OEMs are beginning to apply more sensors in the automated parking system, facilitating maturity of the APS technologies. Automated parking has already been a highlight of new car sales.
Geely SUV Binyue is one of the five most successful new cars in Chinese market in 2018. It debuted on October 31, 2018, with the sales outnumbering ten thousand units and reaching 10,100 units in the first month of launch, 13,222 units in December 2018 and 14,627 units in January 2019. Binyue is provided with fully automated parking system that enables horizontal pull-in, vertical pull-in as well as horizontal pull-out by only a key-touch whilst the driver does not have any control on steering wheel, throttle and brake. Binyue has the automated parking level APL3.5.
CS75 (the hit model of Changan Automobile) has the APA4.0 parking system which enable a man standing outside the car to realize one-key parking. Only a touch on the automated parking button is needed, the car can search the tailgate automatically, and performs operations such as forwarding, reversing and wheel steering. The entire parking process needs no driver engagement. CS75 has an automated parking level at APL4.
BAIC plans to have the majority of its vehicle models be equipped with the automated parking technologies from July 2019.
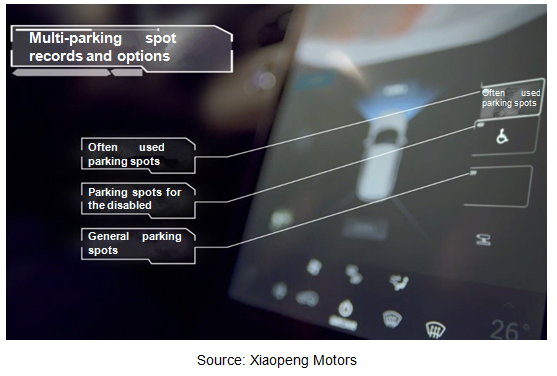
Among emerging car manufacturers, Xiaopeng Motors focuses on automatic parking. Xpeng G3 carries 20 environmental sensors including 12 ultrasonic sensors, 5 vision sensors and 3 radars. That XPENG uses numerous sensor systems to make parking spaces recognized more accurately and lift probability of success in parking is an effective solution to the problems of low parking space recognition and many unsuccessful parking cases, adding more automatic parking capabilities. Xiaopeng says that success rate of its car automatic parking system exceeds 70% compared with less than 5% in general automatic parking and Tesla’s 13%.
As automatic parking technology grows mature and OEMs invest more in APS, installation of such a system will soar from 2020 after years of slow increase, expectedly outstripping 20% in 2023.
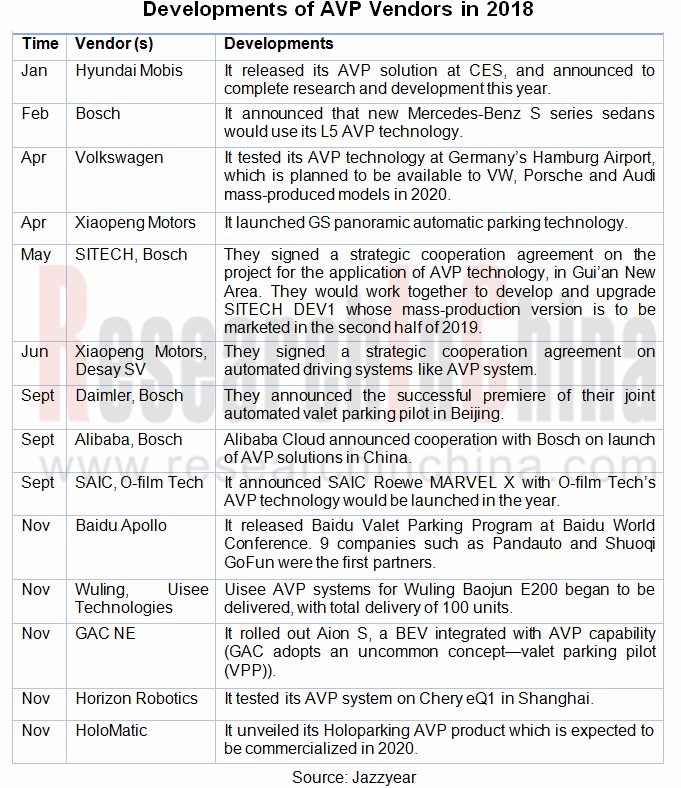
Traditional automakers follow an upgrading automated parking technology roadmap in ToC market, while Tier1 suppliers, technology firms and start-ups also have made an attempt to deploy automated valet parking (AVP) pilot projects at one go in ToB market.
Software-Defined Vehicles in 2026: Software Supply Chain Panorama and Business Models Research
Research on Automotive Software Business Models: Exploration of Token Economy, AI Service Revenue Sharing and Other Businesses
Under the Trend of AI Agents: Exploration of Business Models Based on T...
New Energy Commercial Vehicle 800-1000V High-Voltage Platform & Supply Chain Panorama Research Report, 2026
Research on 800V Architecture of Commercial Vehicles: New Energy Penetration Rate Exceeds 35%, and 800V Full-Domain High-Voltage Architecture Rapidly Penetrates Heavy-Duty Trucks
Explosive Growth in ...
ADAS and Autonomous Driving Tier 1 Suppliers Research Report, 2026 – Chinese Companies
Intelligent Driving Industry Leap: From Widespread L2.9 Adoption toward Physical AI and New Full?Domain Mobility Ecosystem
As vehicle intelligence advances, the installations and penetration rate of...
Vehicle-Road-Cloud Integration and C-V2X Industry Report, 2026
Vehicle-Road-Cloud and C-V2X Research: with the three-tier promotion system of "top-level planning + mandatory pilot + evaluation binding", the industry turning point is approachingThis report focuses...
China OEM Data Capability Analysis Report, 2026
OEM Data Capability Research: 24 OEMs × 9 Capability Domains, Who Takes the Lead?
An L4 autonomous driving R&D and test vehicle can generate approximately 10TB of raw data per single day — data v...
Autonomous Driving Domain Controller and Central Computing Unit (CCU) Industry Report, 2026
Autonomous Driving Domain Controller (ADCU) Research: One-Chip CCU solutions are quickly available in vehicles
In China's passenger car market, autonomous driving systems involved in mass production ...
Automotive EMS and ECU Industry Research Report, 2026
Automotive EMS Research: The boundaries between EMS providers and Tier1 suppliers are becoming blurred, and the supply chain model is evolving from a linear chain to a networked structure
Mainstream ...
Automotive Microcontroller Unit (MCU) and Application Scenario Research Report, 2026
Automotive MCU Research: Increased demand for redundant security drives ASIL D-compliant MCU shipments to exceed 100 million units
In a vehicle EEA, MCUs are widely distributed in various functional ...
China Intelligent Cockpit Patent Analysis Report, 2026
Intelligent Cockpit Patent Research: Cockpit AI, In?vehicle Health, and Infotainment Are Upgrade to Scenario?based and Proactive Functions
From a patent perspective, this report explores the cutting?...
Research Report on Application of VLA Large Model in Automobiles and Robots, 2026
Research on Automotive and Robot VLA: Hybrid Architectures Become Mainstream, VLA Integrates with General World Models, and Reinforcement Learning Serves as Core Engine
Vision?Language?Action (VLA) m...
China Charging Infrastructure (Supercharging, Battery Swapping, V2G, etc.) and High-Performance Supercharging Battery Research Report, 2026
Charging and battery swapping research: as 5C+ supercharging vehicle models go into mass production, the pace of OEMs self-building supercharging networks quickens
800-1000V high-voltage platforms ar...
China Passenger Car Electronic Controlled Suspension Industry Report, 2026
Electronic Controlled Suspension Industry Research: As the First Year of Full Active Suspension Unfolds, Three Technical Routes Race Forward
1. Penetration Rate Surges Three Times, and Electronic Con...
Intelligent Driving SoC Research Report, 2026
Research on Intelligent Driving SoCs: Competition Focus Shifts to L3/L4 Embedded Hardware, and Computing Power of Flagship Vehicle Models Exceeds 1,000 TOPS
In terms of intelligent driving system in...
Automotive AI Large Model Technology Research Report, 2026
Automotive AI Large Model Research: Competition Shifts from "Who Has the Stronger Model" to "Who Boasts Higher Link Efficiency"
ResearchInChina released the Automotive AI Large Model Technology Resea...
Intelligent Vehicle Cockpit Domain Controller Research Report, 2026
Cockpit domain controller research: L3 AIDV intelligent cockpit domain controllers are entering a boom period
Driven by multiple factors such as the continuous evolution of the automotive central int...
Automotive Acoustic System (Audio, Multi-Channel) Industry Report, 2026
Automotive Acoustics Research: Multiple Channels, AI Tuning, and Self-Developed Algorithms Drive the Transformation of High-End Cockpit Sound Fields
I. Automotive Audio Hardware Solutions with 6–9 S...
Autonomous Driving Sensor Chip Research Report, 2026
Research on Autonomous Driving Sensor Chips: Deeply Perceiving the Physical World, Sensor Chips Are Playing A “Leading Role” in Intelligence
In 2026, the autonomous driving sensor chip industr...
Passenger Car Corner Module and Wheel‑Side Control System Research Report, 2026
Wheel-side control research: the “last mile” chassis innovation
Wheel-side control dismantles the traditional drive, braking, steering, and suspension control of the chassis from a "centralized" styl...