Global and China Low Speed Autonomous Driving Industry Report, 2019-2020
In 2019, low speed autonomous driving market tended to calm down, with more regular pilots but on small scale. In 2020, the COVID-19 pandemic brings new opportunities to low speed autonomous delivery industry.
Autonomous minibuses aim to meet the needs for picking up passengers at the front and rear ends. A combination of factors such as technology, cost and rules impede the emergence of large, profitable autonomous minibus companies. Some players plan commercial operation in 2020. Navya as the one deploying the most autonomous minibuses worldwide had sold a total of 164 autonomous minibuses by the end of 2019. Yet it announced that it would no longer sell vehicles and turn to sales of system technologies considering high cost and meager profit, and that in future vehicles would be produced purely for research and development, test and exhibition. EasyMile and May Mobility have an autonomous minibus fleet of 80 units and 25 units, separately, with pilot run in the US, Europe and beyond.
In 2019, some companies realized normal commercial operation of projects on public roads, for example, EasyMile had more than 230 projects worldwide and enabled normal operation on some Canadian public roads.
Baidu Apolong, an autonomous minibus which debuted in 2018, springs up the most rapidly in China. According to the data released, over 100 units of Apolong minibuses already go into operation. Apart from Apolong, in 2019 several bus manufacturers in China also rolled out their own autonomous minibuses. Examples include Uisee Technology which ran autonomous shuttle buses in places such as Guangzhou Baiyun International Airport, Nanning Garden Expo Park and Xingtai Garden Expo Park.
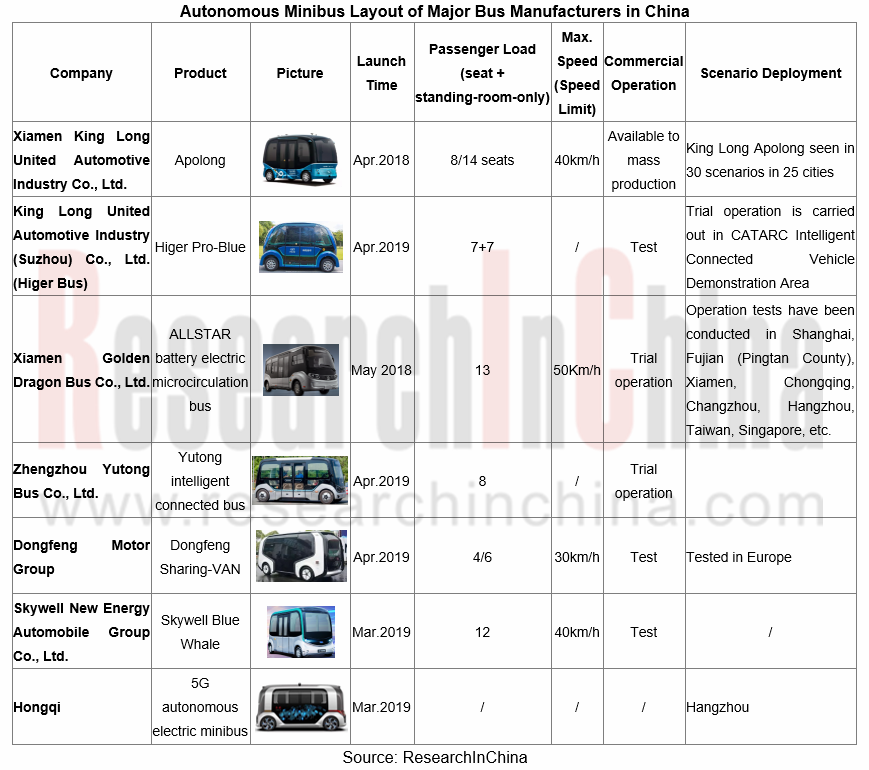
Low speed autonomous delivery vehicle market targets demand for last-mile delivery. In 2019, autonomous delivery vehicle market was advancing steadily. Quite a few companies explored scenario application, with normal trials under way. For instance, Neolix Technologies Co., Ltd. launched an autonomous retail vehicle and put it into trial operation in several parks of Beijing; in late 2019, UISEE deployed autonomous luggage vehicles for normal operation at Hong Kong International Airport.
The problems like high cost, imperfect policies and regulations as well as technical limitations are however still in the way of operating autonomous delivery vehicles on large scale.
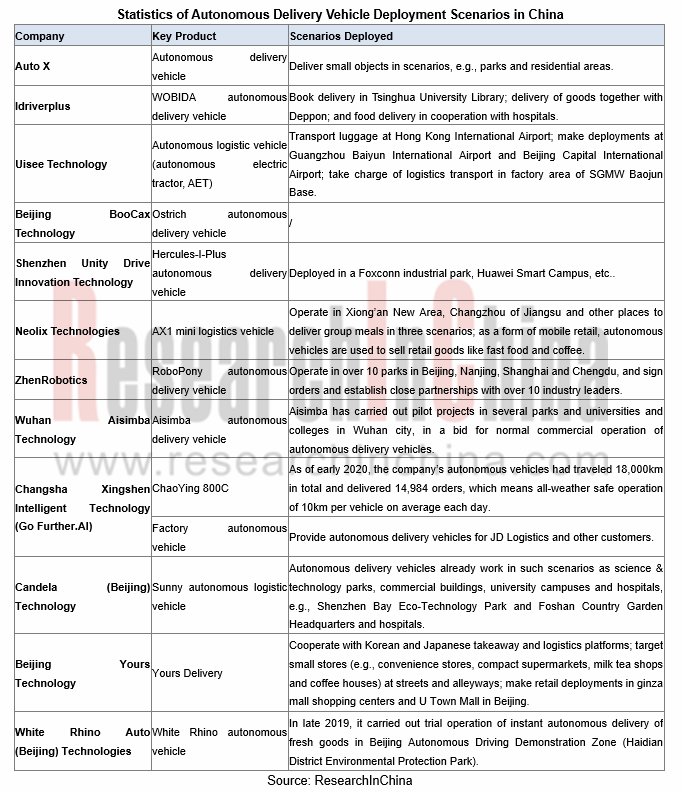
In early 2020, autonomous delivery vehicles of companies including JD Logistics, Neolix Technologies, Idriverplus, Uisee Technology and Meituan joined in the fight against COVID-19, creating new opportunities for autonomous delivery industry.
The attempts on operation of autonomous delivery vehicles on real roads are a boon for large-scale deployments. For example, JD Logistics intelligent delivery robots navigated by Beidou satellites accomplished intelligent delivery from the JD Logistics Wuhan Renhe Station to the No.9 Hospital of Wuhan at a speed of 15km/h; in February 2020, Neolix Technologies had 18 autonomous vehicles in anti-epidemic efforts in Wuhan Leishenshan Hospital and communities of the city; during the outbreak, White Rhino Auto (Beijing) Technologies helped Wuhan Guanggu Mobile Cabin Hospital distribute materials, and provided autonomous delivery services (vegetables and fruits) for communities along a Haidian district demonstration road.
The roleplaying of autonomous vehicles during the epidemic is welcomed by people, in readiness for wider application of autonomous vehicles.
In this period, quite a few autonomous delivery vehicle companies closed a new funding round. Examples include Uisee Technology which finished a series B funding round (where Bosch was an investor) in February 2020; Neolix Technologies receiving investment for its A+ funding round from investors like Leading Ideal in March 2020; and White Rhino Auto raising funds from Chentao Capital in the angel funding round also in March.
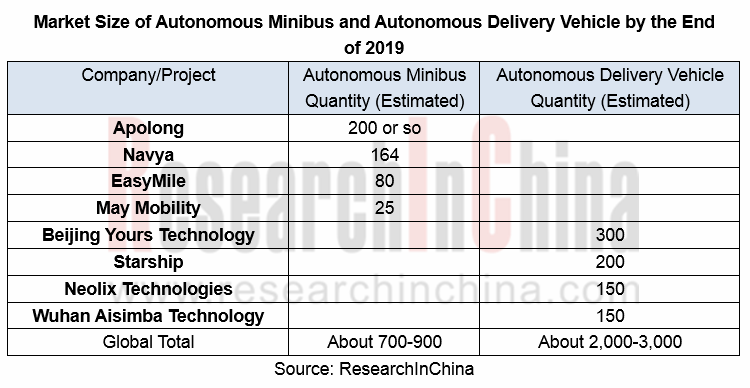
In 2019, there existed altogether 700 to 900 autonomous minibuses worldwide, and about 2,000 to 3,000 autonomous delivery vehicles, a figure projected to outnumber 10,000 units in 2020.
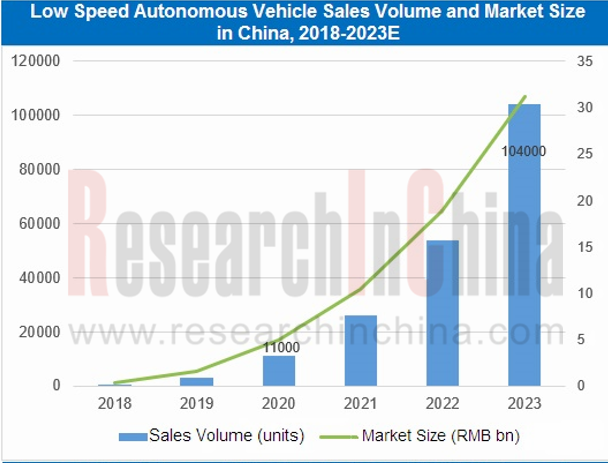
11,000 units of low speed autonomous vehicle will be sold in China in 2020, according to our prediction for the market in early 2019, but the sales figure in 2020 is now trimmed to 15,000 units considering that a few segments enjoy better-than-expected growth.
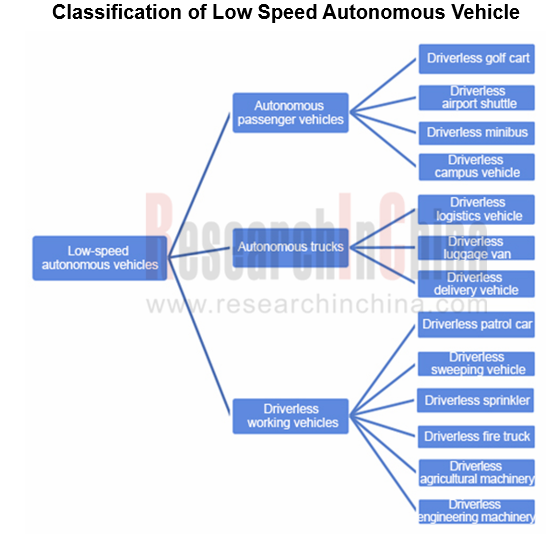
From our classification block diagram above, it can be seen that a report is unable to cover dynamics of all low speed autonomous vehicle segments. On the basis, we prepare two reports on low speed autonomous vehicle: Global and China Low Speed Autonomous Driving Industry Report, 2019-2020, and Global and China Special Autonomous Vehicle (Autonomous Working Vehicle) Industry Report, 2019-2020.
Automotive Microcontroller Unit (MCU) and Application Scenario Research Report, 2026
Automotive MCU Research: Increased demand for redundant security drives ASIL D-compliant MCU shipments to exceed 100 million units
In a vehicle EEA, MCUs are widely distributed in various functional ...
China Intelligent Cockpit Patent Analysis Report, 2026
Intelligent Cockpit Patent Research: Cockpit AI, In?vehicle Health, and Infotainment Are Upgrade to Scenario?based and Proactive Functions
From a patent perspective, this report explores the cutting?...
Research Report on Application of VLA Large Model in Automobiles and Robots, 2026
Research on Automotive and Robot VLA: Hybrid Architectures Become Mainstream, VLA Integrates with General World Models, and Reinforcement Learning Serves as Core Engine
Vision?Language?Action (VLA) m...
China Charging Infrastructure (Supercharging, Battery Swapping, V2G, etc.) and High-Performance Supercharging Battery Research Report, 2026
Charging and battery swapping research: as 5C+ supercharging vehicle models go into mass production, the pace of OEMs self-building supercharging networks quickens
800-1000V high-voltage platforms ar...
China Passenger Car Electronic Controlled Suspension Industry Report, 2026
Electronic Controlled Suspension Industry Research: As the First Year of Full Active Suspension Unfolds, Three Technical Routes Race Forward
1. Penetration Rate Surges Three Times, and Electronic Con...
Intelligent Driving SoC Research Report, 2026
Research on Intelligent Driving SoCs: Competition Focus Shifts to L3/L4 Embedded Hardware, and Computing Power of Flagship Vehicle Models Exceeds 1,000 TOPS
In terms of intelligent driving system in...
Automotive AI Large Model Technology Research Report, 2026
Automotive AI Large Model Research: Competition Shifts from "Who Has the Stronger Model" to "Who Boasts Higher Link Efficiency"
ResearchInChina released the Automotive AI Large Model Technology Resea...
Intelligent Vehicle Cockpit Domain Controller Research Report, 2026
Cockpit domain controller research: L3 AIDV intelligent cockpit domain controllers are entering a boom period
Driven by multiple factors such as the continuous evolution of the automotive central int...
Automotive Acoustic System (Audio, Multi-Channel) Industry Report, 2026
Automotive Acoustics Research: Multiple Channels, AI Tuning, and Self-Developed Algorithms Drive the Transformation of High-End Cockpit Sound Fields
I. Automotive Audio Hardware Solutions with 6–9 S...
Autonomous Driving Sensor Chip Research Report, 2026
Research on Autonomous Driving Sensor Chips: Deeply Perceiving the Physical World, Sensor Chips Are Playing A “Leading Role” in Intelligence
In 2026, the autonomous driving sensor chip industr...
Passenger Car Corner Module and Wheel‑Side Control System Research Report, 2026
Wheel-side control research: the “last mile” chassis innovation
Wheel-side control dismantles the traditional drive, braking, steering, and suspension control of the chassis from a "centralized" styl...
Embodied Artificial Intelligence (& Humanoid Robot) MCU Research Report, 2026
Research on Humanoid Robot MCUs: Evolution from General-Purpose Control to High-Value Dedicated Chip Solutions Integrated with Edge AI Functions
MCU (Microcontroller Unit) refers to a compact integra...
Intelligent Vehicle Zone Control Unit (ZCU) Research Report, 2026
ZCU Research: Cross-domain integrated ZCUs are becoming the edge computing nodes of the next-generation zonal architecture
Currently, the mainstream zonal architecture is mainly the quasi-central + z...
Automotive Cybersecurity and Data Security Research Report, 2026
Cybersecurity & Data Security Research: Intelligent Connected Vehicles Enter the Era of “Systematic Offense-Defense and AI-Defined Security”.
Centering on the panorama of intelligent connect...
Report on Breakthrough Strategies of OEMs and ADAS Tier 1 Suppliers for Overseas Layout of Intelligent Driving, 2026
Regulatory Breakthrough, Local System Establishment, OEMs Competing for NOA Layout: Overall Trends of China’s Intelligent Driving Overseas Layout in 2026
Research on overseas intelligent driving layo...
OEMs and Tier1s’ Intelligent Cockpit Platform (Hardware and Software) Innovation Strategy Research Report, 2026
Intelligent Cockpit Platform Research: multi-dimensional cockpit system architecture reconstruction for multi-agent collaboration and proactive intelligent services
The intelligent cockpit software s...
Automotive AIOS Research Report, 2026
Automotive AIOS Research: Mass Production Solutions Are Implemented
Mass Production Solutions Are Implemented on A Small Scale.
In 2026, AIOS starts small-scale implementation, helping to improve v...
Automotive Telematics Service Provider (TSP) Research Report, 2026
TSP Research: Leading providers collectively turn to AI agents to provide all-scenario active services
Telematics Service Providers (TSPs) are the core hub of the telematics industry chain, connectin...