Domain control unit shipments will boom in 2021.
When the one-to-one correspondence between the growing number of sensors and electronic control units (ECU) leads to underperforming vehicles and adds circuit complexity, more powerful centralized architectures like domain control unit (DCU) and multi-domain controller (MDC) come as an alternative to the distributed ones.
As concerns the tendency of domain controller, Vector conceives three stages of E/E architecture development: controller-centric, DCU, and central computer. Intelligent vehicle will ultimately be a mobile super computer and data center, and a new Wintel will come into being. In future, computing platform, operating system and application software will matter the most to the highly automated vehicles; multimedia multi-domain controllers and central domain controllers are likely to be combined into one.
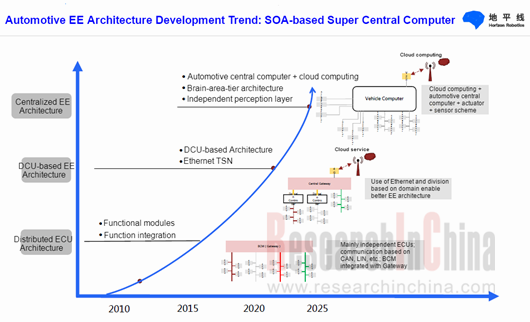
In response to the disruption, Volkswagen plans adoption of a unified automotive E/E architecture; BMW will introduce central communication services and service-oriented architecture (SOA) in its next-generation E/E architecture; the smart vehicle architecture (SVA) launched by Aptiv breaks the bottleneck of conventional architectures, providing frame scalability for next-generation intelligent vehicles. The new E/E architectures will be built on the concept of central computer-layer-area, embodying the philosophy of SOA.
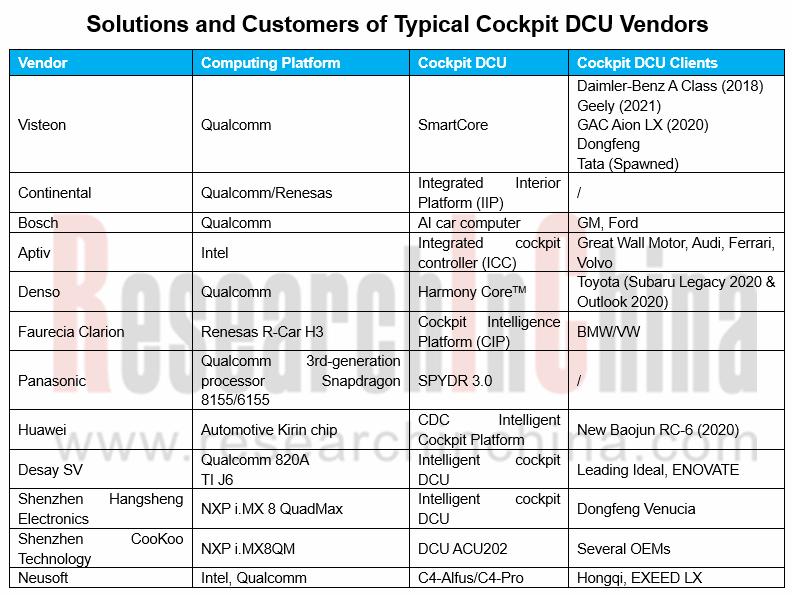
As to DCU, next-generation smart cockpit system based on cockpit DCU enables functionality of cockpit electronic system on a unified software and hardware platform. Cockpit electronic system offering intelligent interaction and scenarios as well as personalized services, will be a foundation for human-vehicle interaction and vehicle-to-everything (V2X) communication. Visteon argues that by 2023, intelligent cockpit integrated with LCD dashboard, center console and co-pilot infotainment system will be based entirely on single-ECU domain control platform.
Globally, Visteon, Continental, Bosch and Aptiv dominate the cockpit DCU market; Chinese players like Huawei, Desay SV, Shenzhen Hangsheng Electronics and Neusoft race to unveil their cockpit DCU solutions.
As for cockpit chip, typical products are comprised of Qualcomm 820A, Intel Atom, NXP i.MX8, Renesas R-CAR H3 and TI Jacinto family. Notably, the prevailing Qualcomm 820A processor platform has been ordered by 18 out of the 25 world-renowned OEMs, with the order intake recording $5.5 billion or so.
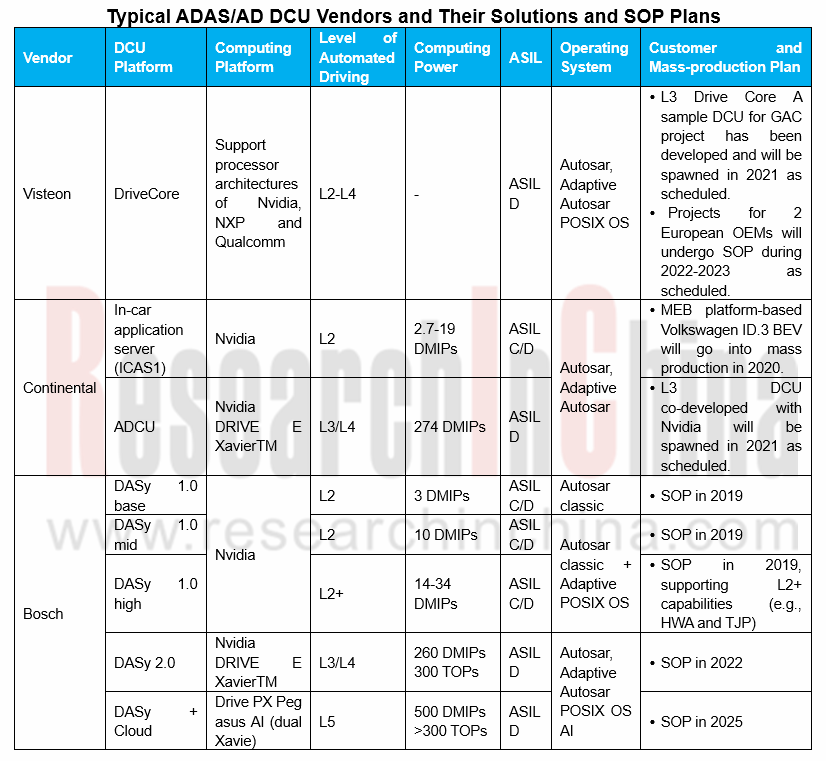
In the ADAS/AD DCU market, most of those in use for Level 1 driving assistance employ separate ECU to control. ADAS ECU which is developed mainly for Level 2 driving assistance is utilized to combine LDW/LKA and AEB. It is in the era of Level 2+, Level 3 and Level 4 automated driving that the demand for autonomous driving domain control unit (AD DCU) will be soaring.
Tier-1 suppliers worldwide already deploy ADAS/AD DCU such as Visteon DriveCore, Bosch DASy, Continental ADCU, ZF ProAI, Veoneer Zeus and Magna MAX4. In China, such typical products include iECU (co-developed by SAIC and TTTech), Huawei MDC (MobileData Center) intelligent driving DCU, IN-DRIVING TITAN, and Neusoft Reach CPDC-II DCU/CPDC-III central computer.
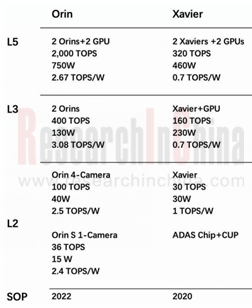
When it comes to autonomous driving chip, Nvidia is absolutely the leader with Nvidia Drive PX2 and Nvidia Drive Xavier being widely deployed by vendors. In December 2019, Nvidia introduced DRIVE AGX Orin, a software-defined platform for Level 5 automated driving, with nearly 7x the performance of the previous generation SoC Xaiver. The Orin SoC integrates NVIDIA’s next-generation GPU architecture and Arm Hercules CPU cores, as well as new deep learning and computer vision accelerators that, in aggregate, deliver 2,000 TOPS.
Other autonomous driving chips include TI TDA4, Qualcomm? Snapdragon Ride?, NXP S32 family, and Mobileye EyeQ family.
In the next three to five years, among DCU market segments, cockpit DCU will see a faster growth rate and a larger market than autonomous driving DCU because it is easier to spawn cockpit DCUs at lower cost; the surging demand for intelligent cockpits, which is fueled by the availability of 5G in vehicles, will drive up cockpit DCU shipments to explode in 2021 on the basis of OEM’s and Tier1’s progress in mass production.
In the ADAS/AD DCU field, inadequate regulations and immature technologies will expectedly make it hard to apply Level 3/Level 4 automated driving technologies on large scale in the upcoming three to five years. OEMs, tier-1 suppliers and chip vendors are working to mass produce L2+ autonomous vehicles. It is predicted that production of Level 3/Level 4 autonomous vehicles will peak around 2025, but business-oriented vehicles will play the key role, with roughly 5 million units of ADAD/AD DCUs for passenger cars to be shipped worldwide in 2025.
Automotive Microcontroller Unit (MCU) and Application Scenario Research Report, 2026
Automotive MCU Research: Increased demand for redundant security drives ASIL D-compliant MCU shipments to exceed 100 million units
In a vehicle EEA, MCUs are widely distributed in various functional ...
China Intelligent Cockpit Patent Analysis Report, 2026
Intelligent Cockpit Patent Research: Cockpit AI, In?vehicle Health, and Infotainment Are Upgrade to Scenario?based and Proactive Functions
From a patent perspective, this report explores the cutting?...
Research Report on Application of VLA Large Model in Automobiles and Robots, 2026
Research on Automotive and Robot VLA: Hybrid Architectures Become Mainstream, VLA Integrates with General World Models, and Reinforcement Learning Serves as Core Engine
Vision?Language?Action (VLA) m...
China Charging Infrastructure (Supercharging, Battery Swapping, V2G, etc.) and High-Performance Supercharging Battery Research Report, 2026
Charging and battery swapping research: as 5C+ supercharging vehicle models go into mass production, the pace of OEMs self-building supercharging networks quickens
800-1000V high-voltage platforms ar...
China Passenger Car Electronic Controlled Suspension Industry Report, 2026
Electronic Controlled Suspension Industry Research: As the First Year of Full Active Suspension Unfolds, Three Technical Routes Race Forward
1. Penetration Rate Surges Three Times, and Electronic Con...
Intelligent Driving SoC Research Report, 2026
Research on Intelligent Driving SoCs: Competition Focus Shifts to L3/L4 Embedded Hardware, and Computing Power of Flagship Vehicle Models Exceeds 1,000 TOPS
In terms of intelligent driving system in...
Automotive AI Large Model Technology Research Report, 2026
Automotive AI Large Model Research: Competition Shifts from "Who Has the Stronger Model" to "Who Boasts Higher Link Efficiency"
ResearchInChina released the Automotive AI Large Model Technology Resea...
Intelligent Vehicle Cockpit Domain Controller Research Report, 2026
Cockpit domain controller research: L3 AIDV intelligent cockpit domain controllers are entering a boom period
Driven by multiple factors such as the continuous evolution of the automotive central int...
Automotive Acoustic System (Audio, Multi-Channel) Industry Report, 2026
Automotive Acoustics Research: Multiple Channels, AI Tuning, and Self-Developed Algorithms Drive the Transformation of High-End Cockpit Sound Fields
I. Automotive Audio Hardware Solutions with 6–9 S...
Autonomous Driving Sensor Chip Research Report, 2026
Research on Autonomous Driving Sensor Chips: Deeply Perceiving the Physical World, Sensor Chips Are Playing A “Leading Role” in Intelligence
In 2026, the autonomous driving sensor chip industr...
Passenger Car Corner Module and Wheel‑Side Control System Research Report, 2026
Wheel-side control research: the “last mile” chassis innovation
Wheel-side control dismantles the traditional drive, braking, steering, and suspension control of the chassis from a "centralized" styl...
Embodied Artificial Intelligence (& Humanoid Robot) MCU Research Report, 2026
Research on Humanoid Robot MCUs: Evolution from General-Purpose Control to High-Value Dedicated Chip Solutions Integrated with Edge AI Functions
MCU (Microcontroller Unit) refers to a compact integra...
Intelligent Vehicle Zone Control Unit (ZCU) Research Report, 2026
ZCU Research: Cross-domain integrated ZCUs are becoming the edge computing nodes of the next-generation zonal architecture
Currently, the mainstream zonal architecture is mainly the quasi-central + z...
Automotive Cybersecurity and Data Security Research Report, 2026
Cybersecurity & Data Security Research: Intelligent Connected Vehicles Enter the Era of “Systematic Offense-Defense and AI-Defined Security”.
Centering on the panorama of intelligent connect...
Report on Breakthrough Strategies of OEMs and ADAS Tier 1 Suppliers for Overseas Layout of Intelligent Driving, 2026
Regulatory Breakthrough, Local System Establishment, OEMs Competing for NOA Layout: Overall Trends of China’s Intelligent Driving Overseas Layout in 2026
Research on overseas intelligent driving layo...
OEMs and Tier1s’ Intelligent Cockpit Platform (Hardware and Software) Innovation Strategy Research Report, 2026
Intelligent Cockpit Platform Research: multi-dimensional cockpit system architecture reconstruction for multi-agent collaboration and proactive intelligent services
The intelligent cockpit software s...
Automotive AIOS Research Report, 2026
Automotive AIOS Research: Mass Production Solutions Are Implemented
Mass Production Solutions Are Implemented on A Small Scale.
In 2026, AIOS starts small-scale implementation, helping to improve v...
Automotive Telematics Service Provider (TSP) Research Report, 2026
TSP Research: Leading providers collectively turn to AI agents to provide all-scenario active services
Telematics Service Providers (TSPs) are the core hub of the telematics industry chain, connectin...