Research on Automotive LiDAR Industry: How five technology roadmaps develop amid the upcoming mass production of high-channel LiDAR?
During 2020-2025, autonomous driving above L3 will be commercialized, for which LiDAR will become an important option. LiDAR vendors break through technical bottlenecks and work closely with OEMs to massively install high-channel LiDAR as soon as possible. Today, Audi has teamed up with Valeo/Luminar, BMW has cooperated with Innoviz, Volvo has collaborated with Luminar, Great Wall Motors has partnered with Ibeo, and Hyundai has joined forces with Velodyne. Even Mobileye, a proponent of visual ADAS, is developing its own LiDAR technology.
In early 2020, Bosch announced that it is making long-range LiDAR sensors production-ready-the first LiDAR (light detection and ranging) system that is suitable for automotive use. Continental delivers a 50-meter range 3D flash LiDAR sensor that's expected to find increasing application in commercial vehicles and off-highway machines in 2020. Valeo’s 16-channel SCALA 2, which can detect objects up to a distance of 150 meters, has won orders from some production vehicle models, and its SOP is expected in 2021. This shows that high-channel LiDAR is on the eve of mass production.
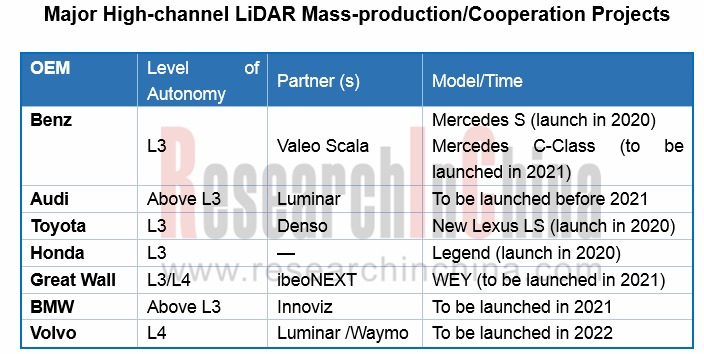
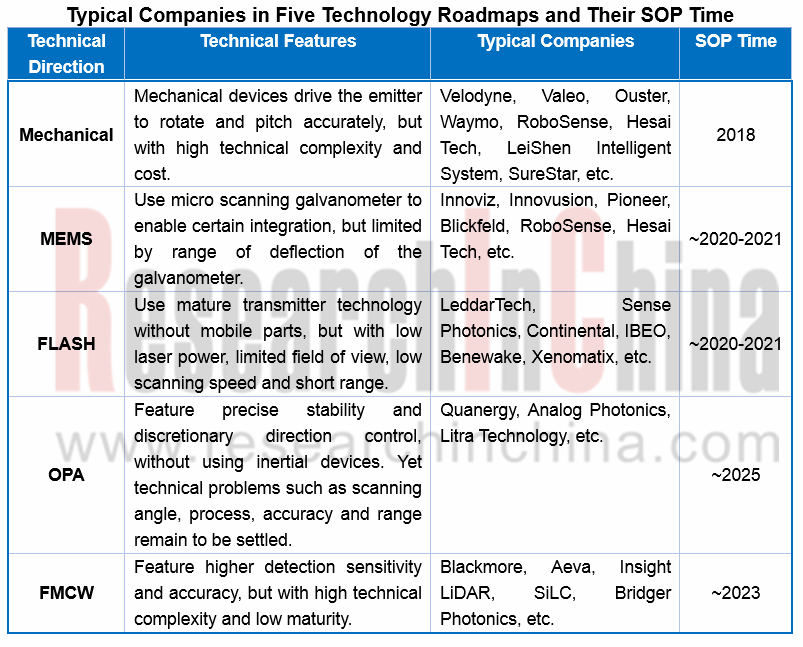
Still, the battle for technology roadmaps in the LiDAR field continues. There are now automotive LiDAR technology roadmaps encompassing mechanical, MEMS, FLASH, OPA and FMCW, among which FMCW is a coherent detection technology while the rest are pulsed ToF detection technologies.
Mechanical LiDAR
Mechanical LiDAR is the earliest developed and most mature product. Waymo's Honeycomb LiDAR is also based on mechanical technology. Although it has been criticized a lot, mechanical LiDAR is still the mainstream on the market. Representative companies of mechanical LiDAR include Velodyne, Valeo, Ouster, Waymo, RoboSense, Hesai Tech, SureStar, LeiShen Intelligent System, etc.
Most mechanical LiDAR vendors are pushing forward two strategies concurrently. On the one hand, they improve the mechanical LiDAR product line, try to reduce costs and enhance performance; on the other hand, they actively expand the solid-state LiDAR product portfolios (MEMS, FLASH, OPA, etc.).
For example, Velodyne has rolled out the all-solid-state Velarray LiDAR, and short-range VelaDome LiDAR perfect for automotive applications such as blind spot monitoring. Velodyne has acquired Mapper.ai, a HD map startup with a team of 25 talents, for quicker development of Vella software. In January 2020, Velodyne unveiled the cheap Velabit LiDAR priced only at $100.
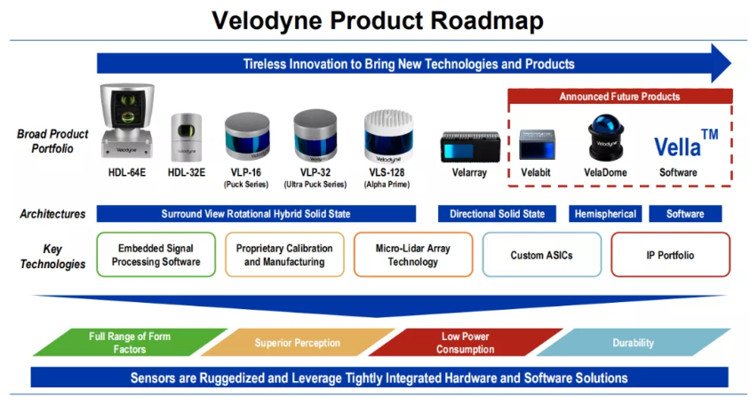
Velodyne branches out to ADAS and other fields aggressively. Nowadays, the autonomous driving business only contributes a quarter of Velodyne's revenue, whereas the remaining earnings come from ADAS, robotics, surveying and mapping, smart cities, shuttles, and unmanned distribution, among which unmanned delivery, Robotaxi and ADAS will become main revenue contributors for Velodyne in the next four years. It is estimated that Velodyne will ship 8 million units by 2025.

MEMS LiDAR
Typical suppliers of MEMS LiDAR include Innoviz, Innovusion, Pioneer, Blickfeld, RoboSense, Hesai Tech, etc.. Using micro galvanometers, MEMS LiDAR is limited in size, vibration reliability and operating temperature range.
As concerns MEMS mirrors, foreign companies are at the forefront, such as Innoluce acquired by Infineon based in Germany, Mirrorcle and MicroVision in the United States, Hamamatsu in Japan, and STMicroelectronics in Switzerland. Their Chinese counterparts include Xi'an ZhiSensor, Taiwan Opus, Silicon Vision Microsystem, among others. A few LiDAR companies supply MEMS mirrors through alliances or independent development. For instance, RoboSense has invested in Silicon Vision Microsystem to deploy MEMS LiDAR; Hesai Tech PandarGT 3.0 uses self-developed MEMS mirrors.
MEMS LiDAR will be spawned by most vendors as early as 2020-2021.
Innoviz, which adopts the MEMS technology roadmap as a typical provider, has received more than USD210 million in financing within only four years since its inception. Innoviz is to date competent for mass production and has fetched orders from OEMs. BMW has selected Innoviz for series production of its autonomous vehicles, starting in 2021. Besides, Innoviz has allied with Tier1 suppliers Harman, HiRain Technologies and Aptiv. The latest Innoviz One has a detection range of 0.1-250 meters and will be produced on a large scale in 2021.
Zvision, a Chinese MEMS LiDAR company, secured RMB70 million in Series A+ round of financing in April 2020.
Flash LiDAR
Typical Flash LiDAR vendors are LeddarTech, Sense Photonics, Continental, IBEO, Benewake, Xenomatix and Ouster.
Sense Photonics as the first one to overcome technical challenges has introduced Osprey, its first modular FLASH LiDAR which was sold on the market in January 2020 at a price of $3,200. Continental’s Flash LiDAR, HFL110 featuring 1,064nm laser and hybrid InGaas/CMOS focal plane array, is expected to be spawned in 2020. IBEO’s NEXT LiDAR is about to be mounted on Great Wall VV7 in 2021.
Another company LeddarTech stands out for building Leddar Ecosystem. In July 2020, LeddarTech acquired VayaVision, a sensor fusion and perception software company. Their cooperative solution enables the fusion of camera, radar, and LiDAR for faster time-to-market, and allows for fusion of up to 15 different sensors for Level 2 to Level 4 autonomous driving applications. Two well-known sensor vendors First Sensor and Sunny Optical Technology also join LeddarTech Leddar Ecosystem.
OPA LiDAR
For OPA LiDAR, Quanergy previously released S3 but has yet to commercialize it. Some players like Analog Photonics and Shenzhen Litra Technology are in the phase of development and exploration. It will expectedly take them over 5 years to launch the technology.
OPA LiDAR enables precise stability and discretionary direction control, without using inertial devices. Yet technical problems such as scanning angle, process, accuracy and range remain to be settled. Current integrated OPA technology fails to offer large aperture needed by mid- and long-range LiDAR, due to complexity, high power consumption or low optical efficiency. In August 2020, researchers at University of Colorado Boulder developed a serpentine optical phased array (SOPA) chip which can enlarge optical aperture for LiDAR.
FMCW LiDAR
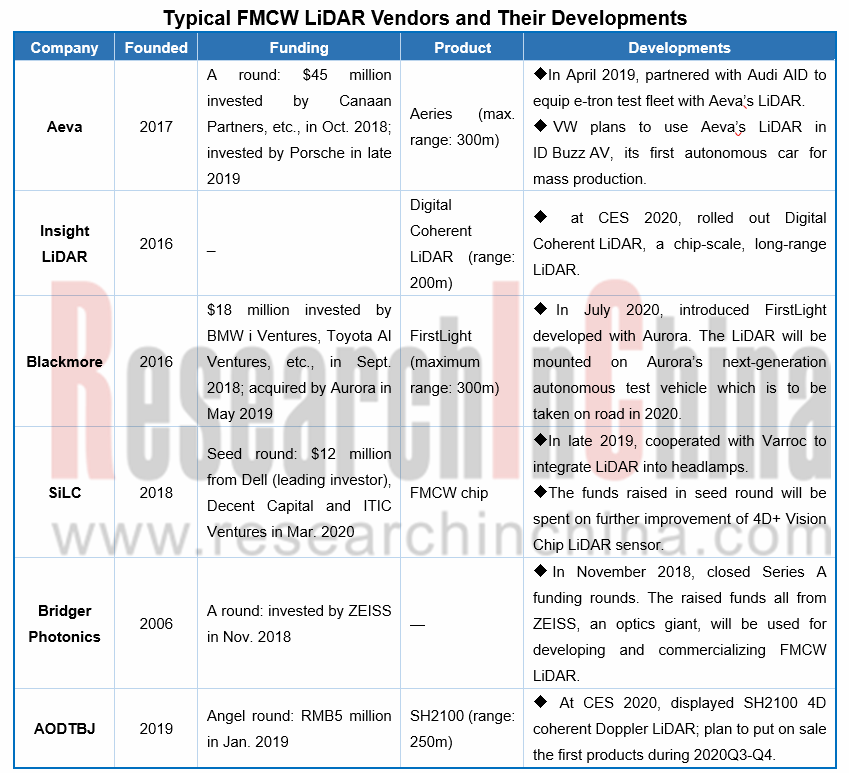
Coherent LiDAR is still in its infancy compared with pulsed ones. The leading technology for the LiDAR is frequency modulated continuous wave (FMCW), into which about 10 players worldwide get involved, including Aeva (invested by Porsche), Blackmore (acquired by Aurora in 2019), Strobe (acquired by Cruise in 2017), SiLC Technologies (invested by Dell), Bridger Photonics (invested by Carl Zeiss) and AODTBJ.
The reason why BMW, Toyota, Porsche, GM and Aurora select FMCW LiDAR lies in FMCW’s edges over pulsed ToF, on ability to directly detect speed (4D information) and high resolution range and permission to use cheap photoelectric detectors (e.g., PIN). The biggest challenge before FMCW technology is the need for being integrated with a plurality of optical components, e.g., laser, amplifier, phase and amplitude controlled low-noise photodiode, mode converter and optical waveguide, all of which should be further integrated into a commercial-scale compact FMCW LiDAR.
From the latest progress, it can be seen that Aeva’s Aeries FMCW system irons out the dependency between maximum detection range and point cloud density, and integrates multiple beams on a chip, achieving full range performance of over 300 meters for objects in addition to the ability to measure instant velocity for every point with a 120-degree field-of-view. The product is projected to be available for use in 2020, costing less than $500 once mass produced.
Furthermore, FirstLight, a LiDAR co-developed by Blackmore and Aurora, allows the Aurora Driver to see well beyond 300 meters even on targets that don't reflect much light, such as a pedestrian wearing dark clothing at night. Aurora has installed its Aurora Driver in six different vehicles, ranging from sedans and Chrysler Pacifica minivans to self-driving trucks. Aurora plans to use its FirstLight LiDAR in its fleet of self-driving development vehicles in 2020.
Actually, OEMs tend to choose more than one technologies. For example, Audi investing Blackmore, a typical FMCW firm, installed Valeo's 4-channel mechanical LiDAR into Audi A8 in 2018 and also has a plan to pack the to-be-produced cars in 2021 with Luminar’s solid state LiDAR.
China Charging Infrastructure (Supercharging, Battery Swapping, V2G, etc.) and High-Performance Supercharging Battery Research Report, 2026
Charging and battery swapping research: as 5C+ supercharging vehicle models go into mass production, the pace of OEMs self-building supercharging networks quickens
800-1000V high-voltage platforms ar...
China Passenger Car Electronic Controlled Suspension Industry Report, 2026
Electronic Controlled Suspension Industry Research: As the First Year of Full Active Suspension Unfolds, Three Technical Routes Race Forward
1. Penetration Rate Surges Three Times, and Electronic Con...
Intelligent Driving SoC Research Report, 2026
Research on Intelligent Driving SoCs: Competition Focus Shifts to L3/L4 Embedded Hardware, and Computing Power of Flagship Vehicle Models Exceeds 1,000 TOPS
In terms of intelligent driving system in...
Automotive AI Large Model Technology Research Report, 2026
Automotive AI Large Model Research: Competition Shifts from "Who Has the Stronger Model" to "Who Boasts Higher Link Efficiency"
ResearchInChina released the Automotive AI Large Model Technology Resea...
Intelligent Vehicle Cockpit Domain Controller Research Report, 2026
Cockpit domain controller research: L3 AIDV intelligent cockpit domain controllers are entering a boom period
Driven by multiple factors such as the continuous evolution of the automotive central int...
Automotive Acoustic System (Audio, Multi-Channel) Industry Report, 2026
Automotive Acoustics Research: Multiple Channels, AI Tuning, and Self-Developed Algorithms Drive the Transformation of High-End Cockpit Sound Fields
I. Automotive Audio Hardware Solutions with 6–9 S...
Autonomous Driving Sensor Chip Research Report, 2026
Research on Autonomous Driving Sensor Chips: Deeply Perceiving the Physical World, Sensor Chips Are Playing A “Leading Role” in Intelligence
In 2026, the autonomous driving sensor chip industr...
Passenger Car Corner Module and Wheel‑Side Control System Research Report, 2026
Wheel-side control research: the “last mile” chassis innovation
Wheel-side control dismantles the traditional drive, braking, steering, and suspension control of the chassis from a "centralized" styl...
Embodied Artificial Intelligence (& Humanoid Robot) MCU Research Report, 2026
Research on Humanoid Robot MCUs: Evolution from General-Purpose Control to High-Value Dedicated Chip Solutions Integrated with Edge AI Functions
MCU (Microcontroller Unit) refers to a compact integra...
Intelligent Vehicle Zone Control Unit (ZCU) Research Report, 2026
ZCU Research: Cross-domain integrated ZCUs are becoming the edge computing nodes of the next-generation zonal architecture
Currently, the mainstream zonal architecture is mainly the quasi-central + z...
Automotive Cybersecurity and Data Security Research Report, 2026
Cybersecurity & Data Security Research: Intelligent Connected Vehicles Enter the Era of “Systematic Offense-Defense and AI-Defined Security”.
Centering on the panorama of intelligent connect...
Report on Breakthrough Strategies of OEMs and ADAS Tier 1 Suppliers for Overseas Layout of Intelligent Driving, 2026
Regulatory Breakthrough, Local System Establishment, OEMs Competing for NOA Layout: Overall Trends of China’s Intelligent Driving Overseas Layout in 2026
Research on overseas intelligent driving layo...
OEMs and Tier1s’ Intelligent Cockpit Platform (Hardware and Software) Innovation Strategy Research Report, 2026
Intelligent Cockpit Platform Research: multi-dimensional cockpit system architecture reconstruction for multi-agent collaboration and proactive intelligent services
The intelligent cockpit software s...
Automotive AIOS Research Report, 2026
Automotive AIOS Research: Mass Production Solutions Are Implemented
Mass Production Solutions Are Implemented on A Small Scale.
In 2026, AIOS starts small-scale implementation, helping to improve v...
Automotive Telematics Service Provider (TSP) Research Report, 2026
TSP Research: Leading providers collectively turn to AI agents to provide all-scenario active services
Telematics Service Providers (TSPs) are the core hub of the telematics industry chain, connectin...
Automotive Smart Interior Research Report, 2026
Smart Interior Research: As Technologies like Interactive Starlight Headliner, Hidden Display and Surface Projection Are Launched, Automotive Interiors Become Ever More Intelligent
The Automotive Sma...
Research Report on AI Applications in Cockpits, 2026
AI Application in Cockpits: AI Services Become More Comprehensive, Convenient, and Refined.
In the first half of 2026, cockpit AI functions underwent initial upgrades across multiple dimensions, inc...
Software-Defined Vehicles in 2026: OEM Software Development and Supply Chain Deployment Strategy Research Report
Research on OEMs’ Software Strategies: R&D Focus, Development Strategies and Supplier Building Models of 30 OEMs
In this paper, we adopt a research framework covering 13 subsystems and 48 sub-di...