As one of the most widely used passive components, MLCC commands approximately 40% of the capacitor market. MLCC finds broad application in fields like communication, consumer electronics, automobile and military, where the robust demand conduces to the expanding MLCC market.
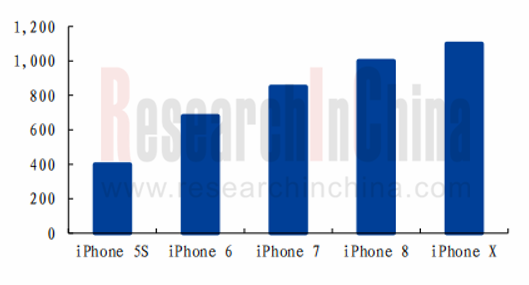
A staggering 64% or so of MLCCs are consumed by consumer electronics, especially smartphones which occupy 39% of total consumption. In iPhone’s case, smartphones with higher configuration use more MLCCs, e.g., an iPhone X needs as many as 1,100 MLCCs compared with an iPhone 5S using 400 pieces. Besides, the portable and intelligent wearables such as TWS headphones and smart watches have drawn much attention from the market over recent years, producing significant demand for MLCCs.
As commercial use of 5G is at a gallop, 5G-enabled smartphones will pack more MLCCs than 4G ones. Examples include a Sub-6Ghz 5G smartphone that uses 10%-15% more MLCCs and an mmWave 5G phone adding 20%-30%. Meanwhile, 5G smartphones’ higher power consumption further drives up demand for high-end, micro/ultra-micro (0201, 01005, etc.) MLCCs with large capacity and low power consumption.
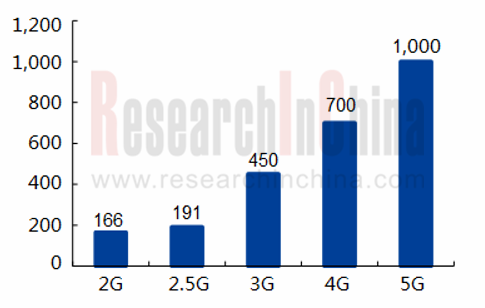
During the faster construction of 5G in 2020, a larger number of 5G base stations to be built and more MLCCs per such a station compared with 4G ones are two factors behind the rising demand for MLCCs. By 2023, global communication base stations’ demand for MLCCs will be 2.1-fold of that in 2019, estimated by Taiyo Yuden. In the meantime, internet of things (IoT) that requires far more stable connectivity will be a beneficiary of low-latency 5G network. A study of VENKEL shows that a terminal needs over 75 MLCCs on average, from which it can be foreseen that more and more connected IOT devices will, beyond doubt, spur the MLCC market to grow.
The development of new energy vehicle and ADAS drives MLCC into a new blue ocean. A common car needs around 3,000 or 4,000 MLCCs while a hybrid/plug-in hybrid vehicle bears around 12,000 pieces and a battery electric vehicle carries virtually 18,000 pieces.
Among vehicle electronic systems, ADAS which applies more MLCCs could collect, detect, recognize and track changed data inside and outside of the vehicle in the shortest time via sensors on the vehicle and helps the driver beware of potential dangers to operate correctly and safely by combining navigation map data to calculate and analyze. Wider coverage of 5G network will be another solution to latency problem. As more and more vehicles carry ADAS that tends to be more intelligent, the demand for MLCCs will multiply.
New energy vehicle with a larger number of control modules like ECU need more passive components to support electronic systems, with a new energy vehicle in want of at least 10,000 MLCCs. With the roll-out of timetables for elimination of ICE vehicles across the world in recent years, new energy vehicles have boasted higher penetration, coupled with more use of MLCCs by a single vehicle, together stimulating the demand for automotive MLCCs.
Of a wide range of automotive MLCC models, those with size ranging from 0402 to 2220 are in use while 0603, 0805 and 1206 get most utilized. Despite unconcern about size of MLCCs, automotive market has a high demanding on them in safety parameters (reliability, service life and failure rate) as well as working temperature, humidity, climate and vibration resistance. Automotive market poses a high entry barrier to MLCC which must be subject to a set of automotive standards (AEC-Q200) and pass quality certification.
It is in the MLCC market that leading players include Murata, Samsung Electro-Mechanics, Yageo, Walsin Technology, Taiyo Yuden, TDK, Kyocera and Chinese Mainland companies like Fenghua Advanced Technology and Chaozhou Three-circle. Since 2016, few MLCC vendors like Murata and TDK have shifted to focus on automotive MLCC, a promising and lucrative high-tech market. This move disrupts the global passive components supply chain and makes low- and mid-end customers turn to companies like Yageo, Fenghua Advanced Technology and Chaozhou Three-circle.
Some vendors have pivoted to the automotive MLCC market.
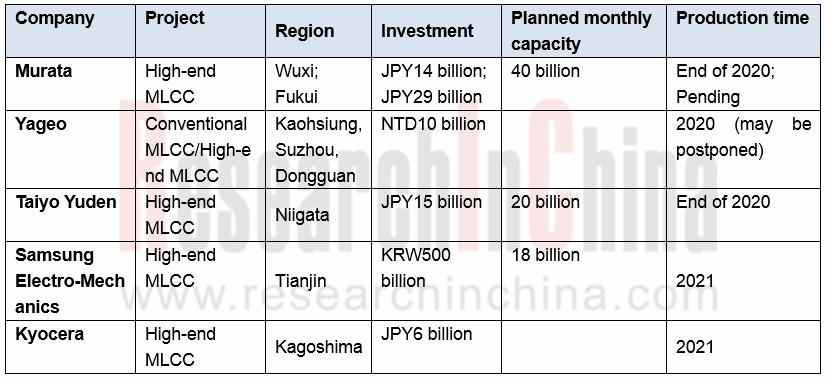
Murata is the MLCC vendor with the highest market share in the world (approximately 56% of the automotive MLCC market), boasting annual capacity up to 1,100 billion MLCCs or so. In recent years, the company has slashed the capacity of low-end MLCCs while ramping up production of automotive and other high-end products. Murata quickens the R&D and mass production of MLCCs for high-end consumer electronics whilst expediting to launch automotive products. In 2019, Murata began to spawn 008004, which will be used in 5G flagship phones of Apple and Huawei. In April 2020, Murata started mass-production of two new multilayer ceramic capacitors for automotive use -- the NFM15HC105D0G3, which is the world's smallest 0402 size (1.0×0.5mm) three-terminal low-ESL multilayer ceramic capacitor, and the NFM18HC106D0G3, which is the three-terminal low-ESL multilayer ceramic capacitor with the world's highest capacitance of 10μF in 0603 size (1.6×0.8mm), suitable for ADAS and autonomous driving.
The second-ranked Samsung Electro-Mechanics by MLCC market share in the world (ranking fourth in the automotive MLCC market with about 6% share) has followed suit over the recent years, like squeezing out low-end capacity and stepping up the deployment of high-end products. In July 2020, the company developed five new types of MLCCs, including three types for power systems and two types for anti-lock braking systems, which will be available to global automakers in future. Besides building a dedicated automotive production line at the Busan plant, Samsung Electro-Mechanics is pressing ahead with construction of a new plant in Tianjin, China.
Given its inferiority in MLCCs for consumer electronics, TDK cancelled orders for 700 million MLCCs covering about 360 models, and committed itself to mid-to-high-end products in 2017 as the first one aggressively exploring the automotive MLCC market, where TDK now seizes about 25% shares.
MLCC vendors in Mainland China have been developing by leaps and bounds in recent years, especially Fenghua Advanced Technology is one of few Chinese MLCC vendors offering a full range of MLCCs covering 01005-2220 and above sizes with advantages in production scale and technical processes; but it still targets consumer electronics. In 2018, the company launched products in line with the AEC-Q200 standard, but still posing no threat to Japanese and Korean peers due to its weak foundation.
Since 2018, traditional automakers worldwide have begun to deploy electric vehicle manufacturing on a large scale, and the governments have introduced timetables for elimination of ICE vehicle. As the number of MLCCs used in an electric vehicle is 6 times that in an ordinary car, MLCCs are bound to be much sought after. Hundreds of carmakers require automotive MLCCs which are only offered by a few automotive MLCC vendors, inevitably leading to the tight supply of automotive MLCCs in the next two years or three, and a big challenge to any automaker who is in readiness for capacity expansion of electric vehicles and even a mission impossible for emerging automakers because leading MLCC suppliers will give priority to key automakers. The MLCCs from tier-II suppliers as a last resort may cause quality issues and enormous maintenance costs.
Global and China Multi-layer Ceramic Capacitor (MLCC) Industry Report, 2020-2026 highlights the following:
 MLCC industry (definition, classification, industry chain, technology trend, etc.);
Global and Chinese MLCC markets (size and forecast, competitive landscape, market segments, etc.);
Automotive MLCC market (size and forecast, competition pattern, etc.);
Leading automotive MLCC vendors in China and beyond (profile, operation, business, new products, etc.);
Upstream MLCC formula vendors (profile, operation, business, new products, etc.)
Vehicle-Road-Cloud Integration and C-V2X Industry Report, 2026
Vehicle-Road-Cloud and C-V2X Research: with the three-tier promotion system of "top-level planning + mandatory pilot + evaluation binding", the industry turning point is approachingThis report focuses...
China OEM Data Capability Analysis Report, 2026
OEM Data Capability Research: 24 OEMs × 9 Capability Domains, Who Takes the Lead?
An L4 autonomous driving R&D and test vehicle can generate approximately 10TB of raw data per single day — data v...
Autonomous Driving Domain Controller and Central Computing Unit (CCU) Industry Report, 2026
Autonomous Driving Domain Controller (ADCU) Research: One-Chip CCU solutions are quickly available in vehicles
In China's passenger car market, autonomous driving systems involved in mass production ...
Automotive EMS and ECU Industry Research Report, 2026
Automotive EMS Research: The boundaries between EMS providers and Tier1 suppliers are becoming blurred, and the supply chain model is evolving from a linear chain to a networked structure
Mainstream ...
Automotive Microcontroller Unit (MCU) and Application Scenario Research Report, 2026
Automotive MCU Research: Increased demand for redundant security drives ASIL D-compliant MCU shipments to exceed 100 million units
In a vehicle EEA, MCUs are widely distributed in various functional ...
China Intelligent Cockpit Patent Analysis Report, 2026
Intelligent Cockpit Patent Research: Cockpit AI, In?vehicle Health, and Infotainment Are Upgrade to Scenario?based and Proactive Functions
From a patent perspective, this report explores the cutting?...
Research Report on Application of VLA Large Model in Automobiles and Robots, 2026
Research on Automotive and Robot VLA: Hybrid Architectures Become Mainstream, VLA Integrates with General World Models, and Reinforcement Learning Serves as Core Engine
Vision?Language?Action (VLA) m...
China Charging Infrastructure (Supercharging, Battery Swapping, V2G, etc.) and High-Performance Supercharging Battery Research Report, 2026
Charging and battery swapping research: as 5C+ supercharging vehicle models go into mass production, the pace of OEMs self-building supercharging networks quickens
800-1000V high-voltage platforms ar...
China Passenger Car Electronic Controlled Suspension Industry Report, 2026
Electronic Controlled Suspension Industry Research: As the First Year of Full Active Suspension Unfolds, Three Technical Routes Race Forward
1. Penetration Rate Surges Three Times, and Electronic Con...
Intelligent Driving SoC Research Report, 2026
Research on Intelligent Driving SoCs: Competition Focus Shifts to L3/L4 Embedded Hardware, and Computing Power of Flagship Vehicle Models Exceeds 1,000 TOPS
In terms of intelligent driving system in...
Automotive AI Large Model Technology Research Report, 2026
Automotive AI Large Model Research: Competition Shifts from "Who Has the Stronger Model" to "Who Boasts Higher Link Efficiency"
ResearchInChina released the Automotive AI Large Model Technology Resea...
Intelligent Vehicle Cockpit Domain Controller Research Report, 2026
Cockpit domain controller research: L3 AIDV intelligent cockpit domain controllers are entering a boom period
Driven by multiple factors such as the continuous evolution of the automotive central int...
Automotive Acoustic System (Audio, Multi-Channel) Industry Report, 2026
Automotive Acoustics Research: Multiple Channels, AI Tuning, and Self-Developed Algorithms Drive the Transformation of High-End Cockpit Sound Fields
I. Automotive Audio Hardware Solutions with 6–9 S...
Autonomous Driving Sensor Chip Research Report, 2026
Research on Autonomous Driving Sensor Chips: Deeply Perceiving the Physical World, Sensor Chips Are Playing A “Leading Role” in Intelligence
In 2026, the autonomous driving sensor chip industr...
Passenger Car Corner Module and Wheel‑Side Control System Research Report, 2026
Wheel-side control research: the “last mile” chassis innovation
Wheel-side control dismantles the traditional drive, braking, steering, and suspension control of the chassis from a "centralized" styl...
Embodied Artificial Intelligence (& Humanoid Robot) MCU Research Report, 2026
Research on Humanoid Robot MCUs: Evolution from General-Purpose Control to High-Value Dedicated Chip Solutions Integrated with Edge AI Functions
MCU (Microcontroller Unit) refers to a compact integra...
Intelligent Vehicle Zone Control Unit (ZCU) Research Report, 2026
ZCU Research: Cross-domain integrated ZCUs are becoming the edge computing nodes of the next-generation zonal architecture
Currently, the mainstream zonal architecture is mainly the quasi-central + z...
Automotive Cybersecurity and Data Security Research Report, 2026
Cybersecurity & Data Security Research: Intelligent Connected Vehicles Enter the Era of “Systematic Offense-Defense and AI-Defined Security”.
Centering on the panorama of intelligent connect...