Cloud service platform (cloud platform for short) can be interpreted as a scalable platform delivering basic services, middleware, data services, and software services to users over the Internet. Cloud platform is divided into: IaaS (Infrastructure as a Service), PaaS (Platform-as-a-Service), and SaaS (Software-as-a-Service). It is also classified into public cloud, private cloud and hybrid cloud types.
The public cloud platforms incorporate AWS, Microsoft Azure, Alibaba Cloud, Tencent Cloud, Huawei Cloud and Baidu Cloud. There are a large number of private cloud platform providers such as open-source Openstack and varying Openstack-based platforms. Non-open source providers include VMware, Zstack, etc.
Vehicle, infrastructure, cloud and network are crucial elements of cooperative vehicle infrastructure system (CVIS) industry chain. This report highlights the “cloud” link, with emphasis on OEM-centric automotive cloud platform services. With supplier’s cloud platforms as a foundation, OEMs build their own cloud platforms such as marketing & after-sale cloud platform, manufacturing & supply chain cloud platform, telematics cloud platform, autonomous driving cloud platform, simulation cloud platform and HD map cloud platform.
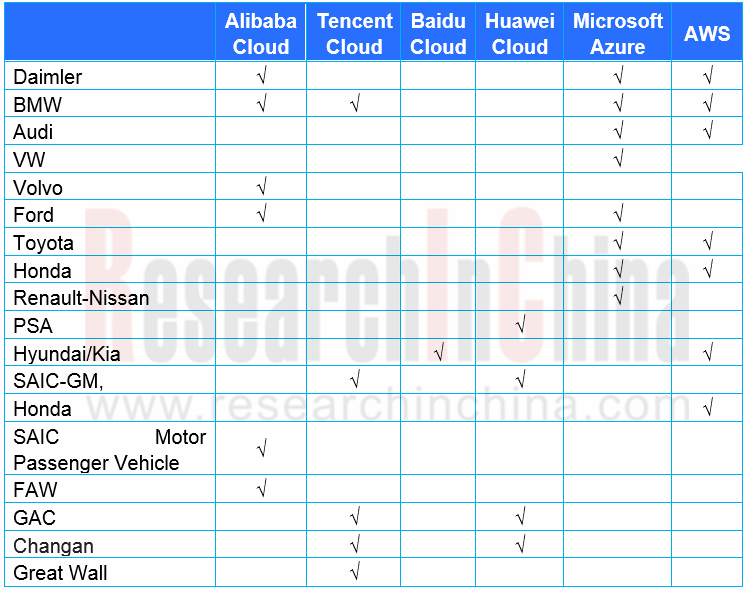
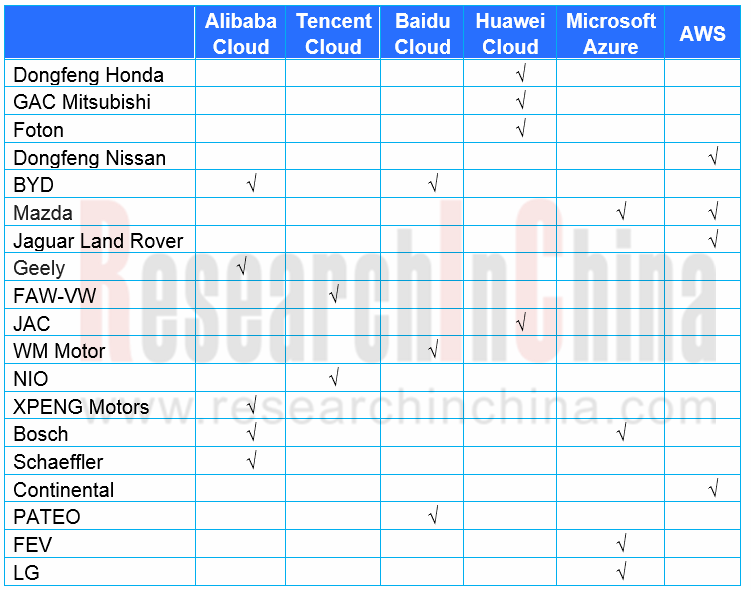
Viewed from the tables above, AWS, Microsoft Azure, Alibaba Cloud, and Tencent Cloud are the first choice of OEMs and Tier1 suppliers. Huawei Cloud and Baidu Cloud are the rising stars. Of both top ten OEMs and top ten Tier1 suppliers that once adopted Amazon Web Services (AWS), more turn to Microsoft Azure as Amazon starts developing and testing autonomous vehicles.
Quite a few OEMs stand on more than one cloud platforms. For instance, Volkswagen Automotive Cloud (vehicles, customers and services) uses Microsoft’s technology, while Volkswagen Industrial Cloud (manufacturing and supply chain management) utilizes Amazon’s.
Telematics cloud platform is among the first automotive cloud platforms already in wide use. In 2017, Microsoft released the Microsoft Connected Vehicle Platform (MCVP), an Azure-based connected automotive platform which has won support from many Tier1 suppliers. The automotive cloud service platform Huawei introduced in 2020 defines more features otherwise: autonomous driving, HD map, battery safety, OTA, V2X and “three powers” (motor, battery and ECU).
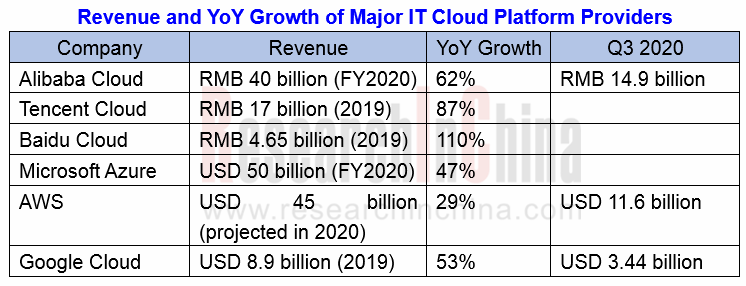
From above it can be clearly seen that IT giants post handsome cloud platform revenues at astounding growth rates, amid the booming demand from automotive sector for cloud services, which is fueled by the following:
(1) Enhancement of automaker’s production management, marketing activities and internal management, and digital revolution and synergy of related industry chains.
(2) Digitalization of the process of automakers’ development, design, test, and validation of software and hardware, and remote R&D teams’ cloud synergy and cloud-based simulation (such as cloud service for firmware simulation).
(3) Digitalization and CASE (Connected, Autonomous, Shared, and Electrified) of automotive products. This means software-defined vehicles, capabilities (e.g., connectivity, navigation, parking, entertainment and payment), and transition from a functional vehicle into an intelligent one cannot be achieved without the support of digitalized process and tools, and cloud services.
(4) Building of the telematics platform for automakers, and the connection, service and operation platform among the four -- car users, automotive products, Internet digital ecosystems, and automakers and their industry chains, providing real-time online mobile interconnected third-space services such as navigation, entertainment and payment, for better user driving experience.
(5) As ADAS/AD gains popularity and gets updated, AVs will generate 4TB data per day, which prompts a surging demand for cloud platform space.
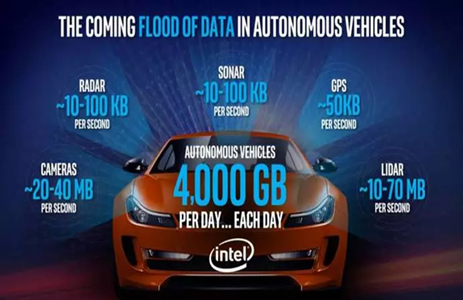
So BAT and Huawei lavish on automotive cloud platform involving operating system, simulation system, telematics system, autonomous driving software, and creation of software and application service ecosystem, considering it is the biggest source of their revenues after all.
OEMs always want to take hold of vehicle data. Currently, leading cloud platform solutions have reserved data ownership of OEMs. For instance, AWS platform retains full ownership of data, while providing functions like machine learning, and special solutions for connectivity and AVs to help OEMs freely create unique brand experience.
Quite a few OEMs set up their own cloud platform subsidiaries and big data centers. Take SAIC Cloud Computing Center as an example. The facility had a 6 or 7-person team, one data center and 5 or 6 cabinets at start and provided just basic cloud storage and IaaS environment. After evolution into Shanghai FinShine Technology Co., Ltd. in 2017, it now boasts a team with 150 talents, three data centers (Shanghai, Nanjing and Zhengzhou) and hundreds of cabinets, and adds software and platform services such as SaaS and PaaS. Up to now the company has owned more than 4,000 cloud hosts, over 10,000 virtual machines or containers, and 30PB storage space.
Companies like SAIC investing heavily in cloud platform still need help from IT tycoons. For example, in 2018, Alibaba Cloud and SAIC together released a hybrid cloud computing service platform for automotive R&D simulation: SSCC (SAIC Simulation Computing Cloud).
To reduce unit costs, IT giants not only build large-scale cloud platforms, but also enable AI algorithms and sundry tool chains and independently develop AI chips. Baidu Cloud, for example, has been a leader in autonomous driving cloud platform field by resorting to competitive DuerOS, Carlife, simulation platform, HD map, autonomous driving algorithms and Kunlun AI chip. OEM’s cloud platform business cannot live without the help of IT firms.
Automotive Microcontroller Unit (MCU) and Application Scenario Research Report, 2026
Automotive MCU Research: Increased demand for redundant security drives ASIL D-compliant MCU shipments to exceed 100 million units
In a vehicle EEA, MCUs are widely distributed in various functional ...
China Intelligent Cockpit Patent Analysis Report, 2026
Intelligent Cockpit Patent Research: Cockpit AI, In?vehicle Health, and Infotainment Are Upgrade to Scenario?based and Proactive Functions
From a patent perspective, this report explores the cutting?...
Research Report on Application of VLA Large Model in Automobiles and Robots, 2026
Research on Automotive and Robot VLA: Hybrid Architectures Become Mainstream, VLA Integrates with General World Models, and Reinforcement Learning Serves as Core Engine
Vision?Language?Action (VLA) m...
China Charging Infrastructure (Supercharging, Battery Swapping, V2G, etc.) and High-Performance Supercharging Battery Research Report, 2026
Charging and battery swapping research: as 5C+ supercharging vehicle models go into mass production, the pace of OEMs self-building supercharging networks quickens
800-1000V high-voltage platforms ar...
China Passenger Car Electronic Controlled Suspension Industry Report, 2026
Electronic Controlled Suspension Industry Research: As the First Year of Full Active Suspension Unfolds, Three Technical Routes Race Forward
1. Penetration Rate Surges Three Times, and Electronic Con...
Intelligent Driving SoC Research Report, 2026
Research on Intelligent Driving SoCs: Competition Focus Shifts to L3/L4 Embedded Hardware, and Computing Power of Flagship Vehicle Models Exceeds 1,000 TOPS
In terms of intelligent driving system in...
Automotive AI Large Model Technology Research Report, 2026
Automotive AI Large Model Research: Competition Shifts from "Who Has the Stronger Model" to "Who Boasts Higher Link Efficiency"
ResearchInChina released the Automotive AI Large Model Technology Resea...
Intelligent Vehicle Cockpit Domain Controller Research Report, 2026
Cockpit domain controller research: L3 AIDV intelligent cockpit domain controllers are entering a boom period
Driven by multiple factors such as the continuous evolution of the automotive central int...
Automotive Acoustic System (Audio, Multi-Channel) Industry Report, 2026
Automotive Acoustics Research: Multiple Channels, AI Tuning, and Self-Developed Algorithms Drive the Transformation of High-End Cockpit Sound Fields
I. Automotive Audio Hardware Solutions with 6–9 S...
Autonomous Driving Sensor Chip Research Report, 2026
Research on Autonomous Driving Sensor Chips: Deeply Perceiving the Physical World, Sensor Chips Are Playing A “Leading Role” in Intelligence
In 2026, the autonomous driving sensor chip industr...
Passenger Car Corner Module and Wheel‑Side Control System Research Report, 2026
Wheel-side control research: the “last mile” chassis innovation
Wheel-side control dismantles the traditional drive, braking, steering, and suspension control of the chassis from a "centralized" styl...
Embodied Artificial Intelligence (& Humanoid Robot) MCU Research Report, 2026
Research on Humanoid Robot MCUs: Evolution from General-Purpose Control to High-Value Dedicated Chip Solutions Integrated with Edge AI Functions
MCU (Microcontroller Unit) refers to a compact integra...
Intelligent Vehicle Zone Control Unit (ZCU) Research Report, 2026
ZCU Research: Cross-domain integrated ZCUs are becoming the edge computing nodes of the next-generation zonal architecture
Currently, the mainstream zonal architecture is mainly the quasi-central + z...
Automotive Cybersecurity and Data Security Research Report, 2026
Cybersecurity & Data Security Research: Intelligent Connected Vehicles Enter the Era of “Systematic Offense-Defense and AI-Defined Security”.
Centering on the panorama of intelligent connect...
Report on Breakthrough Strategies of OEMs and ADAS Tier 1 Suppliers for Overseas Layout of Intelligent Driving, 2026
Regulatory Breakthrough, Local System Establishment, OEMs Competing for NOA Layout: Overall Trends of China’s Intelligent Driving Overseas Layout in 2026
Research on overseas intelligent driving layo...
OEMs and Tier1s’ Intelligent Cockpit Platform (Hardware and Software) Innovation Strategy Research Report, 2026
Intelligent Cockpit Platform Research: multi-dimensional cockpit system architecture reconstruction for multi-agent collaboration and proactive intelligent services
The intelligent cockpit software s...
Automotive AIOS Research Report, 2026
Automotive AIOS Research: Mass Production Solutions Are Implemented
Mass Production Solutions Are Implemented on A Small Scale.
In 2026, AIOS starts small-scale implementation, helping to improve v...
Automotive Telematics Service Provider (TSP) Research Report, 2026
TSP Research: Leading providers collectively turn to AI agents to provide all-scenario active services
Telematics Service Providers (TSPs) are the core hub of the telematics industry chain, connectin...