Global and China Automotive Intelligent Cockpit Platform Research Report, 2021
Next-Generation Intelligent Cockpit Platform: Deep Domain Integration, Pluggable Hardware, Reusable Software
As new-generation E/E architectures evolve, deep integration of cockpit domain may become a trend.
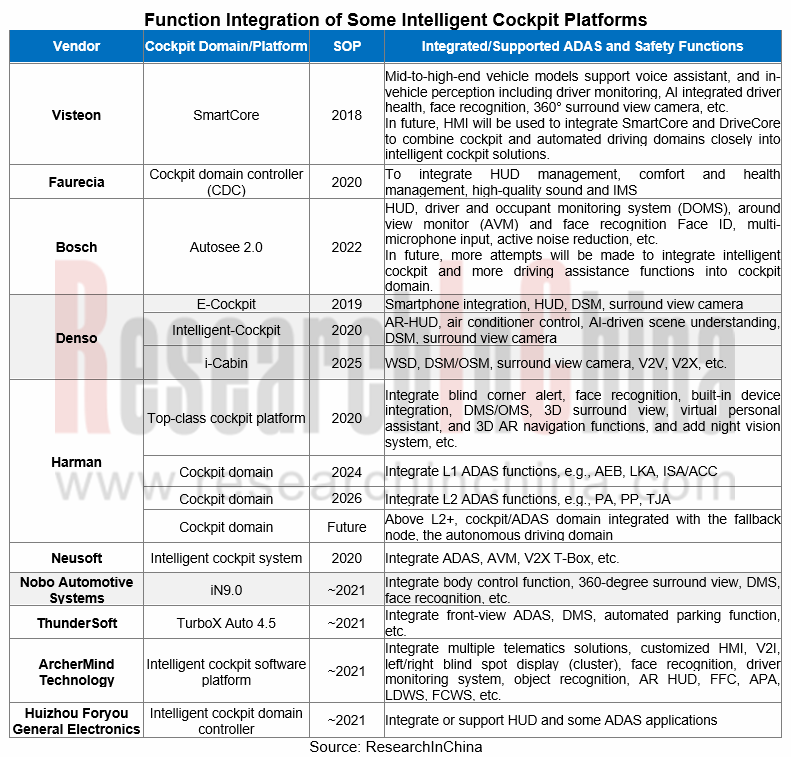
The development of automotive E/E architectures comes with the integration of ADAS functions and V2X systems into the cockpit domain that already combines conventional cockpit electronics.
Through the lens of function integration, the cockpit domain tends to be integrated. As well as basic capabilities including dashboard and center console, rear seat entertainment, HUD and voice, quite a few suppliers currently integrate also surround view camera, DMS, IMS and some ADAS functions into their intelligent cockpit platforms.
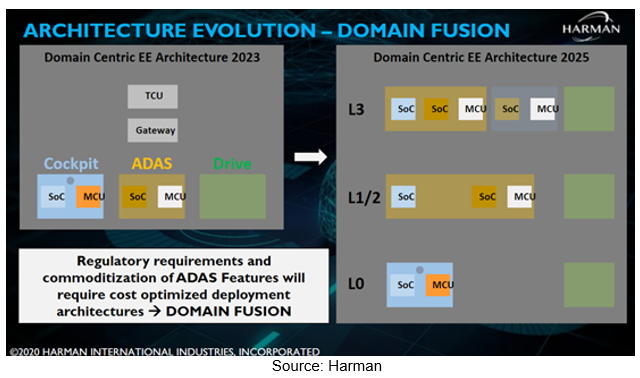
In Harman’s case, its cockpit platform already integrates L0 ADAS functions from AR navigation and 360° surround view to DMS/OMS and E-mirror. In future, Harman will combine intelligent cockpit domain controller and ADAS domain controller to support L1~L2+/L3 capabilities, giving OEMs scope for lowering their costs and simplifying systems.
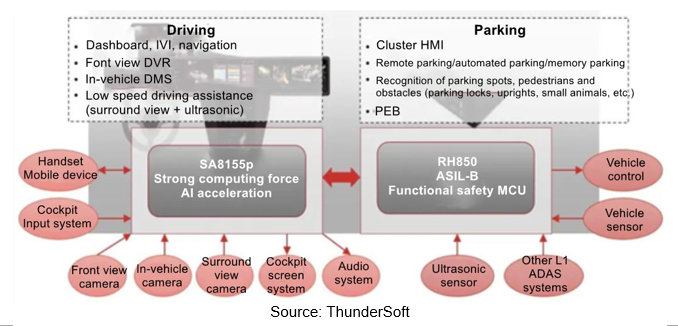
In 2021, ThunderSoft also introduced TurboX Auto 4.5, its new-generation intelligent cockpit platform that allows the cockpit to integrate DMS and automated parking solution and interact with ADAS scenarios. Its intelligent cockpit that can start the built-in computing platform in the parking process optimizes low speed driving with stronger computing force or assists the driver in parking, providing better driving experience.
Cockpit SoC trends: stronger CPU and AI computing force, more displays and sensor interfaces, modular and renewable
With a tendency towards intelligent cockpit multi-sensor fusion, multi-mode interaction and multi-scene mode, cockpit SoC as the processing center needs breakthrough upgrades. The next-generation cockpit SoC will head in the following directions:
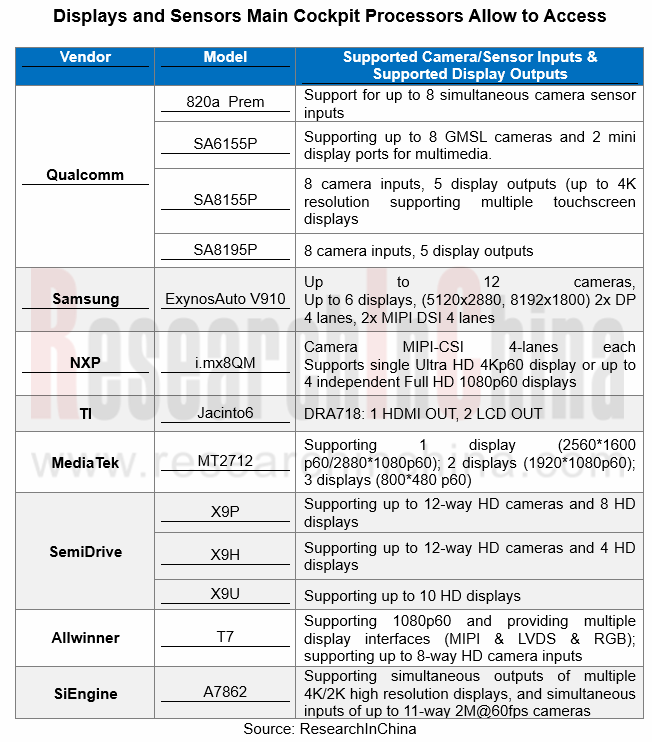
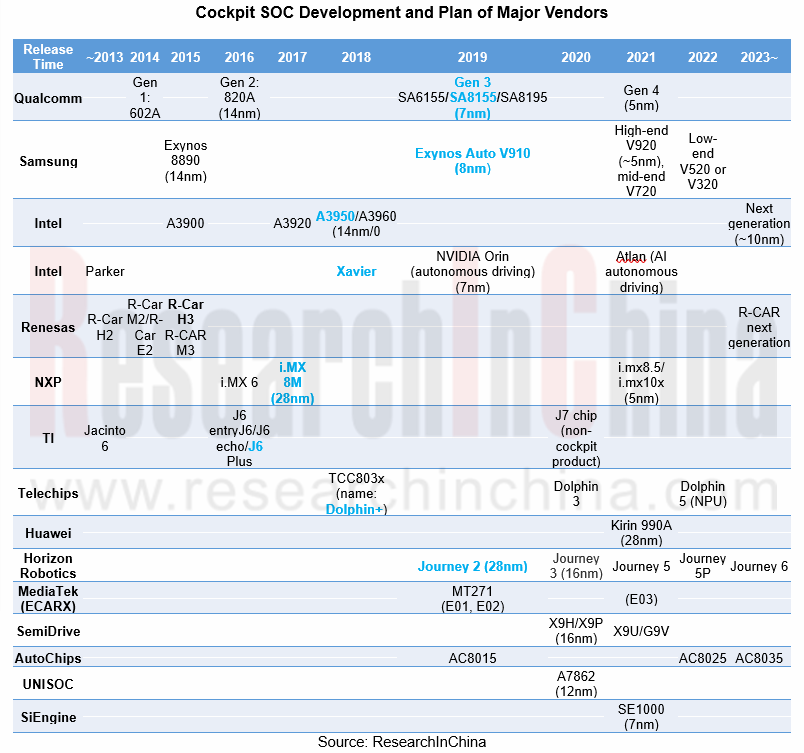
1. Increasingly strong CPU computing force: for example, Qualcomm Snapdragon SA8155P chip and SA8195P CPU boast computing force of 85KDMIPS and 150KDMIPS, respectively; SemiDrive’s latest X9U cockpit chip features CPU computing force of up to 100KDMIPS.
2. Needs for ever stronger AI computing force that allows the driver to interact with voice, graphics and even vehicle functions. In current stage, some mass-produced cockpit SoCs are embedded into AI accelerated computing platforms, affording computing force of 1~5TOPS. Examples include Nvidia Parker for Mercedes-Benz's first-generation MBUX, with AI computing force of 1TOPS, and Samsung’s mass-produced Exynos Auto V910 with AI computing force of approximately 1.9TOPS and its Exynos Auto V920 cockpit chip to be spawned around 2025 with NPU computing force of 30TOPs.
3. Access to more vehicle displays and sensors. For example, Qualcomm 8155/8195 supports up to 8 sensor outputs and 5-way displays; Samsung V910 supports 6-way displays; X9U, SemiDrive’s latest intelligent cockpit chip unveiled at Auto Shanghai 2021 supports 10 HD displays.
4. More advanced chip process. At present, 7nm and 8nm cockpit chips such as Qualcomm 8155/8195 and Samsung V910 have been mass-produced. Qualcomm’s new fourth-generation Snapdragon automotive cockpit chip adopts 5nm process and is projected to be produced in quantities in 2022.
5. Faster chip iteration, shorter release cycle. New cockpit chips are released every 1 or 2 years compared with previous 3 or 5 years, showing faster iteration.
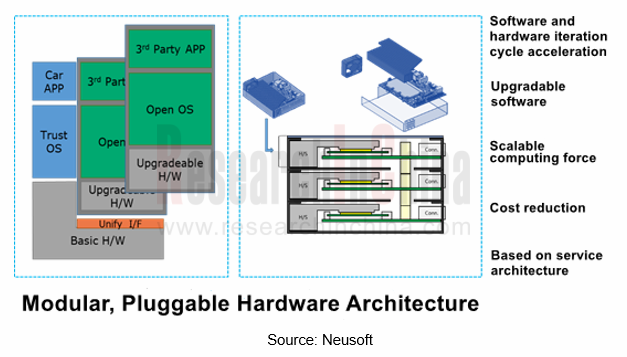
6. Cockpit SoC also tends to be modular, replaceable and scalable. In April 2021, Huawei released 9610, an IVI module with built-in Kirin 990A automotive chip. The chip module featuring pluggable design can be upgraded by way of replacing central processing unit every three years, and each generation with the same interfaces allows direct replacement, covering the full life cycle of vehicles.
Neusoft Vehicle Computing Platform (VCP) also allows flexible, free configurations with hardware plug and unplug. The separation of the computing unit from the functional unit successfully decouples the software and hardware development process, making it a reality features and advantages like upgradable hardware, sharable computing force and scalable software, to build more flexible business models for automakers.
Cockpit software platform: a standard, scalable, open integrated basic software platform
Quite a few technology firms including Continental EB, ThunderSoft, Neusoft Reach, Huawei, ArcherMind Technology and Banma Information Technology have made deployments in intelligent cockpit software platform.
At present, decoupling and separating the intelligent vehicle cockpit software and hardware has been a common belief. Based on service oriented architecture (SOA), the decoupling and reuse of vehicle software and hardware at the underling layer enable rapid iteration of software functions, and the interaction with users over the air (OTA) helps to deliver personalized and differentiated cockpit product experience.
TurboX Auto 4.5, ThunderSoft’s SOA-based intelligent cockpit platform, enables decoupling of scenarios and services, and rapid development and iteration of scenario services.
Besides needed rapid iteration of cockpit software, reusability, scalability and enough flexibility should also be taken into account in SOA design so that the needs for a mass of inputs can be satisfied with minimal software change.
Neusoft already builds its general standard software architecture and software platform that can fast adapt to different mainstream SoC hardware platforms, and help to realize mass production of high-, mid- and low-end multi-platform intelligent cockpits shortly to meet the needs of different OEMs.
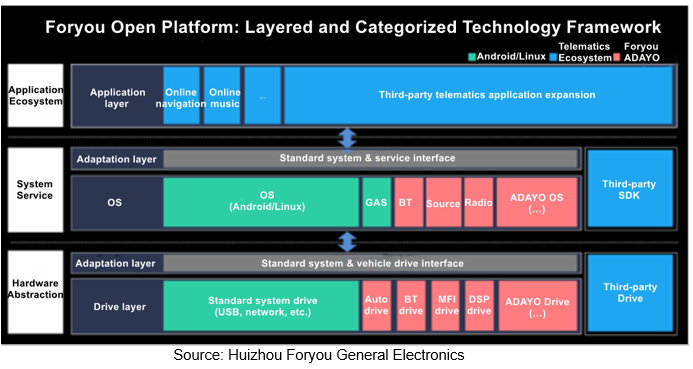
In Jul. 2020, Foryou introduced ADAYO Automotive Open Platform (AAOP) which decouples the telematics software ecosystem at the upper layer and the hardware ecosystem at the underlying layer. AAOP focuses on the intelligent cockpit platform. Based on the standard, modular, layered and categorized software framework of AAOP, Huizhou Foryou General Electronics’ software development model can be transformed from project-based embedded software delivery to layered, categorized software development, which accelerates research and development, reduce R&D preparations and improve R&D efficiency.
Automotive market business models are undergoing disruption. Under the new cooperation model, components suppliers and OEMs partner more closely, and their joint development of cockpit software platforms will become a trend. Tier1s have even been a part of automakers’ engineering design, even partaking in their product design. Platform-based open cooperation on both hardware and software holds a trend. Tier1s are becoming so-called Tier0.5s, while Tier2s work towards Tier1s.
Software-Defined Vehicles in 2026: Software Supply Chain Panorama and Business Models Research
Research on Automotive Software Business Models: Exploration of Token Economy, AI Service Revenue Sharing and Other Businesses
Under the Trend of AI Agents: Exploration of Business Models Based on T...
New Energy Commercial Vehicle 800-1000V High-Voltage Platform & Supply Chain Panorama Research Report, 2026
Research on 800V Architecture of Commercial Vehicles: New Energy Penetration Rate Exceeds 35%, and 800V Full-Domain High-Voltage Architecture Rapidly Penetrates Heavy-Duty Trucks
Explosive Growth in ...
ADAS and Autonomous Driving Tier 1 Suppliers Research Report, 2026 – Chinese Companies
Intelligent Driving Industry Leap: From Widespread L2.9 Adoption toward Physical AI and New Full?Domain Mobility Ecosystem
As vehicle intelligence advances, the installations and penetration rate of...
Vehicle-Road-Cloud Integration and C-V2X Industry Report, 2026
Vehicle-Road-Cloud and C-V2X Research: with the three-tier promotion system of "top-level planning + mandatory pilot + evaluation binding", the industry turning point is approachingThis report focuses...
China OEM Data Capability Analysis Report, 2026
OEM Data Capability Research: 24 OEMs × 9 Capability Domains, Who Takes the Lead?
An L4 autonomous driving R&D and test vehicle can generate approximately 10TB of raw data per single day — data v...
Autonomous Driving Domain Controller and Central Computing Unit (CCU) Industry Report, 2026
Autonomous Driving Domain Controller (ADCU) Research: One-Chip CCU solutions are quickly available in vehicles
In China's passenger car market, autonomous driving systems involved in mass production ...
Automotive EMS and ECU Industry Research Report, 2026
Automotive EMS Research: The boundaries between EMS providers and Tier1 suppliers are becoming blurred, and the supply chain model is evolving from a linear chain to a networked structure
Mainstream ...
Automotive Microcontroller Unit (MCU) and Application Scenario Research Report, 2026
Automotive MCU Research: Increased demand for redundant security drives ASIL D-compliant MCU shipments to exceed 100 million units
In a vehicle EEA, MCUs are widely distributed in various functional ...
China Intelligent Cockpit Patent Analysis Report, 2026
Intelligent Cockpit Patent Research: Cockpit AI, In?vehicle Health, and Infotainment Are Upgrade to Scenario?based and Proactive Functions
From a patent perspective, this report explores the cutting?...
Research Report on Application of VLA Large Model in Automobiles and Robots, 2026
Research on Automotive and Robot VLA: Hybrid Architectures Become Mainstream, VLA Integrates with General World Models, and Reinforcement Learning Serves as Core Engine
Vision?Language?Action (VLA) m...
China Charging Infrastructure (Supercharging, Battery Swapping, V2G, etc.) and High-Performance Supercharging Battery Research Report, 2026
Charging and battery swapping research: as 5C+ supercharging vehicle models go into mass production, the pace of OEMs self-building supercharging networks quickens
800-1000V high-voltage platforms ar...
China Passenger Car Electronic Controlled Suspension Industry Report, 2026
Electronic Controlled Suspension Industry Research: As the First Year of Full Active Suspension Unfolds, Three Technical Routes Race Forward
1. Penetration Rate Surges Three Times, and Electronic Con...
Intelligent Driving SoC Research Report, 2026
Research on Intelligent Driving SoCs: Competition Focus Shifts to L3/L4 Embedded Hardware, and Computing Power of Flagship Vehicle Models Exceeds 1,000 TOPS
In terms of intelligent driving system in...
Automotive AI Large Model Technology Research Report, 2026
Automotive AI Large Model Research: Competition Shifts from "Who Has the Stronger Model" to "Who Boasts Higher Link Efficiency"
ResearchInChina released the Automotive AI Large Model Technology Resea...
Intelligent Vehicle Cockpit Domain Controller Research Report, 2026
Cockpit domain controller research: L3 AIDV intelligent cockpit domain controllers are entering a boom period
Driven by multiple factors such as the continuous evolution of the automotive central int...
Automotive Acoustic System (Audio, Multi-Channel) Industry Report, 2026
Automotive Acoustics Research: Multiple Channels, AI Tuning, and Self-Developed Algorithms Drive the Transformation of High-End Cockpit Sound Fields
I. Automotive Audio Hardware Solutions with 6–9 S...
Autonomous Driving Sensor Chip Research Report, 2026
Research on Autonomous Driving Sensor Chips: Deeply Perceiving the Physical World, Sensor Chips Are Playing A “Leading Role” in Intelligence
In 2026, the autonomous driving sensor chip industr...
Passenger Car Corner Module and Wheel‑Side Control System Research Report, 2026
Wheel-side control research: the “last mile” chassis innovation
Wheel-side control dismantles the traditional drive, braking, steering, and suspension control of the chassis from a "centralized" styl...