Intelligent Vehicle E/E Architecture and Computing Platform Industry Research Report, 2021
E/E Architecture and Computing Platform Industry Research: Three Evolution Stages of Automakers’ E/E Architectures
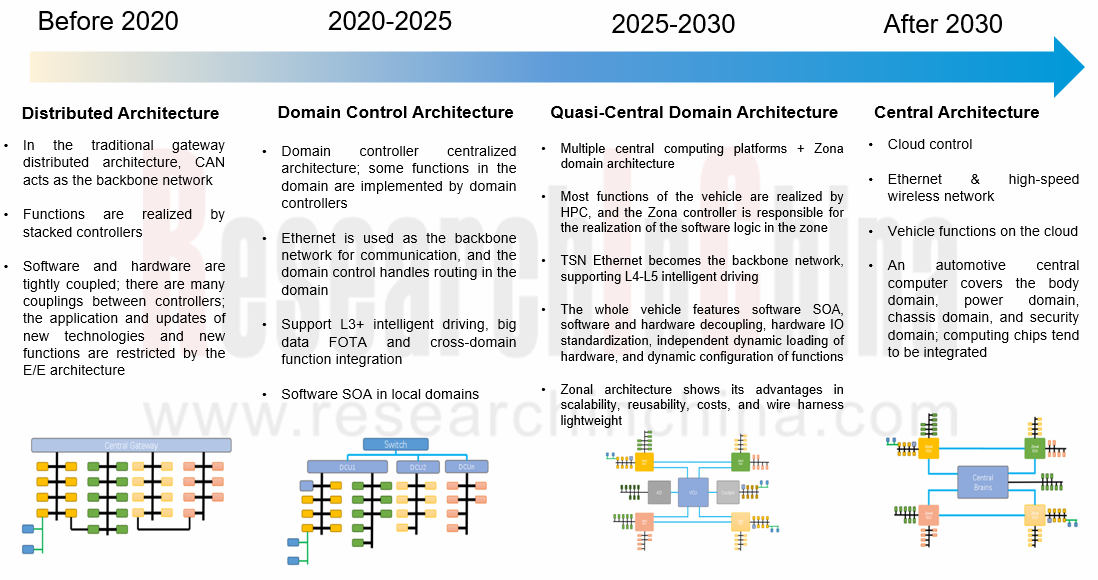
Domain centralized architectures will gradually evolve to quasi-central and central computing architectures
The evolution of the brand-new automotive E/E architecture, which may take ten years, can be divided into three stages:
(1) Domain centralized architecture stage
At present, automakers mainly stay at the domain centralized architecture stage. For example, Volkswagen's E3 architecture, Great Wall’s GEEP3.0 architecture, BYD's E platform 3.0 architecture, Geely's SEA architecture, Xpeng's EE 2.0 architecture, etc. are all typical domain centralized architectures.
Automotive E/E architectures will inevitably develop towards centralized E/E architectures. From the perspective of mass-produced models, centralized E/E architectures prevail now, with domain control over power, chassis, body, intelligent driving and cockpit. However, it is difficult to fully realize standard domain architectures and central architectures due to technical thresholds, diversified configuration gradients, consumption habits and other factors, so the domain hybrid architecture of "distributed ECUs + domain controllers" will be common in the short term.
At present, Volkswagen, BMW, Geely ZEEKR, Huawei, Visteon, etc. adopt three-domain E/E architecture solutions which mainly include intelligent driving domain, intelligent cockpit domain, and vehicle controller domain.
Volkswagen has upgraded the MQB distributed E/E architecture to the MEB (E3) domain centralized E/E architecture which includes 3 domain controllers: vehicle control (ICAS1), intelligent driving (ICAS2), and intelligent cockpit (ICAS3). Modules such as chassis and airbags that do not have integration capabilities belong to ICAS1. At present, ICAS1 and ICAS3 have been developed and installed on ID.3, ID.4 and other models, while ICAS2 has not been developed yet.
In terms of the software architecture, E3 adopts a service-oriented architecture, using CP and AP service middleware to enable SOA communication; as for the communication architecture, E3's backbone network is Ethernet.
On the CC architecture, Huawei has launched three domain control platforms of intelligent cockpit (CDC), vehicle control (VDC), and intelligent driving (MDC) respectively, and released related open platforms and operating systems, such as the autonomous driving operating system AOS, the intelligent cockpit operating system HarmonyOS and the vehicle control operating system VOS.
In terms of communication architecture, the CC architecture has set up 3-5 VIUs (vehicle interface units). All actuators and sensors are connected to distributed gateways so as to form loops. Once a single loop fails to work, the other three loops maintain operation, hereby effectively improving safety.
(2) Quasi-central computing architecture stage
In the next step, automakers will work hard in the quasi-central architecture of “the central computing platform + regional controllers”. Through SOA, it shares the computing power of different domain controllers like a central computing platform. The GEEP 4.0 architecture to be launched by Great Wall in 2022 and the FEEA3.0 architecture (to be mass-produced in 2023) released by FAW Hongqi in 2021 are quasi-central architectures.
Tesla’s EEA architecture is the most advanced, at least 5 years ahead of that of traditional automakers. The E/E architecture of Model 3 has marked Tesla’s entry into the quasi-central architecture stage consisting of central computing module (CCM), Body Control Module Left (BCMLH) and Body Control Module Right (BCMRH), basically materializing the prototype of a centralized architecture with the self-developed Linux, FOTA of the whole vehicle and communication via the Ethernet backbone network.
Tesla's quasi-central E/E architecture has sparked a harness revolution. The wiring harness of Model S/Model X is as long as 3 kilometers, while Model 3 reduces the wiring harness length to 1.5 kilometers, and Model Y further shortens it to around 1 kilometer. Tesla's plans to make the length as short as 100 meters.
(3) Central computing architecture stage
From the perspective of development trends, the automotive E/E architecture will eventually evolve to the central computing architecture, concentrating the functional logic to a central controller. The OEM Great Wall plans to launch the central computing architecture GEEP 5.0 in 2024, and Changan also intends to complete the development of its central domain architecture in 2025.
Evolution of Automotive E/E Architecture
Source: ENOVATE
In the next 3-5 years, OEMs will focus on R&D and layout of quasi-central architectures
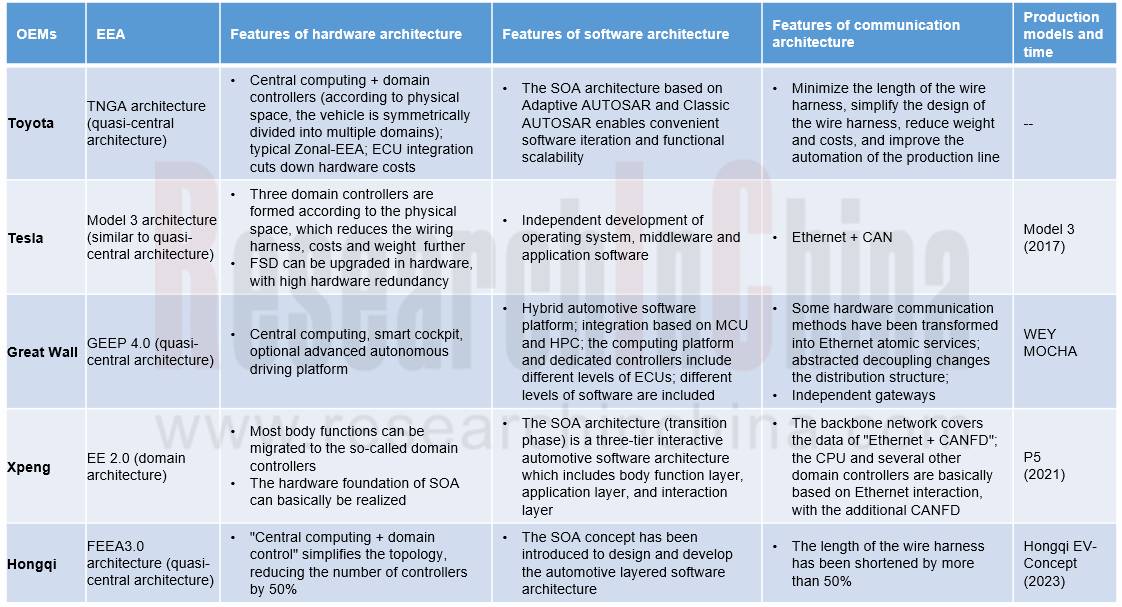
As per the E/E architecture solutions of traditional automakers, most OEMs at home and abroad have transferred from distributed architectures to domain centralized architectures, and they have taken quasi-central architectures as the focus of R&D and layout in the next 3-5 years. Quasi-central and centralized architectures can effectively reduce the number of controllers and wiring harnesses, promote the further decoupling of automotive hardware and software, and drag down the cost further. In order to keep up with the upgrades of automotive technology, OEMs speed up the deployment of quasi-central architectures, introduce SOA architectures and make layout in central computing platforms, etc..
Features of Next-generation E/E Architectures of Some OEMs
Source: ResearchInChina
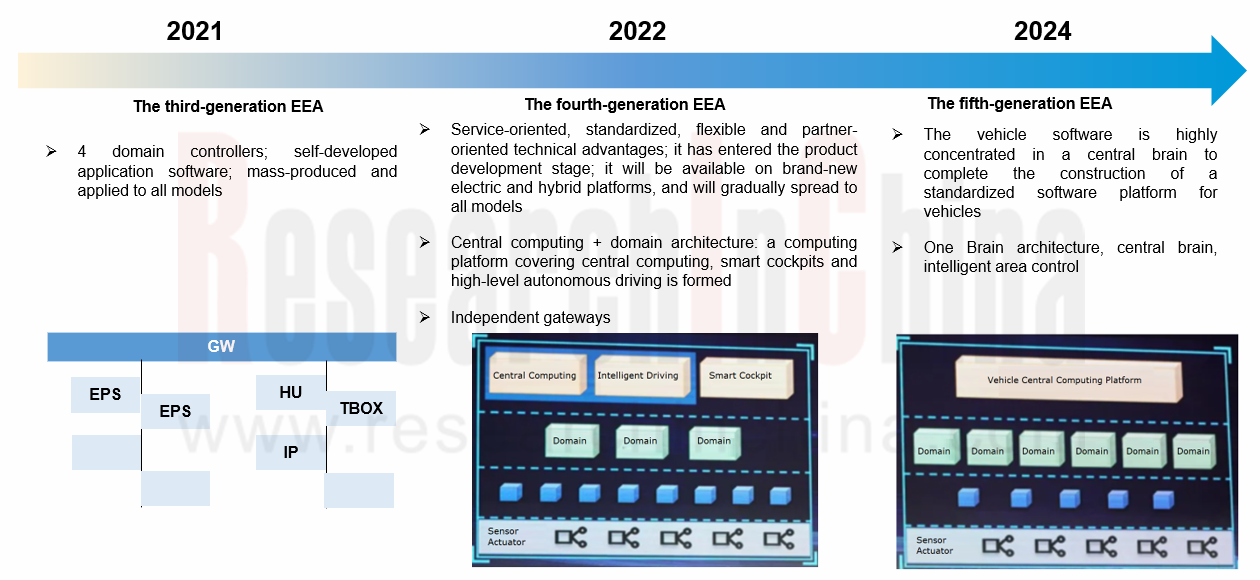
Great Wall has independently developed the GEEP E/E architecture which has evolved to the third-generation GEEP 3.0 so far. As the domain control architecture, it boasts 4 domain controllers. With integrated software and hardware and self-developed application software, it has been successfully applied to all models. At present, Great Wall is actively developing the fourth- and fifth-generation E/E architectures.
As “the central computing platform + regional controllers” architecture, the fourth-generation E/E architecture of Great Wall comprises three large computing platforms for central computing, intelligent cockpit, and optional advanced autonomous driving respectively. The central computing platform integrates body, gateways, air conditioning, EV, power chassis and ADAS, featuring cross-domain integration. It is scheduled to be launched in 2022. The fifth-generation E/E architecture is to highly concentrate the entire automotive software in a central brain to achieve 100% SOA, and it will be available in 2024.
Evolution of Great Wall’s E/E Architecture
Source: ResearchInChina
The FEEA2.0E/E architecture developed by FAW Hongqi independently is a domain control architecture consisting of a new energy vehicle controller, a L3/L4 autopilot controller, and a central gateway controller. It has been mass-produced for E-HS9. FEEA3.0, a next-generation E/E architecture, was released in April 2021 as a quasi-central architecture of “the central computing platform + regional controllers”, reducing the number of controllers and the total length of the wiring harness by more than 50%, as well as adding. It is planned to be deployed on Hongqi EV-Concept in 2023.
Trends under new E/E architectures
As automotive E/E architectures gradually develop toward central architectures, the centralization of computing power, software services, and peripheralization of sensors and actuators tend to be more obvious; the industrial chain structure has been reshaped, and the business model has undergone significant changes.
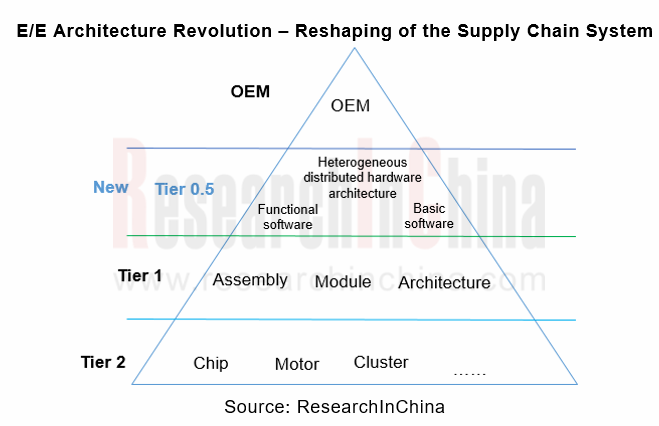
(1) The supply chain system is reshaped
Under the traditional distributed E/E architecture, the hardware and algorithms of controllers are provided by Tier 1 suppliers and OEMs coordinate different suppliers, so that the collaboration is extremely inefficient.
Under the new E/E architecture, OEMs enjoy the dominance. Based on their own software and hardware platforms, they directly convey their demand to suppliers, among which Tier 1 suppliers are no longer dominant while Tier 0.5 suppliers emerge to provide algorithms and software for autonomous driving.
(2) The traditional "turnkey" model transfers to the "full stack" development model
OEMs manipulate the development of software platforms (covering functions integrated, suppliers, etc.) to accomplish deeper development. With the development of autonomous driving technology, OEMs are more inclined to carry out "full-stack" development: they gradually master E/E architectures, operating systems, core algorithms, cloud big data, chips and other capabilities, then provide sustainable and iterative product experience and services with a focus on smart scenarios and consumer experience.
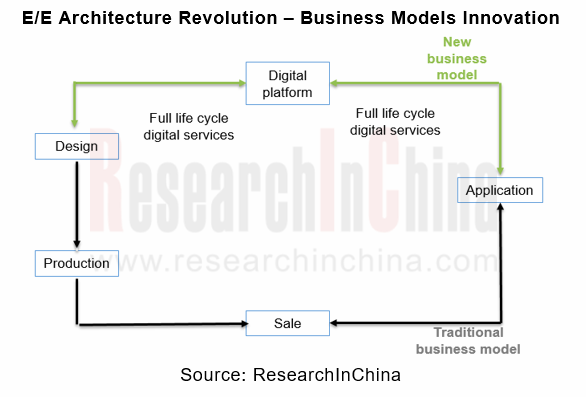
(3) Business models are innovated, and the vehicle OTA sees the completed closed loop of business models
In addition, with the evolution of E/E architectures and the rapid development of vehicle OTA, the sales models of automobiles have altered accordingly. Automakers have turned from one-time product providers to “products + full life cycle services” providers. Around smart scenarios and consumer experience, they provide sustainable and iterative product experience and services. Emerging automakers represented by Tesla update software to iterate and upgrade vehicles.
In addition to vehicle sales, OEMs may charge software updates via OTA in the future. For example, the leader Tesla has earned more than USD1.2 billion from software updates.
Intelligent Vehicle E/E Architecture and Computing Platform Industry Research Report 2021 by ResearchInChina mainly studies the following:
 Overview, technology evolution trends, reform trends, market size, etc. of automotive E/E architectures;
Status quo, evolution trends, etc. of E/E architectures of major OEMs (emerging brands, independent brands, foreign brands);
Status quo, planning, etc. of E/E architectures of major Tier 1 enterprises;
Status quo of main E/E architectures (including computing architecture, software architecture, communication architecture, power management architecture, etc.); Solutions of major manufacturers; evolution of new E/E architectures.
Automotive Microcontroller Unit (MCU) and Application Scenario Research Report, 2026
Automotive MCU Research: Increased demand for redundant security drives ASIL D-compliant MCU shipments to exceed 100 million units
In a vehicle EEA, MCUs are widely distributed in various functional ...
China Intelligent Cockpit Patent Analysis Report, 2026
Intelligent Cockpit Patent Research: Cockpit AI, In?vehicle Health, and Infotainment Are Upgrade to Scenario?based and Proactive Functions
From a patent perspective, this report explores the cutting?...
Research Report on Application of VLA Large Model in Automobiles and Robots, 2026
Research on Automotive and Robot VLA: Hybrid Architectures Become Mainstream, VLA Integrates with General World Models, and Reinforcement Learning Serves as Core Engine
Vision?Language?Action (VLA) m...
China Charging Infrastructure (Supercharging, Battery Swapping, V2G, etc.) and High-Performance Supercharging Battery Research Report, 2026
Charging and battery swapping research: as 5C+ supercharging vehicle models go into mass production, the pace of OEMs self-building supercharging networks quickens
800-1000V high-voltage platforms ar...
China Passenger Car Electronic Controlled Suspension Industry Report, 2026
Electronic Controlled Suspension Industry Research: As the First Year of Full Active Suspension Unfolds, Three Technical Routes Race Forward
1. Penetration Rate Surges Three Times, and Electronic Con...
Intelligent Driving SoC Research Report, 2026
Research on Intelligent Driving SoCs: Competition Focus Shifts to L3/L4 Embedded Hardware, and Computing Power of Flagship Vehicle Models Exceeds 1,000 TOPS
In terms of intelligent driving system in...
Automotive AI Large Model Technology Research Report, 2026
Automotive AI Large Model Research: Competition Shifts from "Who Has the Stronger Model" to "Who Boasts Higher Link Efficiency"
ResearchInChina released the Automotive AI Large Model Technology Resea...
Intelligent Vehicle Cockpit Domain Controller Research Report, 2026
Cockpit domain controller research: L3 AIDV intelligent cockpit domain controllers are entering a boom period
Driven by multiple factors such as the continuous evolution of the automotive central int...
Automotive Acoustic System (Audio, Multi-Channel) Industry Report, 2026
Automotive Acoustics Research: Multiple Channels, AI Tuning, and Self-Developed Algorithms Drive the Transformation of High-End Cockpit Sound Fields
I. Automotive Audio Hardware Solutions with 6–9 S...
Autonomous Driving Sensor Chip Research Report, 2026
Research on Autonomous Driving Sensor Chips: Deeply Perceiving the Physical World, Sensor Chips Are Playing A “Leading Role” in Intelligence
In 2026, the autonomous driving sensor chip industr...
Passenger Car Corner Module and Wheel‑Side Control System Research Report, 2026
Wheel-side control research: the “last mile” chassis innovation
Wheel-side control dismantles the traditional drive, braking, steering, and suspension control of the chassis from a "centralized" styl...
Embodied Artificial Intelligence (& Humanoid Robot) MCU Research Report, 2026
Research on Humanoid Robot MCUs: Evolution from General-Purpose Control to High-Value Dedicated Chip Solutions Integrated with Edge AI Functions
MCU (Microcontroller Unit) refers to a compact integra...
Intelligent Vehicle Zone Control Unit (ZCU) Research Report, 2026
ZCU Research: Cross-domain integrated ZCUs are becoming the edge computing nodes of the next-generation zonal architecture
Currently, the mainstream zonal architecture is mainly the quasi-central + z...
Automotive Cybersecurity and Data Security Research Report, 2026
Cybersecurity & Data Security Research: Intelligent Connected Vehicles Enter the Era of “Systematic Offense-Defense and AI-Defined Security”.
Centering on the panorama of intelligent connect...
Report on Breakthrough Strategies of OEMs and ADAS Tier 1 Suppliers for Overseas Layout of Intelligent Driving, 2026
Regulatory Breakthrough, Local System Establishment, OEMs Competing for NOA Layout: Overall Trends of China’s Intelligent Driving Overseas Layout in 2026
Research on overseas intelligent driving layo...
OEMs and Tier1s’ Intelligent Cockpit Platform (Hardware and Software) Innovation Strategy Research Report, 2026
Intelligent Cockpit Platform Research: multi-dimensional cockpit system architecture reconstruction for multi-agent collaboration and proactive intelligent services
The intelligent cockpit software s...
Automotive AIOS Research Report, 2026
Automotive AIOS Research: Mass Production Solutions Are Implemented
Mass Production Solutions Are Implemented on A Small Scale.
In 2026, AIOS starts small-scale implementation, helping to improve v...
Automotive Telematics Service Provider (TSP) Research Report, 2026
TSP Research: Leading providers collectively turn to AI agents to provide all-scenario active services
Telematics Service Providers (TSPs) are the core hub of the telematics industry chain, connectin...