Global and China Automotive Operating System (OS) Industry Report, 2021
Automotive OS Research: Automotive OS Is Highly Competitive
Automotive OS has always been complicated and dazzling.
A year ago, ResearchInChina classified "Automotive OS" into four types:
1) Basic Auto OS: it refers to base auto OS such as AliOS, QNX, Linux, including all base components like system kernel, underlying driver and virtual machine.
2) Custom-made Auto OS: it is deeply developed and tailored on the basis of basic OS (together with OEMs and Tier 1 suppliers) to eventually bring cockpit system platform or automated driving system platform into a reality. Examples are Baidu in-car OS and VW.OS.
3) ROM Auto OS: Customized development is based on Android (or Linux), instead of changing system kernel. MIUI is the typical system applied in mobile phone. Benz, BMW, NIO, XPeng and CHJ Automotive often prefer to develop ROM auto OS.
4) Super Auto APP (also called phone mapping system) refers to a versatile APP integrating map, music, voice, sociality, etc. to meet car owners’ needs. Examples are Carlife and CarPlay.
However, profound changes have taken place in the Automotive OS field so far. In this report, we classified Automotive OS from another perspective.
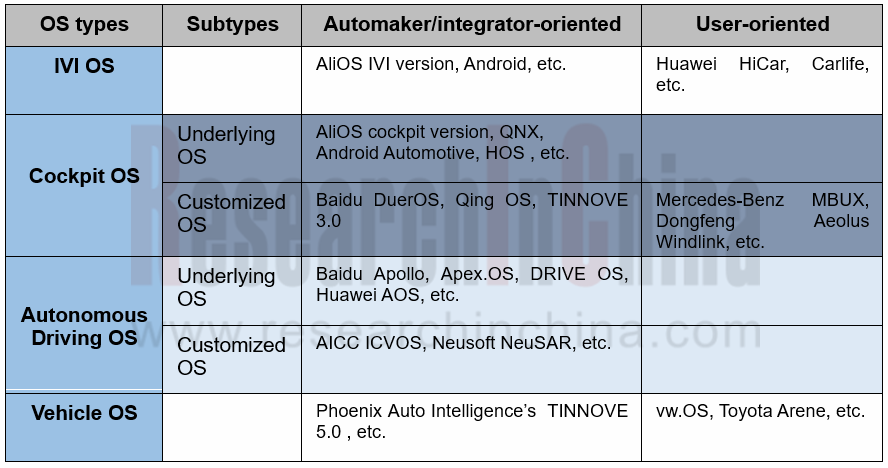
Many Automotive OS vendors have started from IVI OS, with the technological evolution: IVI OS-->Cockpit OS -->Vehicle OS. They are expected to head toward Vehicle OS after 2024.
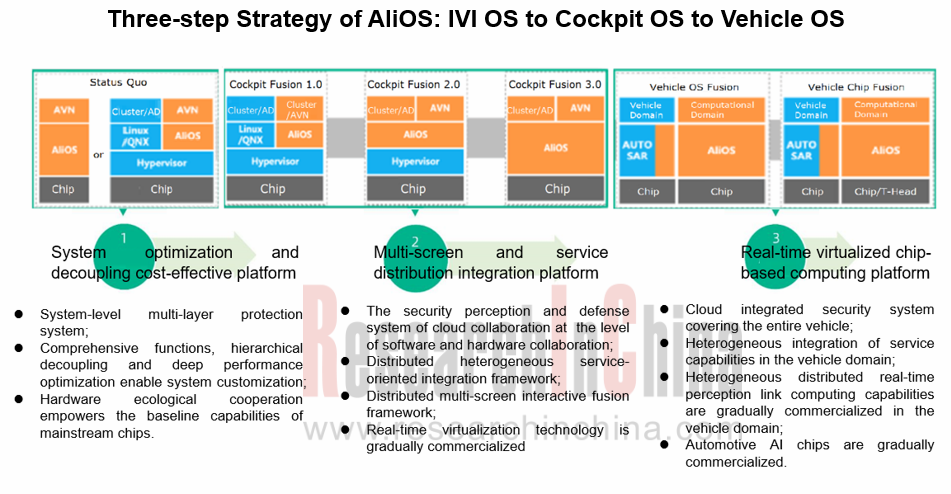
In 2020, Banma SmartDrive proposed the evolution route of AliOS, namely Smart IVI OS-->Smart Cockpit OS -->Smart Vehicle OS.
Based on Tencent's ecology, TINNOVE OS follows the technology roadmap from Cockpit OS to Vehicle OS that integrates the cockpit domain and the autonomous driving domain.
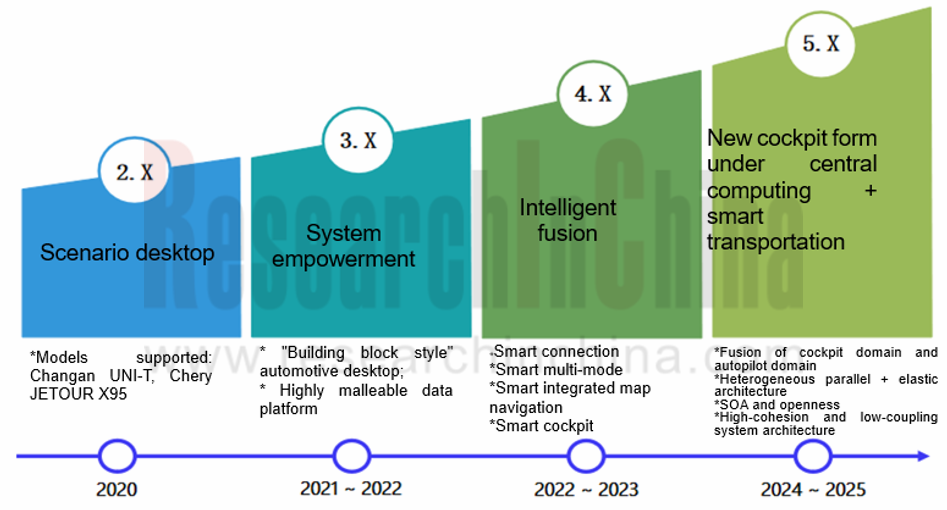
Through the "open" and "ecological" approach, TINNOVE OS transfers Tencent’s ecosystem to the system and OEMs. At present, it has cooperated with Changan Automobile, Audi, Chery JETOUR, Ford and other brands. TINNOVE OS has been installed in more than a dozen models like Changan CS75Plus, UNI-T, CS35Plus and CS85 COUPE. Phoenix Auto Intelligence has recently reached in-depth cooperation with Qualcomm, and SemiDrive, etc.
Autonomous Driving OS and Domain Controllers Are Integrated to Be Autonomous Driving Computing Platform
With the popularity of software-defined vehicles and domain controllers, automakers, Tier1 suppliers and core chip vendors have been all making layout from the perspective of platforms and ecology.
Autonomous driving computing platform providers not only lay out Autonomous Driving OS, but also launch domain controllers, and build ecosystems based on computing platforms consisting of Autonomous Driving OS and domain controllers. With these autonomous driving platforms, OEMs and autonomous driving integrators no longer have to deal directly with the underlying operating system and chips, which can greatly simplify the development process and shorten the product cycle.
Neusoft Reach and AICC are typical autonomous driving computing platform providers.
Neusoft Reach’s next-generation autonomous driving computing platform includes the software platform NeuSAR3.0, the all-in-one X-Cube3.0 for ADAS, and the autonomous driving domain controller X-Box 3.0. In October 2021, Neusoft Reach was invested by SDIC and Virtue Capital with a total of RMB650 million.
In February 2021, AICC released the intelligent driving computing platform "Intelligent Vehicle Basic Brain" (iVBB) 1.0, including intelligent connected vehicle operation system (ICVOS), intelligent vehicle domain hardware (ICVHW), and intelligent connected vehicle-edge-cloud basic software (ICVEC). It features rapid application development, platformization, connectivity, scalability and compliance with automotive regulations.
Automotive OS investment soars, and market competition becomes fierce
In March 2021, Evergrande New Energy Vehicle and Phoenix Auto Intelligence signed an agreement to invest 60% and 40% respectively in establishing an operating system joint venture.
In July 2021, the veteran shareholders Alibaba Group, SAIC Group, SDIC, and Yunfeng Capital jointly injected RMB3 billion into Banma SmartDrive for further R&D and promotion of intelligent vehicle OS.
In June 2021, AICC the completed the angel financing of nearly RMB100 million. In October 2021, AICC raised hundreds of millions of yuan in the pre-A round of financing.
The background of the above three companies: Phoenix Auto Intelligence is backed up by Tencent, Alibaba is behind Banma SmartDrive, and AICC is supported by CICV (invested by more than a dozen traditional OEMs and Tier1 suppliers). Plus Baidu and Huawei, which are aggressive in the Automotive OS market, all players are powerful.
The competition in automotive computing platforms, including operating systems, is essentially ecological competition. Who can win the support of more software developers, component companies, service operators, etc. will dominate the future autonomous driving.
Robot Manufacturers’ Device-Cloud Collaborative Hybrid Computing Deployment Solution Research Report, 2026
EAI Device-Edge-Cloud Collaboration Research: How to Deliver After Layering, Summary of the Ranking for 12 Robot Manufacturers
China’s shipments of humanoid robots are projected to reach 50,000 unit...
China Passenger Car HUD Industry Report, 2026
HUD Research: Installation Rate Exceeds 25% as Entry Price of P-HUD-Equipped Models Falls to RMB130,000
The China Passenger Car HUD Industry Report, 2026 released by ResearchInChina combs through HUD...
Passenger Car Electronic and Electrical Architecture (EEA) and Technology Supply Chain Construction Strategy Research Report, 2026-2027
Passenger Car EEA: The Next-Generation AI EEA Is Gaining Momentum, Enabling Vehicles to Achieve "Autonomous Perception - Autonomous Decision-Making - Autonomous Evolution"
Vehicle Architecture Is Ev...
Next-generation Central and Zonal Communication Network Topology and Chip Industry Research Report, 2026-2027
Research on Zonal Communication Topology: New Architectures Including 10 BASE-T1S+RCP, AVB/TSN Ethernet Are Under Rapid Development
Vehicle communication networks are mainly divided into in-vehicle n...
Software-Defined Vehicles in 2026: Software Supply Chain Panorama and Business Models Research
Research on Automotive Software Business Models: Exploration of Token Economy, AI Service Revenue Sharing and Other Businesses
Under the Trend of AI Agents: Exploration of Business Models Based on T...
New Energy Commercial Vehicle 800-1000V High-Voltage Platform & Supply Chain Panorama Research Report, 2026
Research on 800V Architecture of Commercial Vehicles: New Energy Penetration Rate Exceeds 35%, and 800V Full-Domain High-Voltage Architecture Rapidly Penetrates Heavy-Duty Trucks
Explosive Growth in ...
ADAS and Autonomous Driving Tier 1 Suppliers Research Report, 2026 – Chinese Companies
Intelligent Driving Industry Leap: From Widespread L2.9 Adoption toward Physical AI and New Full?Domain Mobility Ecosystem
As vehicle intelligence advances, the installations and penetration rate of...
Vehicle-Road-Cloud Integration and C-V2X Industry Report, 2026
Vehicle-Road-Cloud and C-V2X Research: with the three-tier promotion system of "top-level planning + mandatory pilot + evaluation binding", the industry turning point is approachingThis report focuses...
China OEM Data Capability Analysis Report, 2026
OEM Data Capability Research: 24 OEMs × 9 Capability Domains, Who Takes the Lead?
An L4 autonomous driving R&D and test vehicle can generate approximately 10TB of raw data per single day — data v...
Autonomous Driving Domain Controller and Central Computing Unit (CCU) Industry Report, 2026
Autonomous Driving Domain Controller (ADCU) Research: One-Chip CCU solutions are quickly available in vehicles
In China's passenger car market, autonomous driving systems involved in mass production ...
Automotive EMS and ECU Industry Research Report, 2026
Automotive EMS Research: The boundaries between EMS providers and Tier1 suppliers are becoming blurred, and the supply chain model is evolving from a linear chain to a networked structure
Mainstream ...
Automotive Microcontroller Unit (MCU) and Application Scenario Research Report, 2026
Automotive MCU Research: Increased demand for redundant security drives ASIL D-compliant MCU shipments to exceed 100 million units
In a vehicle EEA, MCUs are widely distributed in various functional ...
China Intelligent Cockpit Patent Analysis Report, 2026
Intelligent Cockpit Patent Research: Cockpit AI, In?vehicle Health, and Infotainment Are Upgrade to Scenario?based and Proactive Functions
From a patent perspective, this report explores the cutting?...
Research Report on Application of VLA Large Model in Automobiles and Robots, 2026
Research on Automotive and Robot VLA: Hybrid Architectures Become Mainstream, VLA Integrates with General World Models, and Reinforcement Learning Serves as Core Engine
Vision?Language?Action (VLA) m...
China Charging Infrastructure (Supercharging, Battery Swapping, V2G, etc.) and High-Performance Supercharging Battery Research Report, 2026
Charging and battery swapping research: as 5C+ supercharging vehicle models go into mass production, the pace of OEMs self-building supercharging networks quickens
800-1000V high-voltage platforms ar...
China Passenger Car Electronic Controlled Suspension Industry Report, 2026
Electronic Controlled Suspension Industry Research: As the First Year of Full Active Suspension Unfolds, Three Technical Routes Race Forward
1. Penetration Rate Surges Three Times, and Electronic Con...
Intelligent Driving SoC Research Report, 2026
Research on Intelligent Driving SoCs: Competition Focus Shifts to L3/L4 Embedded Hardware, and Computing Power of Flagship Vehicle Models Exceeds 1,000 TOPS
In terms of intelligent driving system in...
Automotive AI Large Model Technology Research Report, 2026
Automotive AI Large Model Research: Competition Shifts from "Who Has the Stronger Model" to "Who Boasts Higher Link Efficiency"
ResearchInChina released the Automotive AI Large Model Technology Resea...