Sensor Chip Research: Automotive Sensors Have Entered a Technology Iteration Cycle, and Opportunities for Localization of Chips Are Coming
Automotive sensor chips can obtain external environment data for autonomous vehicles and improve the safety of autonomous driving as an indispensable part of autonomous vehicles. With the improvement of the autonomous driving level, the demand for sensor chips in vehicles will keep rising, and the requirements on product performance will also become higher and higher.
The demand for automotive cameras is growing rapidly, and domestic and foreign vendors are competing for the automotive CIS market
With the fast development of autonomous driving technology, the number of automotive cameras is gradually increasing. The higher the level of autonomous driving, the greater the demand for cameras. At present, all OEMs are actively deploying L3/L4 production autonomous models, which means the demand for automotive CIS chips is enormous.
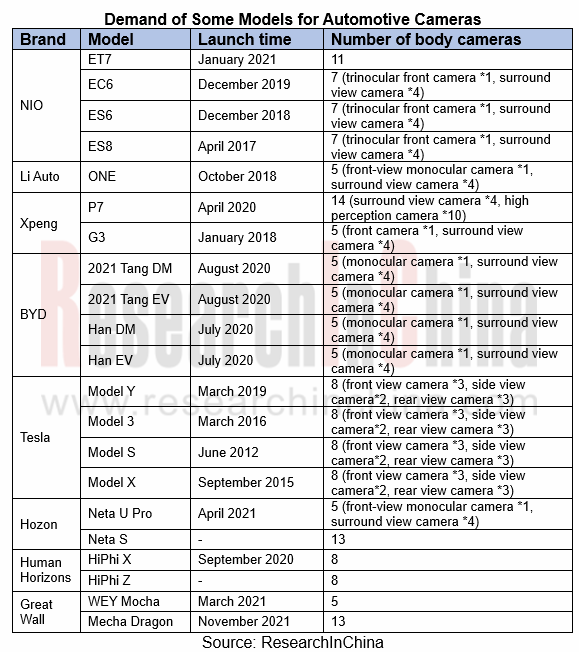
At present, the automotive CIS market is almost monopolized by oligarchs, with ON Semiconductor occupying nearly 60% market share. Traditional mobile phone camera CIS vendors such as Sony and Samsung have entered the automotive market, and the market share of OmniVision, a subsidiary of Will Semiconductor, is also increasing.
Sony entered the field of automotive CIS in 2015, and has mass-produced IMX490, IMX324 and other automotive CIS. NVIDIA's DRIVE Hyperion 8.1 platform launched in 2021 may use Sony's CIS IMX728 for the front-view camera and IMX623 for the fisheye camera.
In addition to CIS, Sony has also dabbled in the LiDAR chip market. In the first half of 2022, Sony plans to launch the IMX459 1/2.9-type (6.25 mm diagonal) stacked SPAD depth sensor for automotive LiDAR applications using direct Time-of-Flight (dToF) method. By leveraging Sony's technologies such as a back-illuminated pixel structure, stacked configurations, and Cu-Cu connections created in the development of CMOS image sensors, Sony has succeeded in a unique device construction that includes SPAD pixels and distance measuring processing circuit on a single chip.
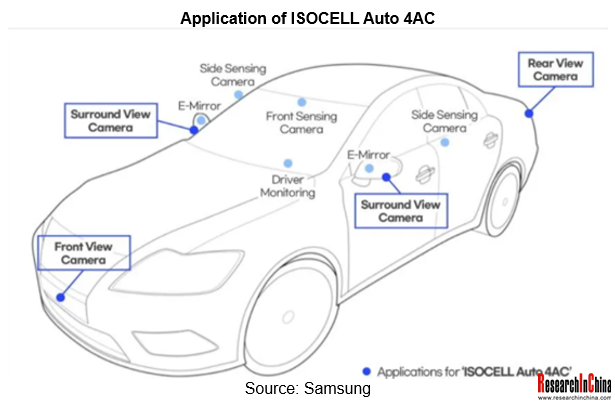
In July 2021, Samsung introduced ISOCELL Auto 4AC, an automotive image sensor. It comes in a 1/3.7-inch optical format with 1.2 million 3.0-micrometer (μm) pixels. With the CornerPixel? technology, it embeds two photodiodes within a single pixel area: one 3.0μm pixel for viewing low light images, and a 1.0μm pixel placed at the corner of the big pixel for brighter environments.
CIS has been out of stock for the past two years and the shortage will continue for some time. In the face of problems such as lack of chips for foreign-funded enterprises and rising product prices, Chinese local enterprises have seen development opportunities.
At CES 2022, OmniVision demonstrated an 8-megapixel automotive front-view camera system for the first time. Using next-generation OX08B40 CMOS image sensors, the system is powered by Xilinx MPSoC and Motovis IP. It will help OmniVision in the 8-megapixel high-end market to compete with ON Semiconductor.

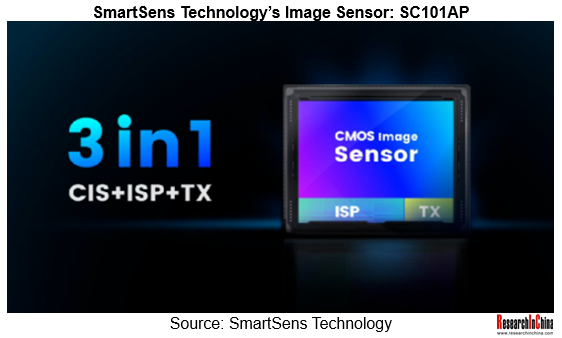
At the end of 2021, SmartSens Technology launched SC101AP, a three-in-one image sensor with integrated ISP and TX functions for automotive applications. The sensor has an optical size of 1/4.2 inches and a pixel size of 2.9μm. It supports video recording and shooting with a resolution of 1MP and 30 frames per second. Its sensitivity has improved by 53%, and the quantum efficiency has leveled up by 31%. SmartSens Technology will release a number of automotive products in 2022, including 8-megapixel ADAS products which are under development, and will be mass-produced in 2023.
GalaxyCore’s automotive CIS products have been used in driving recorders, 360° surround view cameras and cockpit monitoring.
In terms of technology development trends, CIS and ISP chips are both important chips for automotive cameras. ISP analyzes and processes image signals from CIS. Two-in-one automotive CMOS image sensors with ISP are gradually becoming the mainstream of the market. OmniVision's OX03D SoC integrates CMOS and ISP SoC. SmartSens Technology's SC120AT, a two-in-one image sensor with on-chip ISP, can optimize RAW image data and output high-quality video images in the format of YUV 422.
Amid the emerge of 4D radar and product iterations, the chip market pattern is expected to be reshaped
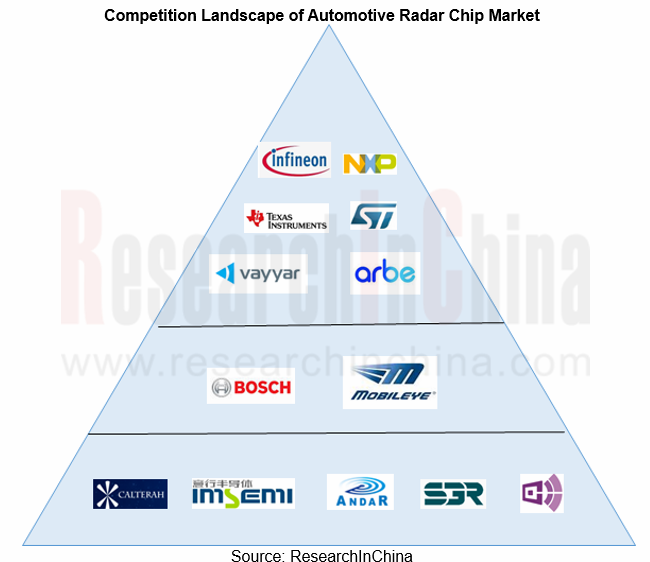
At present, radar chip suppliers are mainly from abroad, and the market share is basically occupied by NXP, Infineon, TI, etc. With the continuous development of autonomous driving, high-resolution radar and 4D radar have emerged. Radar chips have officially stepped into the technology iteration cycle. Domestic vendors may have the opportunity of taking the lead, and the market pattern will undergo certain changes.
(1) Traditional radar chip vendors promote technology upgrades and product cost reductions
Traditional chip vendors are the main players in the radar chip market, especially in the 4D radar chip market. At present, most of 4D solutions on the market adopt TI's chips.
In the past two years, traditional chip vendors have been aggressively improving product performance and further seeking cost control, and they have been committed to providing standardized product solutions for more radar companies.
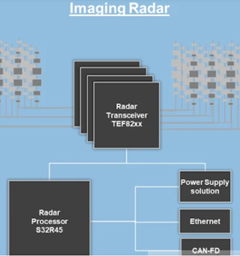
In 2020, NXP announced the first dedicated 16nm imaging radar processor, the NXP S32R45, which will be mass-produced in the first half 2022. The boost is enabled by the combination of proprietary radar hardware acceleration which can deliver up to 64x the compute performance of standard processors, super-resolution radar software algorithms to achieve sub-degree angular resolution and advanced MIMO waveforms that allow simultaneous operation of antenna channels.
The S32R45 radar processor is the flagship of NXP's 6th generation automotive radar chipset family. The combination of NXP’s S32R45 and S32R41 radar processors with the NXP TEF82xx RFCMOS transceivers delivers the fine angular resolution, processing power and range required for production-ready imaging radar solutions.
Texas Instruments launched AWR2944in January 2022, suitable for angular radar and long-range radar. It is approximately 30% smaller than the existing radar sensors, but provides 33% higher resolution than the latter, and detects objects up to 40% farther away from the vehicle.
(2) Domestic radar chip vendors and enterprises speed up their technological layout
Local vendors are at a disadvantage in the radar chip market, but with the iteration of product technology, they are catching up and actively deploying chip technology.
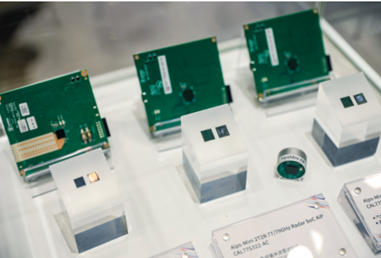
In October 2021, Calterah Semiconductor Technology released the Alps-Mini series automotive radar chips, which meet the automotive regulatory standards, AEC-Q100 and ISO 26262 ASIL-B. The network security unit added on the basis of the previous generation reduces the size by 40% and saves the cost by more than 20%.
In August 2021, Runchip unveiled a 77GHz radar chip - RF77TR34, which adopts RFCMOS process and integrates transceivers (3T4R), PLL, VCO, etc. It will provide samples to customers for evaluation in 2022.
(3) Automotive Tier 1 suppliers have dabbled in the upstream radar chip market
Most of the traditional radar Tier 1 suppliers mainly use third-party chips. In the past two years, they have been seeking changes, hoping to offer differentiated products through chip autonomy.
In 2021, Bosch and the chip foundry GlobalFoundries made a deal to jointly develop radar chips for autonomous driving. Bosch will use the 22FDX radio frequency solution of GlobalFoundries, which operates at a higher frequency, detects farther targets, and is more accurate than the current mainstream low-frequency radar chips.
Tier 1 suppliers have their own unique technology and core intellectual property (IP), which will help them enhance their own competitiveness.
LiDAR has been mass-produced for vehicles, while the chip cost has been declining fast
At present, the demand of production models for LiDAR is low due to its high cost. Chipization is one of the effective ways to slash costs; in addition, chip autonomy can also effectively cut down production costs and create differentiated competition.
(1) On-chip LiDAR
Integrating lasers, detectors, beam steering, and data processing into one chip to form an on-chip LiDAR can effectively reduce product size and costs.
In September 2021, LuminWave released two new chip optical engines - FMCW OE and OPA OE, which will be applied to LuminWave's silicon-optical chip-level FMCW 4D LiDAR products.
Compared with the first-generation chip, the second-generation FMCW SoC chip has four times more parallel FMCW computing units, and up to 128 channels. In addition, other key optical signal processing units are also integrated on the chip, making it one of the most integrated silicon photonics chips at present.
(2) Automotive Tier 1 suppliers deploy the upstream LiDAR chip industry
Now, Huawei, NVIDIA, HESAI, Ouster and other LiDAR Tier 1 suppliers are vigorously deploying the chip business, and forging the LiDAR industry chain by investing in chip makers or self-developing chips.
Ouster launched its self-developed LiDAR chip, L2X, in October 2021, successfully strengthening the company's LiDAR performance. In addition, Ouster acquired Sense Photonics in October 2021 to expand its LiDAR chip product line.
Huawei actively deploys the LiDAR industry chain. Through its subsidiary Hubble Ventures Co., Limited, it has invested in chip companies such as Vertilite and Nanjing visionICs Microelectronics Technology to make a layout for VCSEL, SPAD and other chip technologies. In 2012 and 2013, Huawei acquired CIP, a British photonic integration company, and Caliopa, a Belgian silicon photonics technology developer, to ensure its self-research capabilities in the field of optical chips, and to deploy silicon photonics chip-level FMCW technology in advance.
Automotive Sensor Chip Industry Research Report, 2022 highlights the following:
 Classification and industrial standards of automotive sensor chip, sensor chip industry chain (including image sensor chips, radar chips, LiDAR chips, ultrasonic radar chips, etc.), automotive sensor chip market scale, etc.;
Market size, market structure, technology trends, major suppliers, etc. of visual sensor chips;
Market size, market structure, technology trends, major suppliers, etc. of radar chips;
Market size, market structure, technology trends, major suppliers, etc. of LiDAR chips.
Automotive Microcontroller Unit (MCU) and Application Scenario Research Report, 2026
Automotive MCU Research: Increased demand for redundant security drives ASIL D-compliant MCU shipments to exceed 100 million units
In a vehicle EEA, MCUs are widely distributed in various functional ...
China Intelligent Cockpit Patent Analysis Report, 2026
Intelligent Cockpit Patent Research: Cockpit AI, In?vehicle Health, and Infotainment Are Upgrade to Scenario?based and Proactive Functions
From a patent perspective, this report explores the cutting?...
Research Report on Application of VLA Large Model in Automobiles and Robots, 2026
Research on Automotive and Robot VLA: Hybrid Architectures Become Mainstream, VLA Integrates with General World Models, and Reinforcement Learning Serves as Core Engine
Vision?Language?Action (VLA) m...
China Charging Infrastructure (Supercharging, Battery Swapping, V2G, etc.) and High-Performance Supercharging Battery Research Report, 2026
Charging and battery swapping research: as 5C+ supercharging vehicle models go into mass production, the pace of OEMs self-building supercharging networks quickens
800-1000V high-voltage platforms ar...
China Passenger Car Electronic Controlled Suspension Industry Report, 2026
Electronic Controlled Suspension Industry Research: As the First Year of Full Active Suspension Unfolds, Three Technical Routes Race Forward
1. Penetration Rate Surges Three Times, and Electronic Con...
Intelligent Driving SoC Research Report, 2026
Research on Intelligent Driving SoCs: Competition Focus Shifts to L3/L4 Embedded Hardware, and Computing Power of Flagship Vehicle Models Exceeds 1,000 TOPS
In terms of intelligent driving system in...
Automotive AI Large Model Technology Research Report, 2026
Automotive AI Large Model Research: Competition Shifts from "Who Has the Stronger Model" to "Who Boasts Higher Link Efficiency"
ResearchInChina released the Automotive AI Large Model Technology Resea...
Intelligent Vehicle Cockpit Domain Controller Research Report, 2026
Cockpit domain controller research: L3 AIDV intelligent cockpit domain controllers are entering a boom period
Driven by multiple factors such as the continuous evolution of the automotive central int...
Automotive Acoustic System (Audio, Multi-Channel) Industry Report, 2026
Automotive Acoustics Research: Multiple Channels, AI Tuning, and Self-Developed Algorithms Drive the Transformation of High-End Cockpit Sound Fields
I. Automotive Audio Hardware Solutions with 6–9 S...
Autonomous Driving Sensor Chip Research Report, 2026
Research on Autonomous Driving Sensor Chips: Deeply Perceiving the Physical World, Sensor Chips Are Playing A “Leading Role” in Intelligence
In 2026, the autonomous driving sensor chip industr...
Passenger Car Corner Module and Wheel‑Side Control System Research Report, 2026
Wheel-side control research: the “last mile” chassis innovation
Wheel-side control dismantles the traditional drive, braking, steering, and suspension control of the chassis from a "centralized" styl...
Embodied Artificial Intelligence (& Humanoid Robot) MCU Research Report, 2026
Research on Humanoid Robot MCUs: Evolution from General-Purpose Control to High-Value Dedicated Chip Solutions Integrated with Edge AI Functions
MCU (Microcontroller Unit) refers to a compact integra...
Intelligent Vehicle Zone Control Unit (ZCU) Research Report, 2026
ZCU Research: Cross-domain integrated ZCUs are becoming the edge computing nodes of the next-generation zonal architecture
Currently, the mainstream zonal architecture is mainly the quasi-central + z...
Automotive Cybersecurity and Data Security Research Report, 2026
Cybersecurity & Data Security Research: Intelligent Connected Vehicles Enter the Era of “Systematic Offense-Defense and AI-Defined Security”.
Centering on the panorama of intelligent connect...
Report on Breakthrough Strategies of OEMs and ADAS Tier 1 Suppliers for Overseas Layout of Intelligent Driving, 2026
Regulatory Breakthrough, Local System Establishment, OEMs Competing for NOA Layout: Overall Trends of China’s Intelligent Driving Overseas Layout in 2026
Research on overseas intelligent driving layo...
OEMs and Tier1s’ Intelligent Cockpit Platform (Hardware and Software) Innovation Strategy Research Report, 2026
Intelligent Cockpit Platform Research: multi-dimensional cockpit system architecture reconstruction for multi-agent collaboration and proactive intelligent services
The intelligent cockpit software s...
Automotive AIOS Research Report, 2026
Automotive AIOS Research: Mass Production Solutions Are Implemented
Mass Production Solutions Are Implemented on A Small Scale.
In 2026, AIOS starts small-scale implementation, helping to improve v...
Automotive Telematics Service Provider (TSP) Research Report, 2026
TSP Research: Leading providers collectively turn to AI agents to provide all-scenario active services
Telematics Service Providers (TSPs) are the core hub of the telematics industry chain, connectin...