Global and Chinese Automakers’ Modular Platforms and Technology Planning Research Report, 2022
Research on Automakers’ Platforms and Their Planning: the Strategic Layout Directions of 32 Automakers
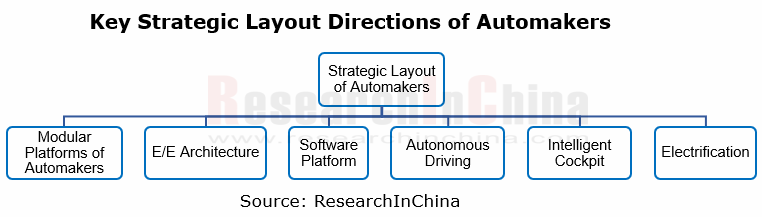
At present, global automotive industry is in the midst of profound changes unseen in a century. This can be intensively demonstrated through energy, power system, E/E architecture, intelligence and connectivity, application scenarios, user experience, and more. In this context, major automakers are changing their strategic layout. They work hard on key areas from automotive manufacturing platforms, E/E architecture and software platforms to autonomous driving, intelligent cockpit and electrification, and attract consumers and satisfy their needs with differentiated products.
1. Automakers keep upgrading their modular platform architectures.
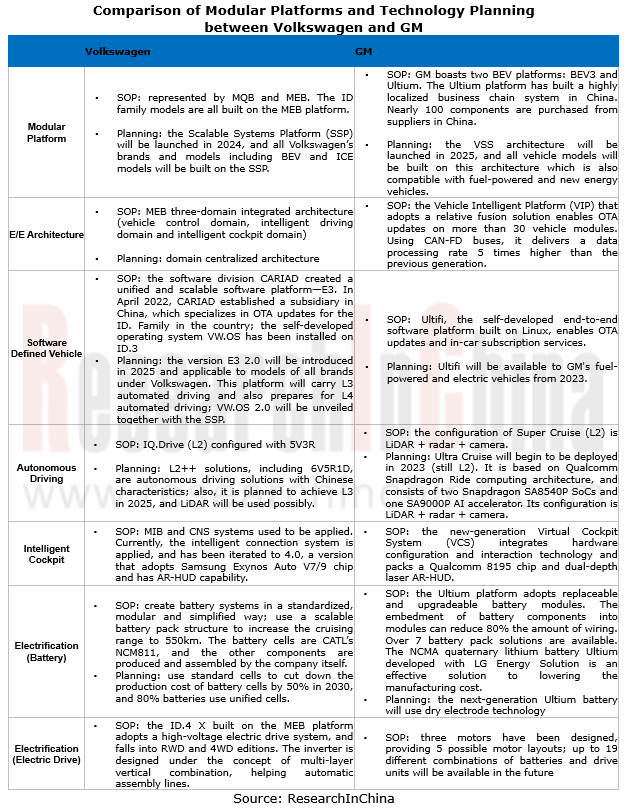
Modular platforms remain superior in increasing the universality of components and lowering R&D and production costs. At present, most automakers have their own modular platforms, or even multiple platforms. Modular architecture outperforms a modular platform. It is an extension and expansion of the platform concept. With higher universality of components and higher scalability, modular architecture is compatible with vehicles of differing classes and power types. Automakers therefore have started gradual transition from modular platform to modular architecture.
Modular architecture favors higher productivity, lower procurement/manufacturing costs, and shorter R&D cycles. In current stage, the generalization rate of components in GAC Global Platform Modular Architecture (GPMA) surpass 60%, compared with 70% in Geely Sustainable Experience Architecture (SEA) and 70%-80% in Toyota New Global Architecture (TNGA).
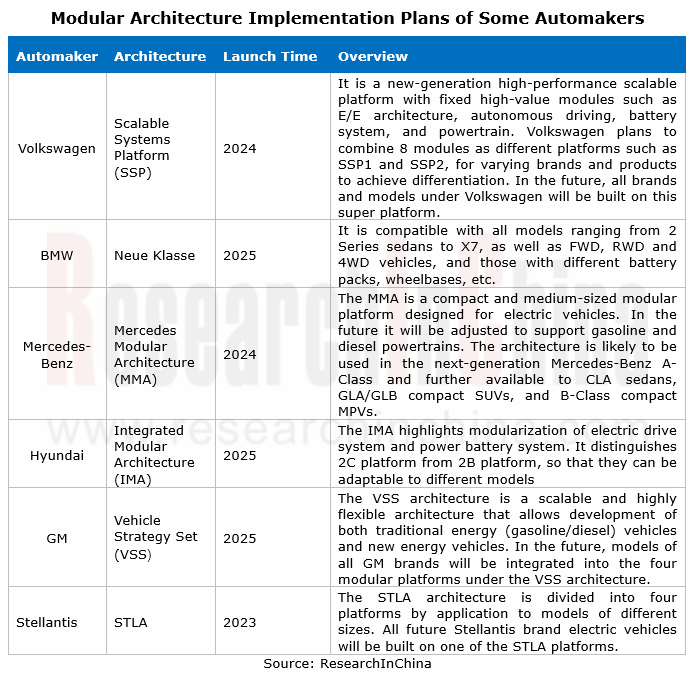
At present, automakers in China deploy modular architectures relatively early. Among them, BYD, Geely, Chery, and Changan Automobile have launched their own modular architectures. The modular architecture launches of foreign peers are concentrated in the period from 2024 to 2025.
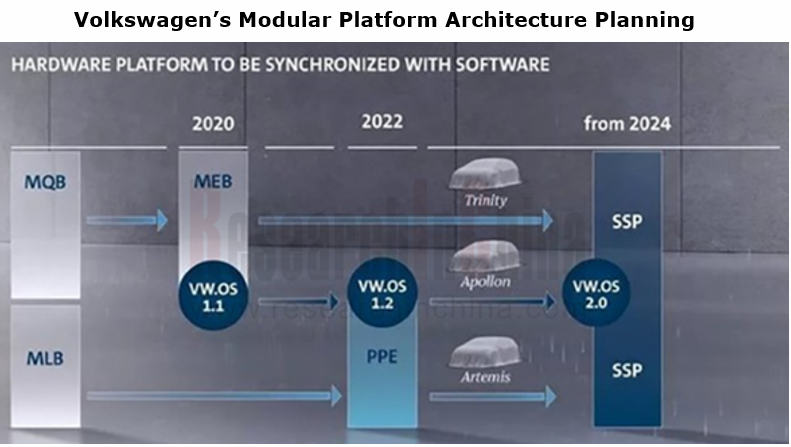
Taking Volkswagen as an example, the company plans to eventually integrate its platforms into SSP, a scalable mechatronics platform architecture applicable to all Volkswagen’s brands and models. In the future, all brands and models at all levels under Volkswagen will be built on this super platform.
2. EEA tends to be centralized.
Through the lens of E/E architecture planning, most automakers plan to deploy centralized vehicle E/E architectures:
GAC projects installation of the centralized E/E architecture "Protoss" in 2023 Aion high-end models;
Hongqi plans launch of its quasi-central architecture FEEA3.0 in 2023;
Great Wall Motor plans to introduce its central computing architecture GEEP 5.0 in 2024;
Changan Automobile is expected to complete the development of its domain centralized architecture in 2025.
For example, GAC has upgraded its E/E architecture in all aspects and has developed the Protoss E/E Architecture, its new vehicle-cloud integrated E/E architecture that enables centralized computing and is about to come out in 2023 at the earliest. This architecture consists of three core computer groups, i.e., central computer, intelligent driving computer and infotainment computer, and four zonal controllers. The intelligent driving domain carries Huawei Ascend 610, a 400TOPS high-performance chip.
3. Automakers transform from independent software platform developers to software service providers.
As autonomous driving and intelligent connectivity boom, large automakers have set off a new round of “software-defined vehicle”-centric transformation and upgrading. Some transform themselves to software service providers by way of establishing software divisions/subsidiaries, independently developing operating systems (OS), and building software platforms.
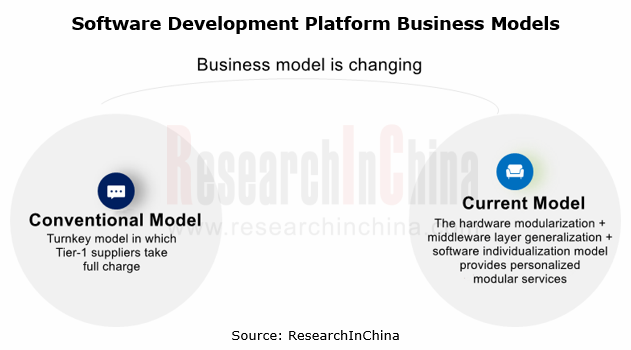
Compared with the turnkey model in which Tier-1 suppliers take full charge in conventional vehicle supply chain, auto brands now take more active part. Joint R&D and flat cooperation gradually blur the boundaries of the supply chain ecosystem, and also diversifies the needs for business models. Modular services thus need providing to meet the individual needs of auto brands with differentiated configurations for different vehicle models. For example, Bosch adopts hardware modularization + middleware layer generalization + software individualization model and adjusts parameters to quickly address the needs of different functions.
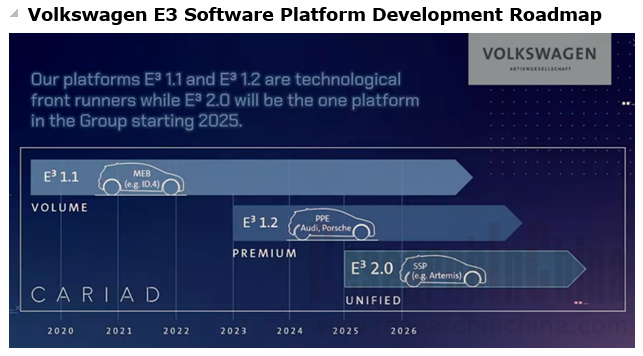
Volkswagen is a typical automaker that develops software on its own. In 2019, Volkswagen established a software division and planned to boost the in-house share of car software development from less than 10% to at least 60% in the five years to come. In 2021, Volkswagen changed the software division into CARIAD, a joint-stock company which will be responsible for independently developing the automotive operating system VW.OS and creating the software platform E3. In April 2022, CARIAD announced its China strategy. Its Chinese subsidiary was then established.
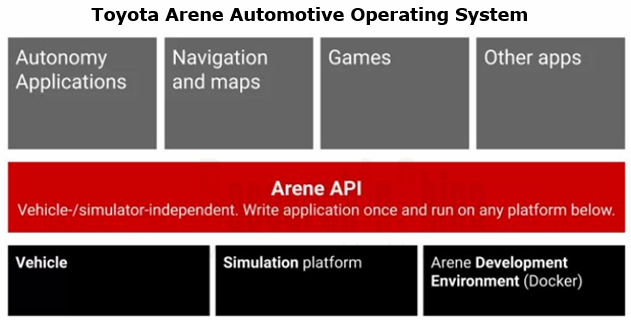
In addition to Volkswagen, GM, Toyota, Mercedes-Benz, Hyundai, SAIC and the like have also begun to self-develop operating systems and deploy their own software platforms, aiming to transform from an automaker to a software service provider. Toyota, which recently acquired the automotive operating system provider Renovo Motors, plans to roll out its own operating system, Arene, in 2025.
4. L3 automated driving of OEMs comes into service.
The mainstream automakers deploy autonomous driving in the following ways:
? Investing in acquiring autonomous driving startups
? Partnering with big tech firms
? Cooperating with other OEMs
? Self-developing, or combining the above ways
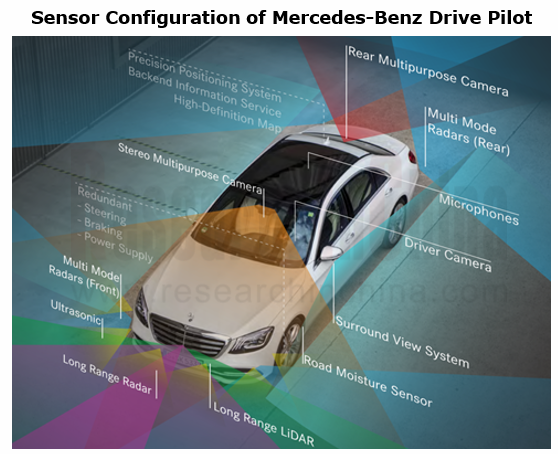
On this basis, these automakers have also introduced their own autonomous driving assistance systems, including Volkswagen IQ.Drive, Toyota Advanced Drive, Mercedes-Benz Drive Pilot, Geely G-Pilot, and GAC ADiGO. Among them, Mercedes-Benz is the world’s first automotive company to meet the United Nations regulation UN-R157. Mercedes-Benz marketed its L3 automated driving system Drive Pilot in Germany in May 2022, and announced that it will be responsible for accidents caused by the system when activated.
Sensor configuration of Mercedes-Benz Drive Pilot:
? 1 LiDAR
? 1 long-range radar
? 4 short-range radars
? 1 stereo camera
? 1 rear view camera
? 1 in-vehicle driver monitoring camera
? 1 differential GPS
Sensor configuration of automated parking:
? 4 surround view cameras
? 12 ultrasonic sensors
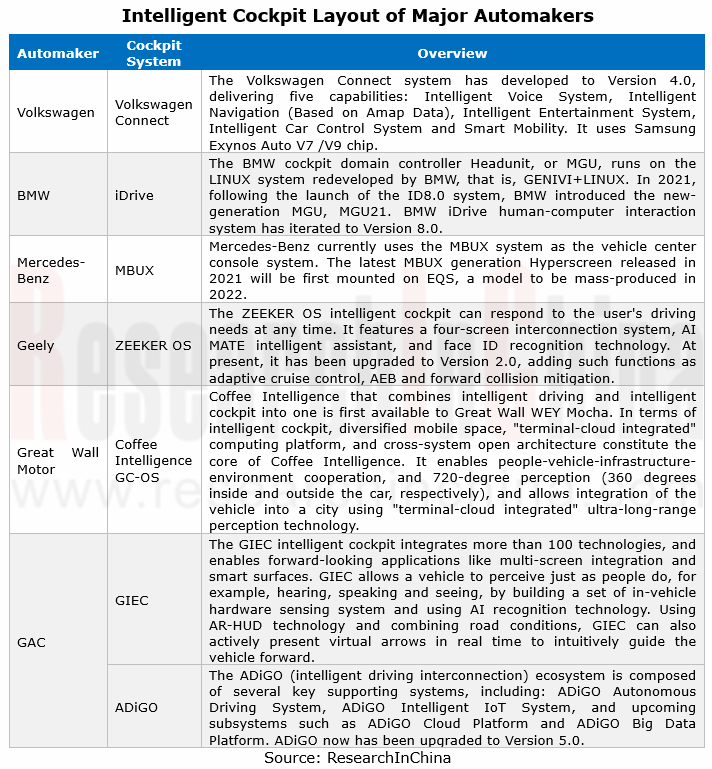
5. Intelligent cockpit interconnection platforms connect vehicles, people and everything, playing a more important role.
As the Internet thrives, major automakers show much enthusiasm for intelligent cockpits. Almost all of them have rolled out different intelligent cockpit interconnection platforms as selling points, in a bid to attract consumers. Examples include BMW iDrive and Mercedes-Benz MBUX, BYD DiLink and Geely GKUI.
Automotive Microcontroller Unit (MCU) and Application Scenario Research Report, 2026
Automotive MCU Research: Increased demand for redundant security drives ASIL D-compliant MCU shipments to exceed 100 million units
In a vehicle EEA, MCUs are widely distributed in various functional ...
China Intelligent Cockpit Patent Analysis Report, 2026
Intelligent Cockpit Patent Research: Cockpit AI, In?vehicle Health, and Infotainment Are Upgrade to Scenario?based and Proactive Functions
From a patent perspective, this report explores the cutting?...
Research Report on Application of VLA Large Model in Automobiles and Robots, 2026
Research on Automotive and Robot VLA: Hybrid Architectures Become Mainstream, VLA Integrates with General World Models, and Reinforcement Learning Serves as Core Engine
Vision?Language?Action (VLA) m...
China Charging Infrastructure (Supercharging, Battery Swapping, V2G, etc.) and High-Performance Supercharging Battery Research Report, 2026
Charging and battery swapping research: as 5C+ supercharging vehicle models go into mass production, the pace of OEMs self-building supercharging networks quickens
800-1000V high-voltage platforms ar...
China Passenger Car Electronic Controlled Suspension Industry Report, 2026
Electronic Controlled Suspension Industry Research: As the First Year of Full Active Suspension Unfolds, Three Technical Routes Race Forward
1. Penetration Rate Surges Three Times, and Electronic Con...
Intelligent Driving SoC Research Report, 2026
Research on Intelligent Driving SoCs: Competition Focus Shifts to L3/L4 Embedded Hardware, and Computing Power of Flagship Vehicle Models Exceeds 1,000 TOPS
In terms of intelligent driving system in...
Automotive AI Large Model Technology Research Report, 2026
Automotive AI Large Model Research: Competition Shifts from "Who Has the Stronger Model" to "Who Boasts Higher Link Efficiency"
ResearchInChina released the Automotive AI Large Model Technology Resea...
Intelligent Vehicle Cockpit Domain Controller Research Report, 2026
Cockpit domain controller research: L3 AIDV intelligent cockpit domain controllers are entering a boom period
Driven by multiple factors such as the continuous evolution of the automotive central int...
Automotive Acoustic System (Audio, Multi-Channel) Industry Report, 2026
Automotive Acoustics Research: Multiple Channels, AI Tuning, and Self-Developed Algorithms Drive the Transformation of High-End Cockpit Sound Fields
I. Automotive Audio Hardware Solutions with 6–9 S...
Autonomous Driving Sensor Chip Research Report, 2026
Research on Autonomous Driving Sensor Chips: Deeply Perceiving the Physical World, Sensor Chips Are Playing A “Leading Role” in Intelligence
In 2026, the autonomous driving sensor chip industr...
Passenger Car Corner Module and Wheel‑Side Control System Research Report, 2026
Wheel-side control research: the “last mile” chassis innovation
Wheel-side control dismantles the traditional drive, braking, steering, and suspension control of the chassis from a "centralized" styl...
Embodied Artificial Intelligence (& Humanoid Robot) MCU Research Report, 2026
Research on Humanoid Robot MCUs: Evolution from General-Purpose Control to High-Value Dedicated Chip Solutions Integrated with Edge AI Functions
MCU (Microcontroller Unit) refers to a compact integra...
Intelligent Vehicle Zone Control Unit (ZCU) Research Report, 2026
ZCU Research: Cross-domain integrated ZCUs are becoming the edge computing nodes of the next-generation zonal architecture
Currently, the mainstream zonal architecture is mainly the quasi-central + z...
Automotive Cybersecurity and Data Security Research Report, 2026
Cybersecurity & Data Security Research: Intelligent Connected Vehicles Enter the Era of “Systematic Offense-Defense and AI-Defined Security”.
Centering on the panorama of intelligent connect...
Report on Breakthrough Strategies of OEMs and ADAS Tier 1 Suppliers for Overseas Layout of Intelligent Driving, 2026
Regulatory Breakthrough, Local System Establishment, OEMs Competing for NOA Layout: Overall Trends of China’s Intelligent Driving Overseas Layout in 2026
Research on overseas intelligent driving layo...
OEMs and Tier1s’ Intelligent Cockpit Platform (Hardware and Software) Innovation Strategy Research Report, 2026
Intelligent Cockpit Platform Research: multi-dimensional cockpit system architecture reconstruction for multi-agent collaboration and proactive intelligent services
The intelligent cockpit software s...
Automotive AIOS Research Report, 2026
Automotive AIOS Research: Mass Production Solutions Are Implemented
Mass Production Solutions Are Implemented on A Small Scale.
In 2026, AIOS starts small-scale implementation, helping to improve v...
Automotive Telematics Service Provider (TSP) Research Report, 2026
TSP Research: Leading providers collectively turn to AI agents to provide all-scenario active services
Telematics Service Providers (TSPs) are the core hub of the telematics industry chain, connectin...