Chinese ADAS and Autonomous Driving Tier 1 Suppliers Report, 2021-2022
Autonomous Driving Tier 1 Suppliers Research: the installation rate of L2 and above autonomous driving functions in passenger cars hit over 30% in 2022Q1.
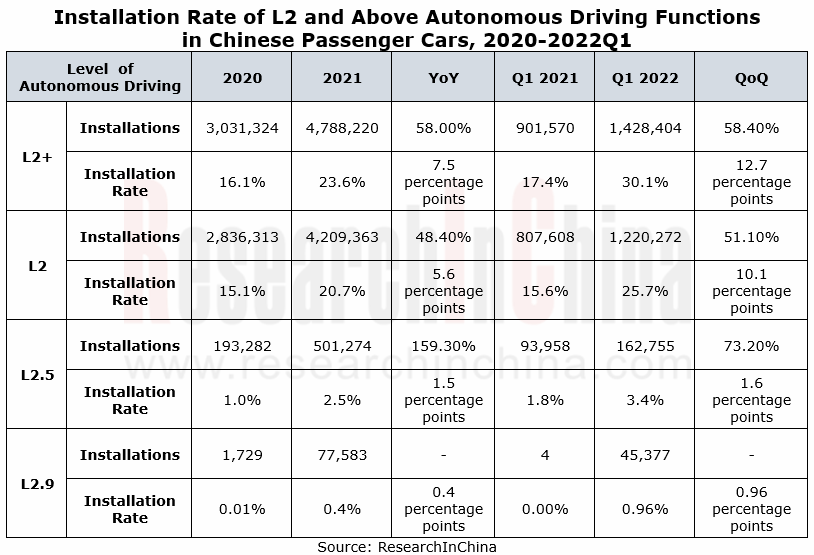
In 2022Q1, the installation rate of L2 and above autonomous driving functions in Chinese passenger cars reached 30.1%, a year-on-year increase of 12.7 percentage points. Specifically, the L2 installation rate went up by 10 percentage points to 25.7%; the L2.5 installation rate rose by 1.6 percentage points to 3.43%; the L2.9 installation rate edged up by 0.95 percentage points to 0.96%.
The boom of ADAS favored a surge in Tier 1 suppliers’ revenue from autonomous driving products.
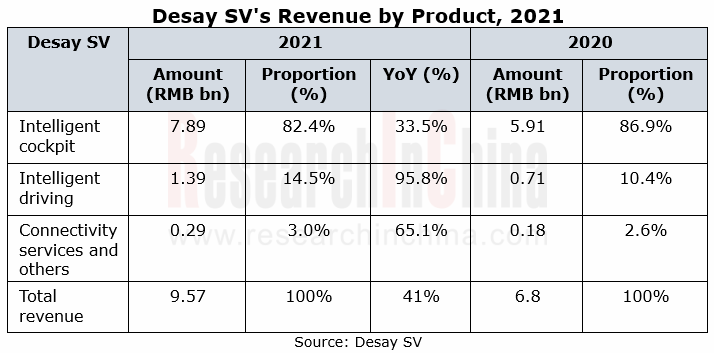
In 2021, Desay SV's revenue from intelligent driving products hit RMB1.39 billion, a year-on-year spike of 95.8%. Desay SV entering the field of autonomous driving in 2016 primarily produces cameras, radars and domain controllers. In the future, it will still focus on perception fusion algorithms and control strategy, and will make further deployments in L3 and L4 autonomous driving solutions. Its domain controller IPU03 was mass-produced for Xpeng P7 in April 2020; the domain controller IPU04 launched in September 2021 is scheduled to be used by Li Auto in 2022; the intelligent computing platform (ICP) "Aurora" became available on market in April 2022.
Neusoft Reach started deploying autonomous driving in 2004. The company works on R&D and commercialization of autonomous driving core technologies, covering autonomous driving systems such as visual perception, embedded high-performance computing, sensor fusion, decision and planning, and vehicle control.
Neusoft Reach provides technologies and solutions for passenger car/commercial vehicle products. Its autonomous driving products include front view smart cameras, driver monitoring systems, domain controllers, and central computing platforms. Its self-developed automotive basic software platform NeuSAR enables effective decoupling of software and hardware. The encapsulation of end-cloud cooperation middleware services helps to connect vehicle-cloud cooperation value data communication links and mobilize cloud platform services to enable the continuous intelligent driving iterations and updates at the vehicle end.
Jingwei Hirain’s revenue from intelligent driving electronics sustained AAGRs of over 100% in recent three years. Jingwei Hirain has begun to deploy autonomous driving in 2015, and established its intelligent driving division in 2017. Its products are led by cameras, radars, domain controllers, computing platforms and chassis-by-wire. The company is working hard to develop system software technology.
Both conventional Tier 1 suppliers and emerging Tier 1 Internet firms are deploying decision layer products
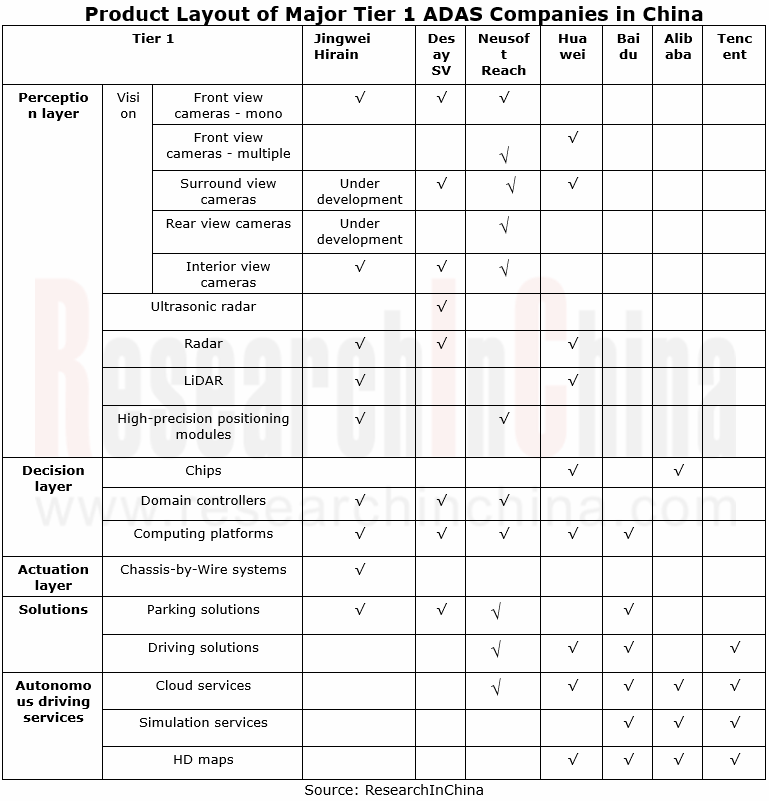
Decision layer products are the bridge between the perception layer and the execution layer. As the core products of high-level autonomous driving, they are responsible for computing, judgment, and decision. At present, Jingwei Hirain, Desay SV, Neusoft Reach, Huawei, and Baidu all have launched their own domain controllers and computing platforms.
Huawei set up the "Internet of Vehicles Division" in 2013. It dabbles in the field of smart cars by starting with the automotive communication module ME909T. Huawei has started developing autonomous driving communication architecture since 2015, and has rolled out the autonomous driving AI chip "Ascend", the Ascend-based intelligent driving computing platform MDC, the intelligent driving cloud service “Octopus”, the intelligent driving operating system AOS, LiDAR, 4D imaging radar, etc.
Huawei keeps enriching its computing platform offerings. In October 2018, Huawei first introduced its intelligent driving computing platforms, MDC600 for L3 autonomous driving and MDC300 for L4. In September 2020, it unveiled MDC210 for L2+ and MDC610 for L3-L4. The vehicle models in which Huawei is negotiating on use of MDC610 include GAC AION LX, Great Wall Salon Mecha Dragon, and GAC Trumpchi. In April 2021 Huawei announced MDC810 an intelligent driving computing platform that supports L4-L5 and will be first seen in BAIC ARCFOX αS Huawei Inside (HI) Edition. The installation of the chip in 2022 Neta TA and GAC Aion is under negotiation. Huawei also plans to launch MDC100 in 2022.
The Institute of Deep Learning Baidu founded in July 2013 has launched an autonomous vehicle project and developed the Apollo autonomous driving open platform. It has introduced autonomous driving service products such as autonomous driving cloud service, simulation service, HD map. In 2021, its products were extended to autonomous driving solutions and decision products. In April 2021, its AVP solution and the corresponding computing platform were first mounted on Weltmeister W6.
Emerging Tier 1 companies are eagerly converting their role in the industry chain.
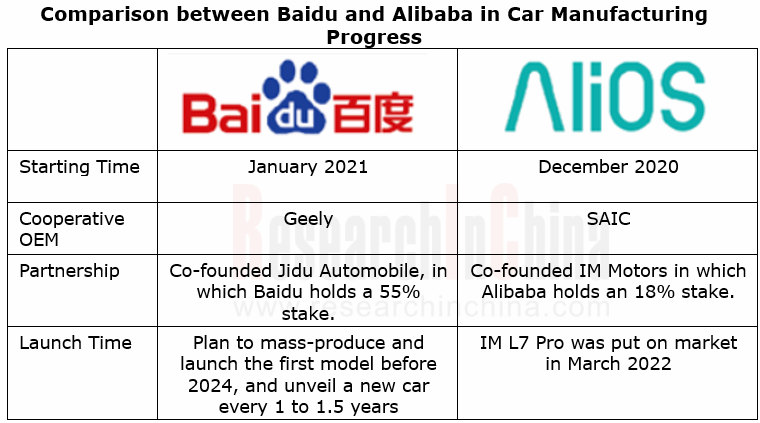
Emerging Tier 1 companies (Baidu, Alibaba, etc.) have made a foray into the automotive field with their superior software technology and data platforms. They are accelerating the development of software-defined vehicles and shortening the development cycle of new automotive products. Meanwhile, they have realized that the Tier 1 market is limited and they need to vigorously change their role in the industry chain into a partner of conventional OEMs to jointly build cars. For example, Alibaba and SAIC together established IM Motors in 2020; Baidu and Geely co-funded Jidu Automobile in 2021.
Robot Manufacturers’ Device-Cloud Collaborative Hybrid Computing Deployment Solution Research Report, 2026
EAI Device-Edge-Cloud Collaboration Research: How to Deliver After Layering, Summary of the Ranking for 12 Robot Manufacturers
China’s shipments of humanoid robots are projected to reach 50,000 unit...
China Passenger Car HUD Industry Report, 2026
HUD Research: Installation Rate Exceeds 25% as Entry Price of P-HUD-Equipped Models Falls to RMB130,000
The China Passenger Car HUD Industry Report, 2026 released by ResearchInChina combs through HUD...
Passenger Car Electronic and Electrical Architecture (EEA) and Technology Supply Chain Construction Strategy Research Report, 2026-2027
Passenger Car EEA: The Next-Generation AI EEA Is Gaining Momentum, Enabling Vehicles to Achieve "Autonomous Perception - Autonomous Decision-Making - Autonomous Evolution"
Vehicle Architecture Is Ev...
Next-generation Central and Zonal Communication Network Topology and Chip Industry Research Report, 2026-2027
Research on Zonal Communication Topology: New Architectures Including 10 BASE-T1S+RCP, AVB/TSN Ethernet Are Under Rapid Development
Vehicle communication networks are mainly divided into in-vehicle n...
Software-Defined Vehicles in 2026: Software Supply Chain Panorama and Business Models Research
Research on Automotive Software Business Models: Exploration of Token Economy, AI Service Revenue Sharing and Other Businesses
Under the Trend of AI Agents: Exploration of Business Models Based on T...
New Energy Commercial Vehicle 800-1000V High-Voltage Platform & Supply Chain Panorama Research Report, 2026
Research on 800V Architecture of Commercial Vehicles: New Energy Penetration Rate Exceeds 35%, and 800V Full-Domain High-Voltage Architecture Rapidly Penetrates Heavy-Duty Trucks
Explosive Growth in ...
ADAS and Autonomous Driving Tier 1 Suppliers Research Report, 2026 – Chinese Companies
Intelligent Driving Industry Leap: From Widespread L2.9 Adoption toward Physical AI and New Full?Domain Mobility Ecosystem
As vehicle intelligence advances, the installations and penetration rate of...
Vehicle-Road-Cloud Integration and C-V2X Industry Report, 2026
Vehicle-Road-Cloud and C-V2X Research: with the three-tier promotion system of "top-level planning + mandatory pilot + evaluation binding", the industry turning point is approachingThis report focuses...
China OEM Data Capability Analysis Report, 2026
OEM Data Capability Research: 24 OEMs × 9 Capability Domains, Who Takes the Lead?
An L4 autonomous driving R&D and test vehicle can generate approximately 10TB of raw data per single day — data v...
Autonomous Driving Domain Controller and Central Computing Unit (CCU) Industry Report, 2026
Autonomous Driving Domain Controller (ADCU) Research: One-Chip CCU solutions are quickly available in vehicles
In China's passenger car market, autonomous driving systems involved in mass production ...
Automotive EMS and ECU Industry Research Report, 2026
Automotive EMS Research: The boundaries between EMS providers and Tier1 suppliers are becoming blurred, and the supply chain model is evolving from a linear chain to a networked structure
Mainstream ...
Automotive Microcontroller Unit (MCU) and Application Scenario Research Report, 2026
Automotive MCU Research: Increased demand for redundant security drives ASIL D-compliant MCU shipments to exceed 100 million units
In a vehicle EEA, MCUs are widely distributed in various functional ...
China Intelligent Cockpit Patent Analysis Report, 2026
Intelligent Cockpit Patent Research: Cockpit AI, In?vehicle Health, and Infotainment Are Upgrade to Scenario?based and Proactive Functions
From a patent perspective, this report explores the cutting?...
Research Report on Application of VLA Large Model in Automobiles and Robots, 2026
Research on Automotive and Robot VLA: Hybrid Architectures Become Mainstream, VLA Integrates with General World Models, and Reinforcement Learning Serves as Core Engine
Vision?Language?Action (VLA) m...
China Charging Infrastructure (Supercharging, Battery Swapping, V2G, etc.) and High-Performance Supercharging Battery Research Report, 2026
Charging and battery swapping research: as 5C+ supercharging vehicle models go into mass production, the pace of OEMs self-building supercharging networks quickens
800-1000V high-voltage platforms ar...
China Passenger Car Electronic Controlled Suspension Industry Report, 2026
Electronic Controlled Suspension Industry Research: As the First Year of Full Active Suspension Unfolds, Three Technical Routes Race Forward
1. Penetration Rate Surges Three Times, and Electronic Con...
Intelligent Driving SoC Research Report, 2026
Research on Intelligent Driving SoCs: Competition Focus Shifts to L3/L4 Embedded Hardware, and Computing Power of Flagship Vehicle Models Exceeds 1,000 TOPS
In terms of intelligent driving system in...
Automotive AI Large Model Technology Research Report, 2026
Automotive AI Large Model Research: Competition Shifts from "Who Has the Stronger Model" to "Who Boasts Higher Link Efficiency"
ResearchInChina released the Automotive AI Large Model Technology Resea...