Automotive Memory Chip Research: Localization is imperative amid intense competition
The global smart phone storage market size hit US$46 billion in 2021 when the global automotive storage market size reached about US$4.5 billion, which is only equivalent to 1/10 of the former. Under development trend of intelligent connected vehicles, automobiles will become one of main growth engines of memory IC industry. By 2027, global automotive storage market size will exceed US$12.5 billion, with a CAGR of 18.6% from 2021 to 2027.
According to Micron Technology, the automotive storage market in China amounted to about US$700 million in 2021, and it will jump to US$1.5 billion by 2023. On the one hand, the growth momentum comes from growth of automobile shipments in China; on the other hand, it also benefits from continuous expansion of automotive memory and memory capacity.
High-level autonomous vehicles have posed enormous demand for automotive memory capacity, density and bandwidth
At present, main storage applications in automotive market include DRAM(DDR, LPDDR) and NAND (e.MMC and UFS, etc.). Low-power LPDDR and NAND will be main growth engines, and the demand for NOR Flash, used for chip startup, will continue to increase. In addition, higher intelligent driving levels will have a direct impact on the demand for GDDR, which is RAM specially used for ADAS floating-point computing chips in vehicles.
More powerful sensors, ADAS/AD integrated systems, central computers, digital cockpits, event recording systems,terminal-cloud computing, vehicle FOTA, etc. all put forward higher requirements for automotive memory. On the one hand, the memory capacity will go up from gigabytes (GB) to terabytes (TB); on the other hand, the memory density and bandwidth will be greatly improved.
For example, NAND Flash mainly store continuous data in ADAS, IVI systems, automotive center console systems, etc. As autonomous driving levels up, the demand for NAND capacity in ADAS has swelled. Generally, L1/L2 ADAS only requires the mainstream 8GB e-MMC, L3 needs 128/256GB, and L5 may involve over 2TBt. In the future, the data production, transmission and recording of advanced autonomous vehicles will require higher density and speed, so that PCIe SSD may be adopted.
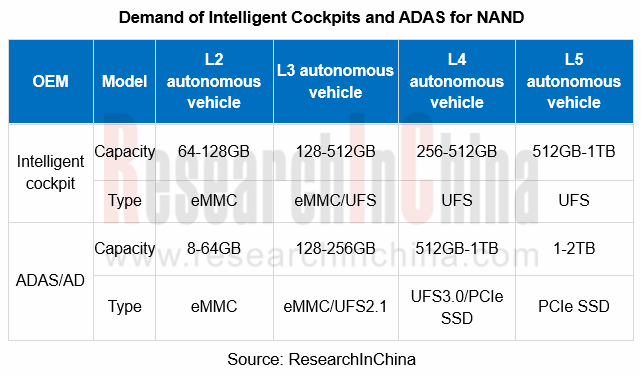
Autonomous vehicles boast more and more internal and external perception devices, including front cameras, internal cameras, high-resolution imaging radar, LiDAR, etc., and they will exploit high-density NOR Flash(QSPI, xSPI, etc., for chip startup) and DRAM(LPDDR3/4, LPDDR5, GDDR, etc.) widely.
At present, L1-L2 autonomous vehicles largely use LPDDR3 or LPDDR4, with the bandwidth of 25-50 GB/s. The bandwidth requirement is raised to 200GB/s for L3 autonomous driving, 300GB/s for L4 and 500GB/s for L5. Therefore, LPDDR5 and GDDR6 with higher bandwidth can simplify the system design of high-level autonomous vehicles.
Counterpoint’s data shows that in the next decade, the memory capacity of a single vehicle will reach 2TB~11TB, catering to the requirements of different autonomous driving levels.
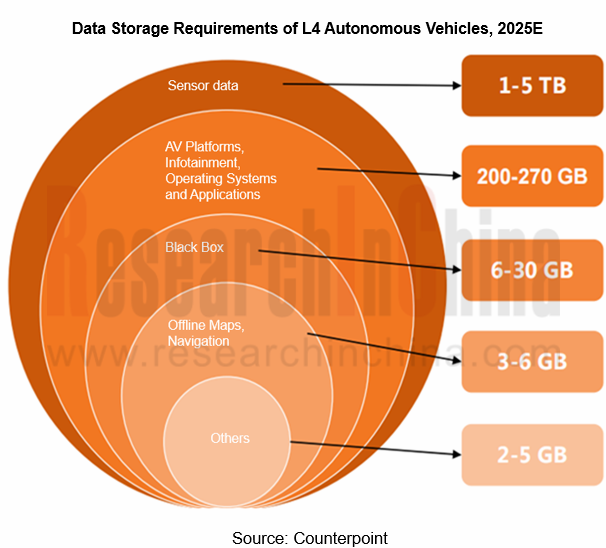
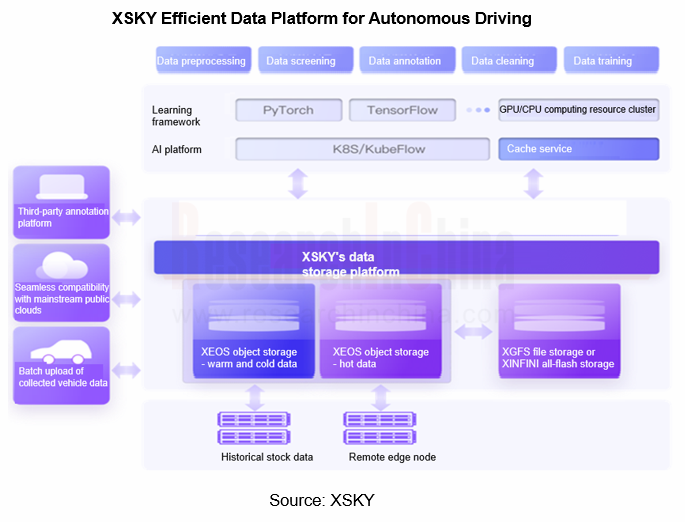
At the same time, autonomous driving is driven by data. The development of ADAS platforms needs massive road test data from cameras, radar, LiDAR, GPS and the like. These data are uploaded to the cloud for storage, AI training, simulation testing and verification. A one-hour L2 or L4-L5 road test probably generates 2TB or 16-20TB of data correspondingly, so that a single road test will produce 8-60TB of data, and the entire development cycle will churn out exabytes (EB) of data.
This has triggered huge market demand for autonomous driving cloud storage. In China, there are many cloud service providers that offer product solutions for autonomous driving data cloud storage, including Tencent Cloud, Alibaba Cloud, WD My Cloud, Sugon ParaStor, YRCloudFile, XSKY and so on.
As the functions of intelligent cockpits become more and more diversified, larger storage capacity is constantly in demand, and storage technology is constantly innovating
With the wide application of central integrated digital cockpits, DRAM has evolved from DDR2 and DDR3 to LPDDR4, LPDDR5 or GDDR. In addition, the interface of mobile phones has transferred from eMMC to UFS, so will smart cockpit memory chips. It is also possible for high-end models to adopt PCIe SSD.
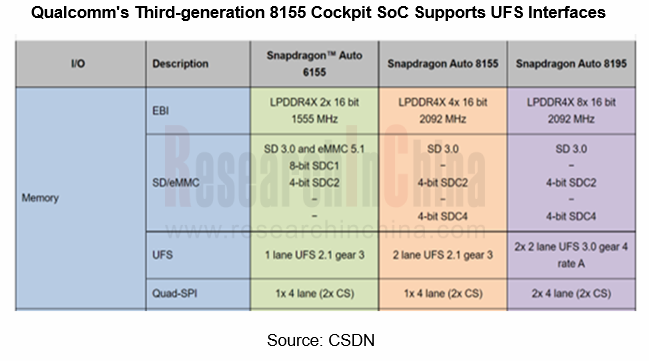
The cores of both UFS and eMMC interfaces involve NAND flash, but their control interfaces follow different protocols. The maximum communication rate of eMMC is 400MB/s, relative to 1,160 MB/s of UFS. The communication speed directly affects the startup time and software loading time of vehicles, which offer varying experience. In response to the demand for faster startup, reading and writing, the storage in the cockpit field must support UFS2.1 at least. Qualcomm's third-generation 8155 cockpit SoC has already endorsed UFS interfaces.
The intelligent cockpits of newly launched models demonstrate the increasingly powerful storage capacity:
?Xpeng P7 launched in 2020 is equipped with Qualcomm Snapdragon 820A with 8G memory + 128GB storage, enabling users to download more automotive Apps, supporting applet expansion, and featuring both practicality and fun;
?The next-generation SA8155P-based ZEEKR intelligent cockpit, available in ZEEKR 001 unveiled in 2021, has an 8-core CPU of the 7 nm process, with 16G memory and 128GB storage.
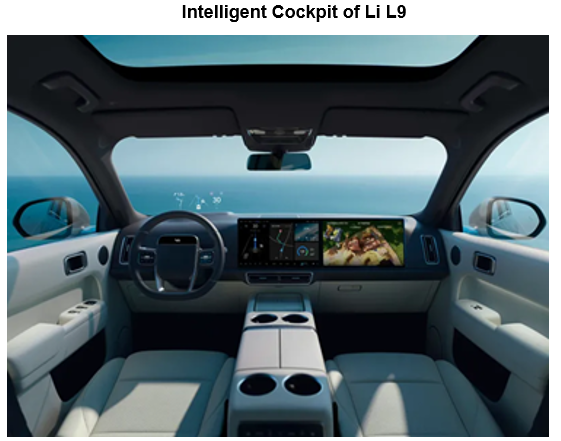
?Li L9 which debuted in 2022 comes standard with two Qualcomm Snapdragon 8155 chips with 24G memory and 256GB high-speed storage, which together form a powerful computing platform.
Chinese storage suppliers accelerate deployment in the promising automotive storage market
The requirements for automotive storage products are much higher than those for consumer electronics. Automotive-grade storage products have to take a long R&D and verification cycle, undergo a complicated certification process, comply with IATF16949, ASPCIE and ISO 26262, and satisfy the standards of some automakers, such as GMW3172 and VW80000. As a result, this market poses high barriers to entry and embodies obvious oligopoly.
Overseas storage vendors such as Micron, Samsung, SK Hynix and Microchip still dominate the development of the automotive storage industry as monopolists. Among them, Micron enjoys the global market share of over 45%. In 2021, Micron launched its industry-leading automotive LPDDR5 certified by ISO 26262 ASIL-D, with the maximum capacity of 128GB.
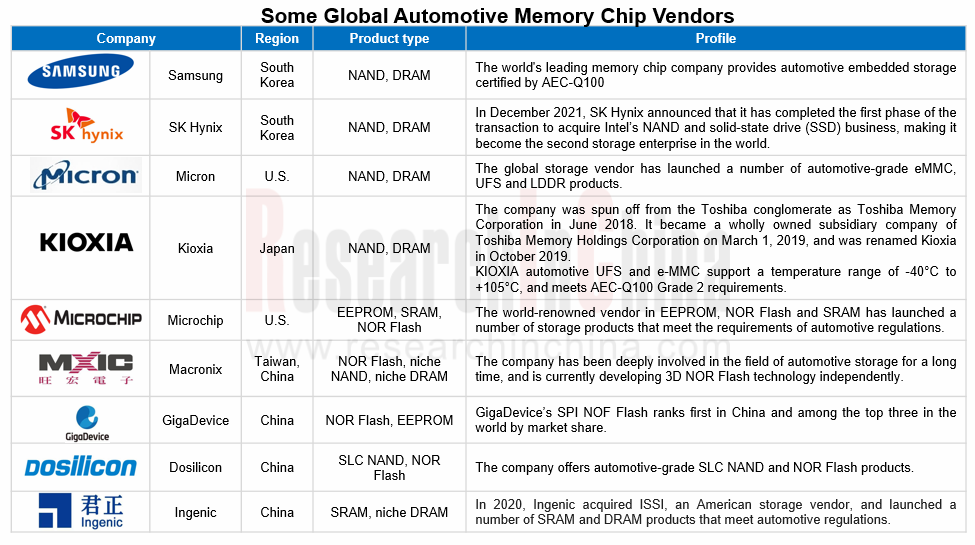
In recent years, Chinese memory chip vendors have made great efforts in automotive storage products:
SRAM: Ingenic has been focusing on independent CPU, SoC and AI engines for many years. In 2020, it acquired 100% stake in Beijing ISSI. By virtue of intellectual property rights, it can completely avoid the impact of the sanctions imposed by the United States government, independently develop and produce SRAM in line with automotive regulations, and produce niche DRAM. Ingenic has reached close cooperation with auto parts vendors such as Bosch and Continental.
EEPROM: Giantec Semiconductor, a leading EEPROM enterprise in China, launched GT24C512B, a high-reliability automotive A1-grade memory chip, in August 2022, which can withstand erasing and writing for up to 4 million times at room temperature, and has been applied to OBC, VCU and other related fields.
NOR Flash: GigaDevice has delved in the field of NOR Flash for many years. By market share, it ranks first in China and third in the world. The GD25 series launched by GigaDevice is the only mass-produced NOR Flash in China that meets AEC-Q100, with the storage capacity of 2Mb~2Gb.
In addition to OEMs, there is another type of storage players in China, like Longsys, BIWIN Storage Technology and Powe, who buy wafers and particles from IDMs and purchase master chips from third-party master chip vendors, then conduct packaging tests through their own or third-party packaging and testing factories, and produce storage products of different storage types, interfaces and standards.
Robot Manufacturers’ Device-Cloud Collaborative Hybrid Computing Deployment Solution Research Report, 2026
EAI Device-Edge-Cloud Collaboration Research: How to Deliver After Layering, Summary of the Ranking for 12 Robot Manufacturers
China’s shipments of humanoid robots are projected to reach 50,000 unit...
China Passenger Car HUD Industry Report, 2026
HUD Research: Installation Rate Exceeds 25% as Entry Price of P-HUD-Equipped Models Falls to RMB130,000
The China Passenger Car HUD Industry Report, 2026 released by ResearchInChina combs through HUD...
Passenger Car Electronic and Electrical Architecture (EEA) and Technology Supply Chain Construction Strategy Research Report, 2026-2027
Passenger Car EEA: The Next-Generation AI EEA Is Gaining Momentum, Enabling Vehicles to Achieve "Autonomous Perception - Autonomous Decision-Making - Autonomous Evolution"
Vehicle Architecture Is Ev...
Next-generation Central and Zonal Communication Network Topology and Chip Industry Research Report, 2026-2027
Research on Zonal Communication Topology: New Architectures Including 10 BASE-T1S+RCP, AVB/TSN Ethernet Are Under Rapid Development
Vehicle communication networks are mainly divided into in-vehicle n...
Software-Defined Vehicles in 2026: Software Supply Chain Panorama and Business Models Research
Research on Automotive Software Business Models: Exploration of Token Economy, AI Service Revenue Sharing and Other Businesses
Under the Trend of AI Agents: Exploration of Business Models Based on T...
New Energy Commercial Vehicle 800-1000V High-Voltage Platform & Supply Chain Panorama Research Report, 2026
Research on 800V Architecture of Commercial Vehicles: New Energy Penetration Rate Exceeds 35%, and 800V Full-Domain High-Voltage Architecture Rapidly Penetrates Heavy-Duty Trucks
Explosive Growth in ...
ADAS and Autonomous Driving Tier 1 Suppliers Research Report, 2026 – Chinese Companies
Intelligent Driving Industry Leap: From Widespread L2.9 Adoption toward Physical AI and New Full?Domain Mobility Ecosystem
As vehicle intelligence advances, the installations and penetration rate of...
Vehicle-Road-Cloud Integration and C-V2X Industry Report, 2026
Vehicle-Road-Cloud and C-V2X Research: with the three-tier promotion system of "top-level planning + mandatory pilot + evaluation binding", the industry turning point is approachingThis report focuses...
China OEM Data Capability Analysis Report, 2026
OEM Data Capability Research: 24 OEMs × 9 Capability Domains, Who Takes the Lead?
An L4 autonomous driving R&D and test vehicle can generate approximately 10TB of raw data per single day — data v...
Autonomous Driving Domain Controller and Central Computing Unit (CCU) Industry Report, 2026
Autonomous Driving Domain Controller (ADCU) Research: One-Chip CCU solutions are quickly available in vehicles
In China's passenger car market, autonomous driving systems involved in mass production ...
Automotive EMS and ECU Industry Research Report, 2026
Automotive EMS Research: The boundaries between EMS providers and Tier1 suppliers are becoming blurred, and the supply chain model is evolving from a linear chain to a networked structure
Mainstream ...
Automotive Microcontroller Unit (MCU) and Application Scenario Research Report, 2026
Automotive MCU Research: Increased demand for redundant security drives ASIL D-compliant MCU shipments to exceed 100 million units
In a vehicle EEA, MCUs are widely distributed in various functional ...
China Intelligent Cockpit Patent Analysis Report, 2026
Intelligent Cockpit Patent Research: Cockpit AI, In?vehicle Health, and Infotainment Are Upgrade to Scenario?based and Proactive Functions
From a patent perspective, this report explores the cutting?...
Research Report on Application of VLA Large Model in Automobiles and Robots, 2026
Research on Automotive and Robot VLA: Hybrid Architectures Become Mainstream, VLA Integrates with General World Models, and Reinforcement Learning Serves as Core Engine
Vision?Language?Action (VLA) m...
China Charging Infrastructure (Supercharging, Battery Swapping, V2G, etc.) and High-Performance Supercharging Battery Research Report, 2026
Charging and battery swapping research: as 5C+ supercharging vehicle models go into mass production, the pace of OEMs self-building supercharging networks quickens
800-1000V high-voltage platforms ar...
China Passenger Car Electronic Controlled Suspension Industry Report, 2026
Electronic Controlled Suspension Industry Research: As the First Year of Full Active Suspension Unfolds, Three Technical Routes Race Forward
1. Penetration Rate Surges Three Times, and Electronic Con...
Intelligent Driving SoC Research Report, 2026
Research on Intelligent Driving SoCs: Competition Focus Shifts to L3/L4 Embedded Hardware, and Computing Power of Flagship Vehicle Models Exceeds 1,000 TOPS
In terms of intelligent driving system in...
Automotive AI Large Model Technology Research Report, 2026
Automotive AI Large Model Research: Competition Shifts from "Who Has the Stronger Model" to "Who Boasts Higher Link Efficiency"
ResearchInChina released the Automotive AI Large Model Technology Resea...