Automotive electronics OEM/ODM/EMS research: amid the disruption in the division of labor mode in the supply chain, which auto parts will be covered by OEM/ODM/EMS mode?
Consumer electronic manufacturing service (EMS) providers are becoming important players in the automotive industry.
Due to the sluggish growth of the consumer electronics market, many consumer EMS providers have begun to tap the new automotive electronics (OEM) market. Top manufacturers such as Luxshare Precision, BOE, Lens Technology and Sunny Optical Technology have produced phased results.
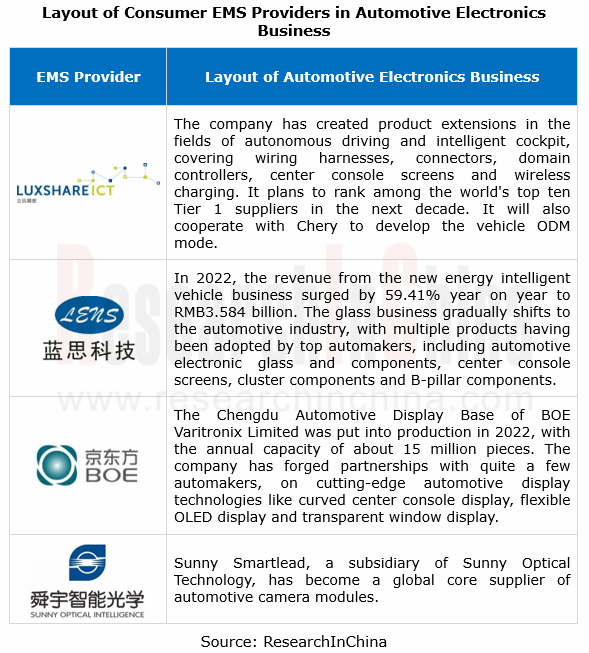
Besides acting as Tier 1 suppliers of automotive electronics, consumer EMS providers are also expanding the OEM business rapidly, for example:
Sunny Optical Technology manufactures LiDAR modules for Innovusion;
Cowell (Apple's main supplier of front camera modules), a subsidiary of Luxshare Precision, has secured a LiDAR OEM order from RoboSense. It participates in the design and manufacturing through joint design manufacturing (JDM) model. The LiDAR business become its second growth curve;
Luxshare Precision cooperates with Chery to develop the ODM model with actual projects scheduled to be carried out around 2024. It targets conventional foreign automakers and Chinese Smart EV brands.
As concerns automotive OEMs, emerging carmakers and conventional mainstream automakers are making continuous efforts on full-stack independent development. As they enjoy more autonomy in hardware design and definition and seek to develop differentiated and customized products, the problems such as long development cycle, high development cost, inflexible cooperation models, low openness and patent ownership stand out in conventional suppliers.
Vehicles become more like smartphones. Automotive OEMs not only want to define and master the system architectures and software algorithms of core products by themselves, but also hope to lead or participate in the design of hardware systems and outsource the manufacturing to automotive electronics companies, thereby deriving three models: OEM, ODM and EMS.
OEM (original equipment manufacturer) model: automakers design, and designate OEMs which manufacture according to the original designs and provide OEM services with materials supplied by the automakers;
ODM (original design manufacturer) model: upon the requirements of customers and their desired functions, ODMs take on all the links from product R&D to design, and then to production. Automakers that purchase their service only need to brand the finished products. As cross-border car manufacturing flourishes, the ODM model featuring "commissioned design and manufacturing or original design and manufacturing" has begun to prevail, for example, the cooperation between JAC and NIO, between Seres and Huawei, between Chery and Luxshare Precision;
EMS (electronics manufacturing services) model: this model originates from consumer electronics. Based on the ODM model, it also provides knowledge and management services, including logistics management, raw materials procurement, and after-sale services. In the automotive electronics market, EMS providers with certain advantages will not be easily replaced once they enter the supply chain of some automotive electronics customer.
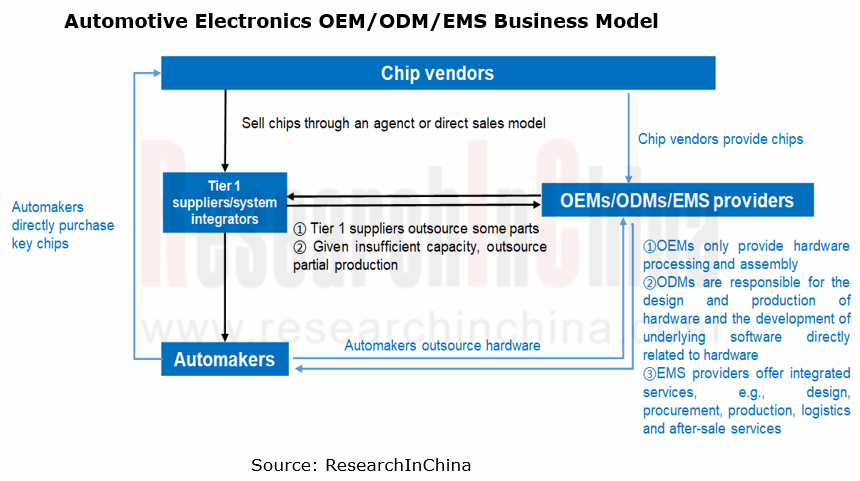
Automotive electronics OEM/ODM/EMS: hardware OEM/ODM/EMS companies are transforming into integrated hardware solution providers, and accelerating in-depth cooperation with OEMs.
In the automotive electronics industry, the arena of hardware OEM/ODM/EMS is attracting ever more conventional consumer electronics companies who prefer an entry from domain controllers, automotive communication modules, LiDAR, AR-HUD and other high-value-added intelligent products. For example, suppliers of Apple such as Quanta Computer, Wistron, Pegatron and Luxshare Precision race to embark on automotive electronics OEM/ODM/EMS.
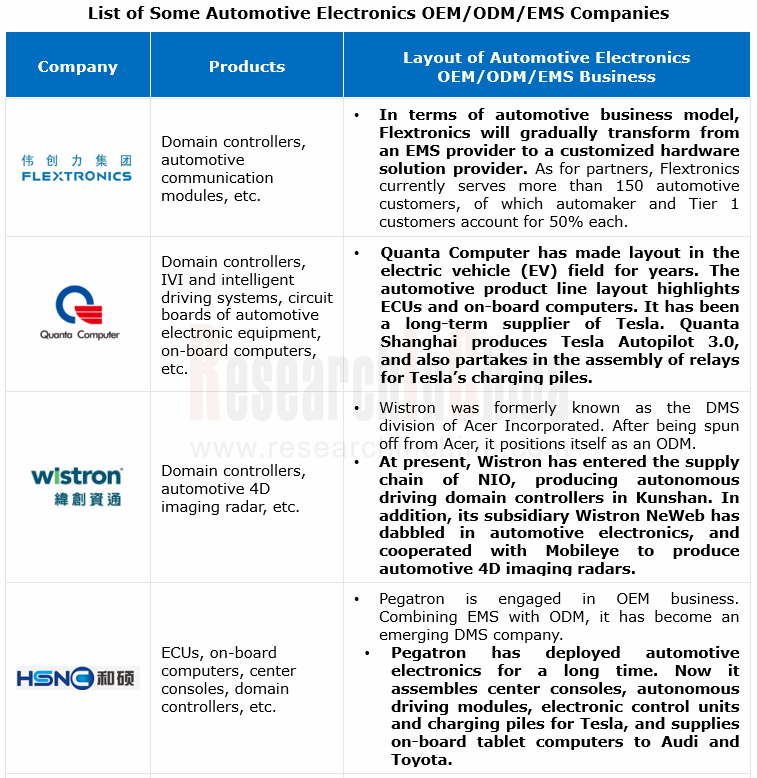
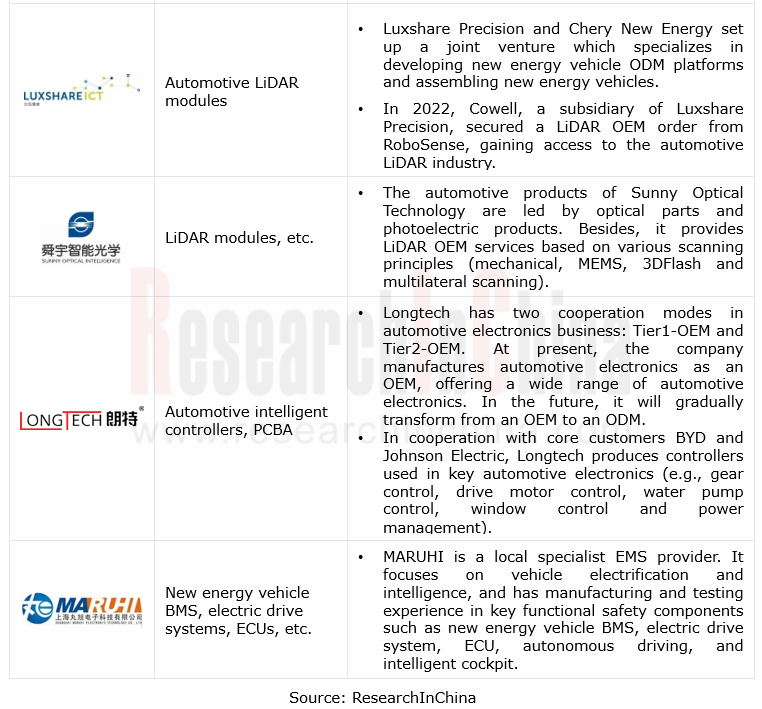
The OEM+EMS cooperation model is changing. Most obviously, ever more automakers become more willing to independently develop core products and technologies, especially high-added-value, highly differentiated know-how products. In this model, auto brands can concentrate more on personalized requirements, software and hardware the decoupling, and development of functional applications.
In Chinese market, Flextronics is gradually transforming from an EMS provider to a customized hardware solution provider. Flextronics implements the "Local-to-Local" strategy and the "Assistant Development Manufacturing (ADM)" business model. The ADM model enables automakers to partner with Flextronics at any point in the product life cycle, so as to fill the gap in the product development process. Flextronics’ ADM model allows for more flexibility in OEMs’ product design.
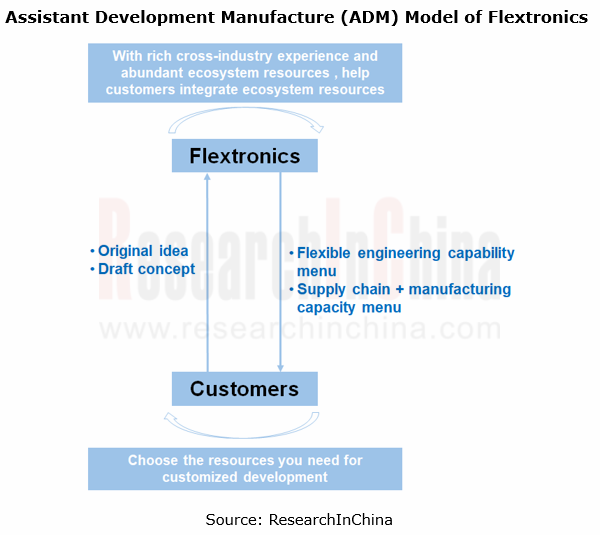
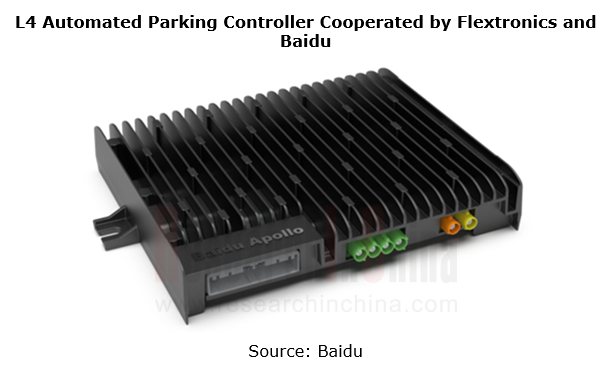
Based on the ADM model, Flextronics collaborated with Baidu Apollo to mass-produce the Apollo Computing Unit (ACU). In the cooperation, Flextronics provides Baidu with customized product development and design, testing and verification, as well as supply chain integration and optimization, production line design and large-scale manufacturing, according to advices and architecture requirements of Baidu Apollo experts.
Amid the evolution of E/E architectures, the boundary between PCs and vehicles will gradually vanish in the zonal era.
Under the zonal and central computing architecture, a vehicle computing system will be like a PC, that is, all operations will be completed by a CPU, and all applications will be executed by the CPU, perhaps together with a GPU/AI accelerator. Peripherals, interfaces and underlying software system are fixed. The underlying system is almost completely transparent to programmers who only need to develop specific applications. As with today's PCs based on Windows+CPU, software-defined vehicles can be realized.
Against this backdrop, vehicles will embody a high division of labor in the supply chain, just like smartphones and Pcs. Both OEMs and chip vendors will gain a far higher existence and even begin to replace conventional Tier1 suppliers.
As a result, automotive electronics OEMs are building close partnerships with automakers in more aspects:
Flextronics: in April 2023, Flextronics leveraged Horizon Journey 5 and a turnkey solution to produce customized L2+ central domain controllers for Chinese automakers.
In addition, Flextronics has forged a 6-year partnership with Li Auto, covering such products as dome lights, ambient lights, autonomous driving controllers, cockpit entertainment domain, and central computing units.
Foxconn: based on NVIDIA's turnkey solution "Hyperion AV", Foxconn will directly customize domain controllers and central computing platforms for automakers.
Lenovo Group: based on the new-generation NVIDIA DRIVE Thor SoC, Lenovo will independently develop its next-generation automotive domain controller platforms. In the future, the domain controller platform architecture based on DRIVE Thor will become Lenovo’s high-end core product line for on-board computing, and related products are expected to be mass-produced in early 2025.
Car making by ODMs: the model of "technical architecture licensing by automakers" and "car making by ODMs" will bring new revolutionary opportunities for the global automotive industry.
In the era of feature phones, mobile phone vendors like Motorola and Nokia all built their own factories. After the advent of smartphones, Apple, Xiaomi and Huawei among others have turned into large ODMs. Phone brands’ more concentration on product development and design provides a big boost to the development of mobile phone industry chain. How to transplant the smartphone model into the automotive industry has already been a spotlight.
Automotive OEM/ODM/EMS is nothing new in the automotive industry. Magna, a global OEM giant, has designed and mass-produced about 30 vehicle models for several automakers, including BMW X3, Mercedes-Benz G, and models of Toyota and Jaguar, with the total production higher than 3.7 million units. In China, the collaborations between NIO and JAC, or between Seres and Huawei have seen initial results. Yet there are no successful cases where consumer electronics companies as ODMs spawn vehicles, so that the layout made by bellwethers such as Foxconn and Luxshare Precision has drawn much attention from the market.
Foxconn’s CDMS (contract design and manufacturing service) business model is that Foxconn becomes a CDMS provider for the automotive industry. Simply put, Foxconn and Yulon together launched the MIH modular EV platform to provide OEM services for automakers with limited production capacity or outsourcing needs.
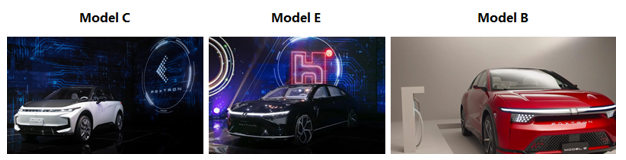
Foxconn has introduced a number of electric vehicles based on the MIH platform, such as Model C, Model B and Model E.
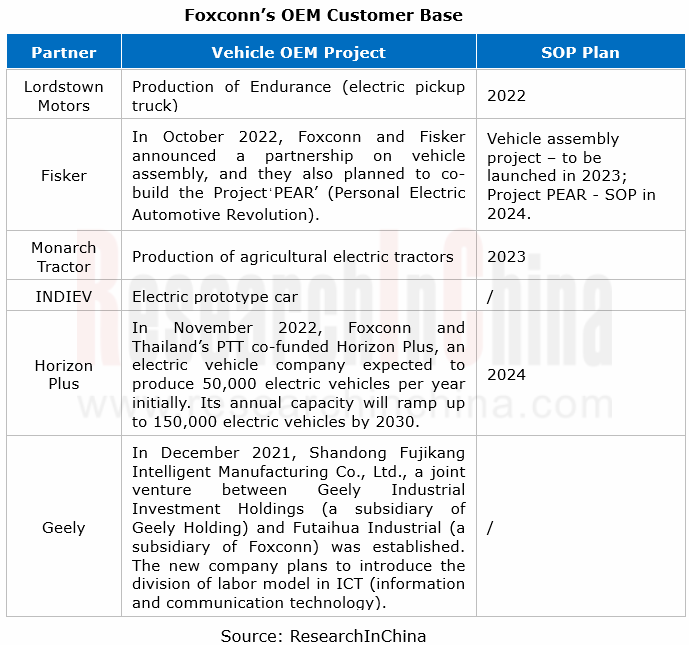
Up to now, Foxconn however has mainly served overseas start-ups like Lordstown Motors, Monarch Tractor and INDIEV, without benchmarking customers, mainstream customers or those placing massive orders.
From the perspective of automakers, based on the Sustainable Experience Architecture (SEA) platform, a modular electric vehicle platform Geely invested RMB18 billion to build in 4 years, ZEEKR has achieved phased results. Geely has opened the "SEA" platform license to the global. The architecture will be available to "Jidu Auto" (a brand owned by Geely and Baidu), "IZERA" (a brand in the cooperation between Geely and Poland-based EMP), Waymo One’s autonomous fleet (SEA-M Intelligent Platform), and Volvo Polestar 4/5. The ODM model may support the technical architecture export of automakers.
In the age of BEVs and intelligence, the concept of modular platform-based car making plays a more important role. The goal of the cooperation between Geely and Foxconn, or between Chery and Luxshare Precision is to export the "vehicle platform technical architecture".
It is believed that the model of "technical architecture licensing by automakers" and "car making by ODMs" may bring an opportunity to the global automotive industry for a disruption in the next stage.
China Intelligent Cockpit Patent Analysis Report, 2026
Intelligent Cockpit Patent Research: Cockpit AI, In?vehicle Health, and Infotainment Are Upgrade to Scenario?based and Proactive Functions
From a patent perspective, this report explores the cutting?...
Research Report on Application of VLA Large Model in Automobiles and Robots, 2026
Research on Automotive and Robot VLA: Hybrid Architectures Become Mainstream, VLA Integrates with General World Models, and Reinforcement Learning Serves as Core Engine
Vision?Language?Action (VLA) m...
China Charging Infrastructure (Supercharging, Battery Swapping, V2G, etc.) and High-Performance Supercharging Battery Research Report, 2026
Charging and battery swapping research: as 5C+ supercharging vehicle models go into mass production, the pace of OEMs self-building supercharging networks quickens
800-1000V high-voltage platforms ar...
China Passenger Car Electronic Controlled Suspension Industry Report, 2026
Electronic Controlled Suspension Industry Research: As the First Year of Full Active Suspension Unfolds, Three Technical Routes Race Forward
1. Penetration Rate Surges Three Times, and Electronic Con...
Intelligent Driving SoC Research Report, 2026
Research on Intelligent Driving SoCs: Competition Focus Shifts to L3/L4 Embedded Hardware, and Computing Power of Flagship Vehicle Models Exceeds 1,000 TOPS
In terms of intelligent driving system in...
Automotive AI Large Model Technology Research Report, 2026
Automotive AI Large Model Research: Competition Shifts from "Who Has the Stronger Model" to "Who Boasts Higher Link Efficiency"
ResearchInChina released the Automotive AI Large Model Technology Resea...
Intelligent Vehicle Cockpit Domain Controller Research Report, 2026
Cockpit domain controller research: L3 AIDV intelligent cockpit domain controllers are entering a boom period
Driven by multiple factors such as the continuous evolution of the automotive central int...
Automotive Acoustic System (Audio, Multi-Channel) Industry Report, 2026
Automotive Acoustics Research: Multiple Channels, AI Tuning, and Self-Developed Algorithms Drive the Transformation of High-End Cockpit Sound Fields
I. Automotive Audio Hardware Solutions with 6–9 S...
Autonomous Driving Sensor Chip Research Report, 2026
Research on Autonomous Driving Sensor Chips: Deeply Perceiving the Physical World, Sensor Chips Are Playing A “Leading Role” in Intelligence
In 2026, the autonomous driving sensor chip industr...
Passenger Car Corner Module and Wheel‑Side Control System Research Report, 2026
Wheel-side control research: the “last mile” chassis innovation
Wheel-side control dismantles the traditional drive, braking, steering, and suspension control of the chassis from a "centralized" styl...
Embodied Artificial Intelligence (& Humanoid Robot) MCU Research Report, 2026
Research on Humanoid Robot MCUs: Evolution from General-Purpose Control to High-Value Dedicated Chip Solutions Integrated with Edge AI Functions
MCU (Microcontroller Unit) refers to a compact integra...
Intelligent Vehicle Zone Control Unit (ZCU) Research Report, 2026
ZCU Research: Cross-domain integrated ZCUs are becoming the edge computing nodes of the next-generation zonal architecture
Currently, the mainstream zonal architecture is mainly the quasi-central + z...
Automotive Cybersecurity and Data Security Research Report, 2026
Cybersecurity & Data Security Research: Intelligent Connected Vehicles Enter the Era of “Systematic Offense-Defense and AI-Defined Security”.
Centering on the panorama of intelligent connect...
Report on Breakthrough Strategies of OEMs and ADAS Tier 1 Suppliers for Overseas Layout of Intelligent Driving, 2026
Regulatory Breakthrough, Local System Establishment, OEMs Competing for NOA Layout: Overall Trends of China’s Intelligent Driving Overseas Layout in 2026
Research on overseas intelligent driving layo...
OEMs and Tier1s’ Intelligent Cockpit Platform (Hardware and Software) Innovation Strategy Research Report, 2026
Intelligent Cockpit Platform Research: multi-dimensional cockpit system architecture reconstruction for multi-agent collaboration and proactive intelligent services
The intelligent cockpit software s...
Automotive AIOS Research Report, 2026
Automotive AIOS Research: Mass Production Solutions Are Implemented
Mass Production Solutions Are Implemented on A Small Scale.
In 2026, AIOS starts small-scale implementation, helping to improve v...
Automotive Telematics Service Provider (TSP) Research Report, 2026
TSP Research: Leading providers collectively turn to AI agents to provide all-scenario active services
Telematics Service Providers (TSPs) are the core hub of the telematics industry chain, connectin...
Automotive Smart Interior Research Report, 2026
Smart Interior Research: As Technologies like Interactive Starlight Headliner, Hidden Display and Surface Projection Are Launched, Automotive Interiors Become Ever More Intelligent
The Automotive Sma...