Solid state battery research: semi-solid state battery has come out, is all-solid state battery still far away?
In recent years, the new energy vehicle market has been booming, and the penetration of new energy vehicles has sustained steady growth. From January to April 2023, the production and sales of new energy vehicles in China reached 2.291 million units and 2.222 million units, respectively, both jumping by 42.8% on a like-on-like basis, with a market share of 27%. With rising sales, new energy vehicles demand ever more power batteries. It is estimated that the global electric vehicle battery usage is expected to reach approximately 749GWh in 2023.
In the era when the installation of power batteries in vehicles approaches TWh, suppliers step up production of solid-state batteries with higher energy density, driven by favorable policies and market demand.
In China, the "New Energy Vehicle Industry Development Plan (2021-2035)" issued by the General Office of the State Council on November 2, 2020 specifies that the R&D and industrialization of solid-state power battery technologies should be accelerated, and the R&D of solid-state batteries is raised to the national level for the first time. China's power battery industrialization goal is that in 2025, the energy density of liquid battery cells will reach 350Wh/kg; in 2030, the energy density of solid-liquid hybrid battery cells will be 400Wh/kg; in 2035, the energy density of quasi/all-solid-state battery cells will reach 500Wh/kg.
Meanwhile, Japan, South Korea, Europe and the US have also introduced incentive policies to develop solid-state batteries. For example, the US released the National Blueprint for Lithium Batteries 2021-2030 in 2021; Europe issued the Battery 2030+ and the Battery Innovation Roadmap 2030; most Japanese and Korean companies team up to develop, and automakers, scientific research institutions, and battery and materials companies divide labor clearly and are keen on cooperative development of solid-state battery technology.
1. Compared with the current mainstream liquid batteries, solid-state batteries have begun to get a foothold by virtue of bringing quite a few benefits.
Compared with liquid lithium batteries, solid-state batteries use solid electrodes and solid state electrolytes. In theory their energy density can reach up to 400-500Wh/kg, which is 2 to 3 times that of liquid lithium batteries. Solid-state batteries offers the benefits of cruising range increase, much lower thermal runaway risk, shorter charging time, longer cycle life, and smaller size. It is particularly worth noting that lithium metal anodes can increase the energy density of batteries by more than 70%.
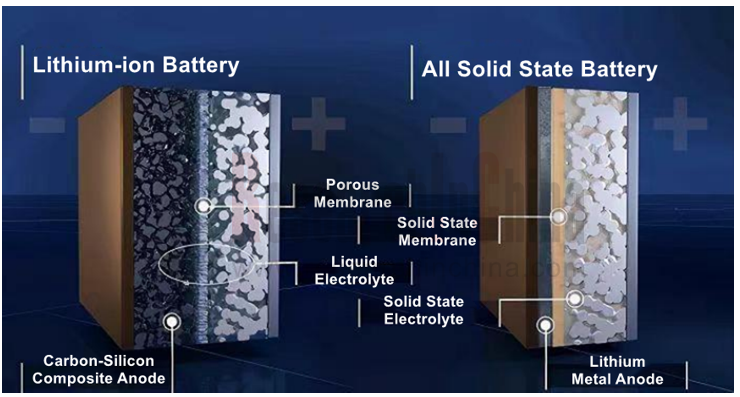
On this basis, ever more companies double down on R&D and production of solid-state batteries. Among power battery companies, CATL, Gotion Hi-Tech, Ganfeng Lithium, EVE Energy and Sunwoda are working hard on layout of solid-state battery technology. Yet for the moment the volume production of semi-solid state batteries will start earlier.
2. With increasing energy density of batteries, semi-solid state battery prototypes begin to be used in vehicles.
As a transitional route, semi-solid state batteries can improve safety performance, because the reduction of electrolytes lowers the thermal runaway risk caused by external heating and shock and internal short circuits. The electrolyte content in semi-solid state batteries is about 10% or below (the electrolyte mass of conventional lithium batteries makes up about 20%), and the soft package + laminated packaging process is used commonly. In terms of system, semi-solid state batteries can follow the 811 system, or adapt to more radical chemical systems such as the group 9, offering improvements in both energy density and comprehensive cost.
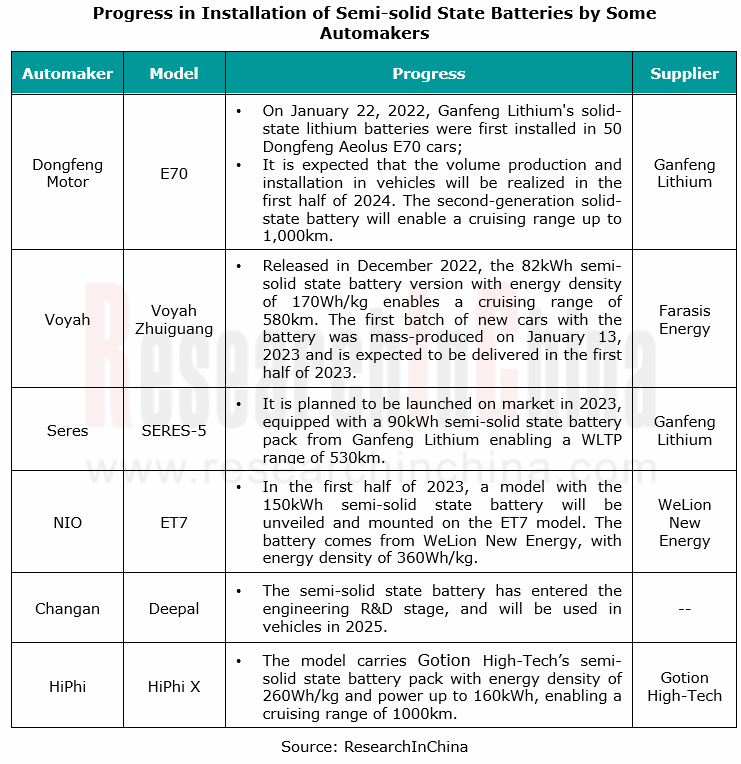
On January 22, 2022, E70, the demonstration operating car carrying the Dongfeng-Ganfeng high specific energy solid-state battery jointly developed by Dongfeng Motor and Ganfeng Lithium, made its world debut in Xinyu City, Jiangxi Province. Since then, the trial use of solid-state battery prototypes in vehicles has been kicked off.
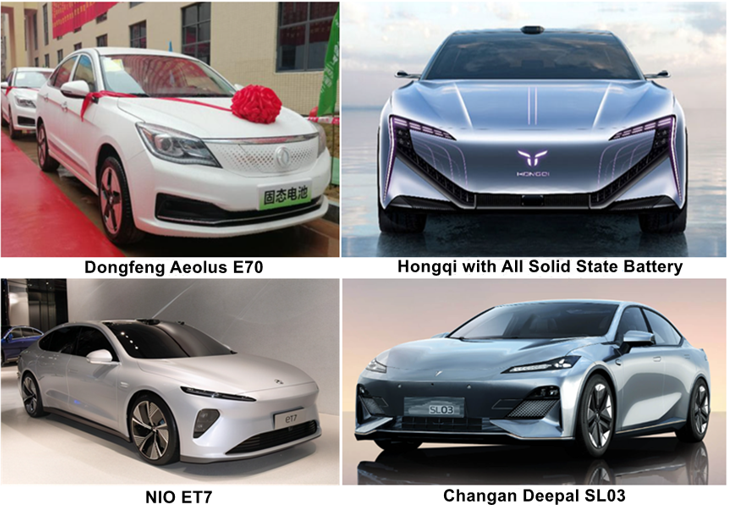
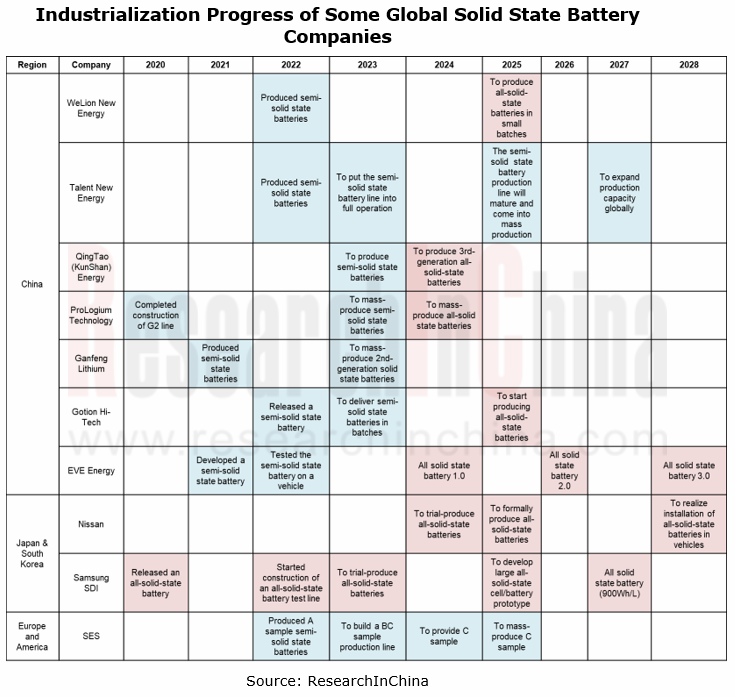
At present, companies that can mass-produce semi-solid state batteries include Beijing WeLion New Energy Technology, QingTao (KunShan) Energy Development, Talent New Energy, ProLogium Technology, Ganfeng Lithium, Gotion Hi-Tech, and EVE Energy.
Among them, WeLion New Energy's first semi-solid state battery was rolled off the production line in November 2022, with energy density of 360Wh/kg; Talent New Energy put into production China’s first semi-solid state battery production line in October 2022, a facility expected to come into full operation in July 2023, with planned annual capacity up to 10GWh during 2023-2024 and 26GWh during 2024-2026; in April 2023, QingTao (KunShan) Energy Development's first production line with designed capacity of 1GWh became operational, with the first batch of semi-solid state batteries rolled off the line in the Pidu Factory.
3. All-solid-state batteries are expected to be mass-produced around 2024.
The mass production of all-solid-state batteries are expected to start around 2024. Major companies include Nissan, Samsung SDI, and Montavista Energy Technologies.
From the solid-state battery production line layout, it can be seen that foreign companies start earlier, for example:
Solid Power brought into operation a continuous process pilot production line in Louisville, Colorado in 2019; produced 320Wh/kg 20Ah lithium metal batteries in 2020; announced the addition of a second Denver-area production facility in Thornton, Colorado in 2021; on June 6, 2022, announced that it has completed the installation of its pilot production line designed to produce electric vehicle batteries, aiming to accelerate the production of automotive solid-state batteries. In January 2023, BMW and Solid Power started the next-stage joint R&D of all-solid-state batteries. Solid Power licenses cell design and manufacturing processes to the BMW Group to help it build a pilot line in Munich. The first prototype vehicle will be launched before 2025, and the all-solid-state batteries will be produced in quantities in 2030.
In March 2022, Samsung SDI announced that it started the launch of the pilot line (S-line) for manufacturing solid-state batteries at SDI R&D Center located in Yeongtong-gu, Suwon-si, Gyeonggi-do. The facility will start trial production in 2023 and achieve large-scale production in 2027.
Among foreign OEMs, in 2024 Nissan will start a pilot plant in Yokohama, Japan and set up an all-solid-state battery production line; it will produce all-solid-state batteries in 2025 and see them installed into vehicles in 2028. Toyota will produce all-solid-state batteries on small scale and first use them in HEV models before 2025; it will achieve continuous and stable production of all-solid-state batteries before 2030.
Most Chinese companies take a production route gradually from semi-solid to all-solid state batteries. The companies that quickly realize the production of all-solid-state batteries are led by GTC-Power, Beijing WeLion New Energy Technology, QingTao (KunShan) Energy Development, ProLogium Technology, Gotion Hi-Tech and EVE Energy.
For example, EVE Energy will iterate its all-solid-state battery technology in three phases, and will concentrate on the oxide, sulfide and halide R&D routes. The company plans to complete the R&D of the all-solid-state battery technology 1.0 in 2024, with energy density of 350Wh/kg and cycle life more than 300 times; iterate its all-solid-state battery technology to 3.0 in 2028, which features high safety, high flexibility and high temperature resistance to meet the requirements of power batteries, with energy density increased to 550Wh/kg and cycle life up to over 1,000 times.
On December 21, 2021, the Japanese laboratory of GTC-Power successfully developed a 1.5Ah all-solid-state lithium battery sample, which heralds GTC-Power’s entry into the fast lane in R&D of all-solid-state lithium batteries. Its all-solid-state power battery has passed the acupuncture and 350°C thermal runaway tests, with energy density greater than 400Wh/kg and cycle life more than 1,200 times, and it can still work at -40°C-150°C.
4. What are the constraints on the industrialization of solid-state batteries?
At present, solid-state batteries still have such problems as high interfacial impedance between the solid-state electrolyte and the electrode, and relatively low bulk ionic conductivity of the solid-state electrolyte. The solutions to the high interfacial impedance and low conductivity are the key to the industrialization of solid-state lithium batteries.
Solutions:
① Ultrathin electrolyte is one of the effective ways to reduce interfacial impedance in the industry. For example, Talent New Energy’s research institute and its Chongqing manufacturing base have developed electrolyte ultra-thin film preparation technology and interface softening technology using innovative processes and new customized equipment, and its process system compatible with the existing liquid batteries can go into production quickly.
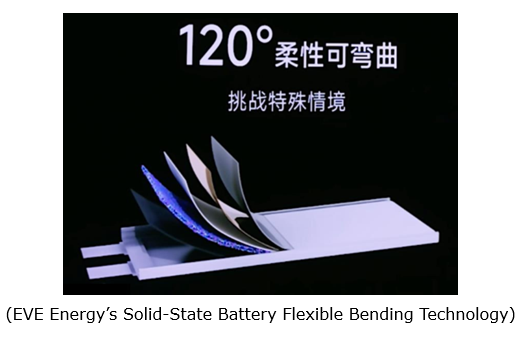
② The solid-state battery interface softening technology is also an effective solution to lower interfacial impedance. For example, the existing halide-based all-solid-state thin-film pouch battery technology of EVE Energy can adapt to special high temperature and bending conditions, and allows for stable discharging in the high temperature zone of 150°C by combining high nickel anodes. The softening technology enables normal battery charge and discharge even in the condition of 120 ° bending.
③ Among the three major electrolyte systems (polymer, oxide and sulfide), the sulfides are soft and flexible and feature the highest ionic conductivity, up to the level of liquid electrolyte (10-2 S/cm), breaking the conductivity bottleneck of solid state electrolytes. Yet sulfides with high resistance are easy to have side reactions with air, water, etc., posing many process challenges. Typical companies taking the sulfide route include GTC-Power, Enpower Greentech, CATL, Toyota, Honda, Samsung, and Solid Power.
Nevertheless, oxide solid state electrolyte is currently at the forefront in terms of industrial application and production nodes. With both electrical conductivity and stability, oxides are relatively easy to spawn and thus develop rapidly. Typical companies that choose the oxide system include WeLion New Energy, QingTao (KunShan) Energy, ProLogium Technology, Gotion Hi-Tech, Farasis Energy and Ganfeng Lithium.
In addition to the abovementioned, the varying production processes and the purchase of new equipment have also slowed down the production to a certain extent. At present, semi-solid state batteries can be basically compatible with liquid battery production lines, at almost flat cost. Amid a gradual transition to the production of all-solid-state batteries, because of very different processes and production procedures, a large number of new process equipment like isostatic pressing equipment need to be purchased. Isostatic pressing equipment is difficult to produce, debug and use, and also needs a lot of know-hows and experience to attain the efficiency and yield of lithium battery rolling and hot pressing processes, which undoubtedly places some pressure on the industrialization of solid-state batteries.
Finally, relevant manufacturers also need to continuously optimize their production line equipment and production processes to improve the yield of battery cell packaging and increase sales. This is also one of the key factors to realize the virtuous circle of the solid-state battery industry.
Robot Manufacturers’ Device-Cloud Collaborative Hybrid Computing Deployment Solution Research Report, 2026
EAI Device-Edge-Cloud Collaboration Research: How to Deliver After Layering, Summary of the Ranking for 12 Robot Manufacturers
China’s shipments of humanoid robots are projected to reach 50,000 unit...
China Passenger Car HUD Industry Report, 2026
HUD Research: Installation Rate Exceeds 25% as Entry Price of P-HUD-Equipped Models Falls to RMB130,000
The China Passenger Car HUD Industry Report, 2026 released by ResearchInChina combs through HUD...
Passenger Car Electronic and Electrical Architecture (EEA) and Technology Supply Chain Construction Strategy Research Report, 2026-2027
Passenger Car EEA: The Next-Generation AI EEA Is Gaining Momentum, Enabling Vehicles to Achieve "Autonomous Perception - Autonomous Decision-Making - Autonomous Evolution"
Vehicle Architecture Is Ev...
Next-generation Central and Zonal Communication Network Topology and Chip Industry Research Report, 2026-2027
Research on Zonal Communication Topology: New Architectures Including 10 BASE-T1S+RCP, AVB/TSN Ethernet Are Under Rapid Development
Vehicle communication networks are mainly divided into in-vehicle n...
Software-Defined Vehicles in 2026: Software Supply Chain Panorama and Business Models Research
Research on Automotive Software Business Models: Exploration of Token Economy, AI Service Revenue Sharing and Other Businesses
Under the Trend of AI Agents: Exploration of Business Models Based on T...
New Energy Commercial Vehicle 800-1000V High-Voltage Platform & Supply Chain Panorama Research Report, 2026
Research on 800V Architecture of Commercial Vehicles: New Energy Penetration Rate Exceeds 35%, and 800V Full-Domain High-Voltage Architecture Rapidly Penetrates Heavy-Duty Trucks
Explosive Growth in ...
ADAS and Autonomous Driving Tier 1 Suppliers Research Report, 2026 – Chinese Companies
Intelligent Driving Industry Leap: From Widespread L2.9 Adoption toward Physical AI and New Full?Domain Mobility Ecosystem
As vehicle intelligence advances, the installations and penetration rate of...
Vehicle-Road-Cloud Integration and C-V2X Industry Report, 2026
Vehicle-Road-Cloud and C-V2X Research: with the three-tier promotion system of "top-level planning + mandatory pilot + evaluation binding", the industry turning point is approachingThis report focuses...
China OEM Data Capability Analysis Report, 2026
OEM Data Capability Research: 24 OEMs × 9 Capability Domains, Who Takes the Lead?
An L4 autonomous driving R&D and test vehicle can generate approximately 10TB of raw data per single day — data v...
Autonomous Driving Domain Controller and Central Computing Unit (CCU) Industry Report, 2026
Autonomous Driving Domain Controller (ADCU) Research: One-Chip CCU solutions are quickly available in vehicles
In China's passenger car market, autonomous driving systems involved in mass production ...
Automotive EMS and ECU Industry Research Report, 2026
Automotive EMS Research: The boundaries between EMS providers and Tier1 suppliers are becoming blurred, and the supply chain model is evolving from a linear chain to a networked structure
Mainstream ...
Automotive Microcontroller Unit (MCU) and Application Scenario Research Report, 2026
Automotive MCU Research: Increased demand for redundant security drives ASIL D-compliant MCU shipments to exceed 100 million units
In a vehicle EEA, MCUs are widely distributed in various functional ...
China Intelligent Cockpit Patent Analysis Report, 2026
Intelligent Cockpit Patent Research: Cockpit AI, In?vehicle Health, and Infotainment Are Upgrade to Scenario?based and Proactive Functions
From a patent perspective, this report explores the cutting?...
Research Report on Application of VLA Large Model in Automobiles and Robots, 2026
Research on Automotive and Robot VLA: Hybrid Architectures Become Mainstream, VLA Integrates with General World Models, and Reinforcement Learning Serves as Core Engine
Vision?Language?Action (VLA) m...
China Charging Infrastructure (Supercharging, Battery Swapping, V2G, etc.) and High-Performance Supercharging Battery Research Report, 2026
Charging and battery swapping research: as 5C+ supercharging vehicle models go into mass production, the pace of OEMs self-building supercharging networks quickens
800-1000V high-voltage platforms ar...
China Passenger Car Electronic Controlled Suspension Industry Report, 2026
Electronic Controlled Suspension Industry Research: As the First Year of Full Active Suspension Unfolds, Three Technical Routes Race Forward
1. Penetration Rate Surges Three Times, and Electronic Con...
Intelligent Driving SoC Research Report, 2026
Research on Intelligent Driving SoCs: Competition Focus Shifts to L3/L4 Embedded Hardware, and Computing Power of Flagship Vehicle Models Exceeds 1,000 TOPS
In terms of intelligent driving system in...
Automotive AI Large Model Technology Research Report, 2026
Automotive AI Large Model Research: Competition Shifts from "Who Has the Stronger Model" to "Who Boasts Higher Link Efficiency"
ResearchInChina released the Automotive AI Large Model Technology Resea...