1. Automotive lens companies: "camera module segment + emerging suppliers" facilitates the rise of Chinese products.
In 2023, automotive lens companies still maintain a three-echelon pattern. The first echelon is led by Sunny Optical, whose lens products still prevail in the industry in terms of sales and technical strength, and are expected to still take a 40% market share in 2023; the second echelon covers Lianchuang Electronic (China), OFILM (China), Trace Optical (China), Guangzhou Jinghua Precision Optics (China), Sekonix (South Korea), Nidec (Japan), and Maxell (Japan), with market shares ranging from 5% to 10%; the third-echelon players include Phenix Optics and Largan Precision.
In 2023, Chinese automotive lens companies keep extending to the downstream of the industry chain. Among them, Sunny Smartlead (a module factory of Sunny Optical), Lianchuang Electronic, OFILM, and Guangzhou Jinghua Precision Optics have successfully transformed themselves from Tier2s into Tier1s, and mainly partner with Chinese emerging carmakers. Their Japanese and Korean peers such as Maxell, Nidec Sankyo, and Sekonix still specialize in lens products and supply to Tier1s and conventional OEMs.
Despite still big market shares, Japanese and Korean companies are thus facing the impact from Chinese suppliers that gain more competitive edges by way of "emerging suppliers + expansion in the camera module segment".
Sunny Optical shipped 79.316 million automotive lenses from January to October 2023, a 19.1% jump compared with the same period in 2022, with automotive camera module shipments estimated to reach 8 million units. With regard to module mass production, major customers include Li Auto, Xpeng, Mazda, Toyota, Great Wall, SAIC, Geely and ZEEKR.
Lianchuang Electronic was expected to ship 9 million automotive lenses from January to October 2023, surging by over 30% on a like-on-like basis, with automotive camera module shipments estimated to reach 3 to 4 million units. In terms of camera modules, Lianchuang Electronic’s automotive optics business has started deploying automotive camera modules since 2021, and develops in cooperation with NIO and BYD. At present, Lianchuang Electronic’s automotive camera module products have covered front view, surround view, rear view, DMS and other fields. As for volume production, Lianchuang Electronic is a key supplier of 8M ADAS automotive image modules for NIO's new-generation platforms, which have been available to NIO ET7 and ET5 in 2022 and have been designated by BYD and Leapmotor among other automakers.
In the first ten months of 2023, by one estimate OFILM shipped 8.5 million automotive lenses, an increase of over 15% from the prior-year period, and 5 million camera modules, up by 10%. In terms of camera modules, OFILM established Shanghai OFILM Intelligent Vehicle Connected Technology Co., Ltd. in 2015, specializing in deploying intelligent driving products like vehicle camera modules. At present, OFILM's vehicle camera module products have covered front view (mono/multi-camera), side view, CMS, surround view, rear view, DMS, OMS and other fields.
2. The automotive CMOS image sensor (CIS) market is dominated by the trio, followed by Samsung and SmartSens.
In current stage the automotive CIS market is still led by the three bellwethers, namely, ON Semiconductor, OmniVision, and Sony.
In 2022, ON Semiconductor took the biggest share in the global automotive CIS market, about 40%; OmniVision followed with a share of about 25%-30%; Sony was positioned third with about 12%-15%.
Samsung followed them, with a share of about 5%-7% in 2022. In addition to cooperating with Hyundai Mobis, as a preferred supplier of Korean automakers Samsung also jumped on Tesla's train in 2022 and became a CIS supplier (supplying ISOCELL Auto 4AC) for several Tesla models, so it boasted a much bigger share in the market.
Except OmniVision China, Chinese companies capable of large-scale supply include SmartSens, BYD Semiconductor and GalaxyCore. Founded in 2017 and headquartered in Shanghai, SmartSens has automotive CIS products covering front view (8M), surround/rear view (1M-2M) and cockpit (3M-5M), which have been spawned for projects of automakers like BYD, FAW, SAIC, Dongfeng Nissan, Great Wall, Leapmotor and Voyah, with a global market share of approximately 3%-5%.
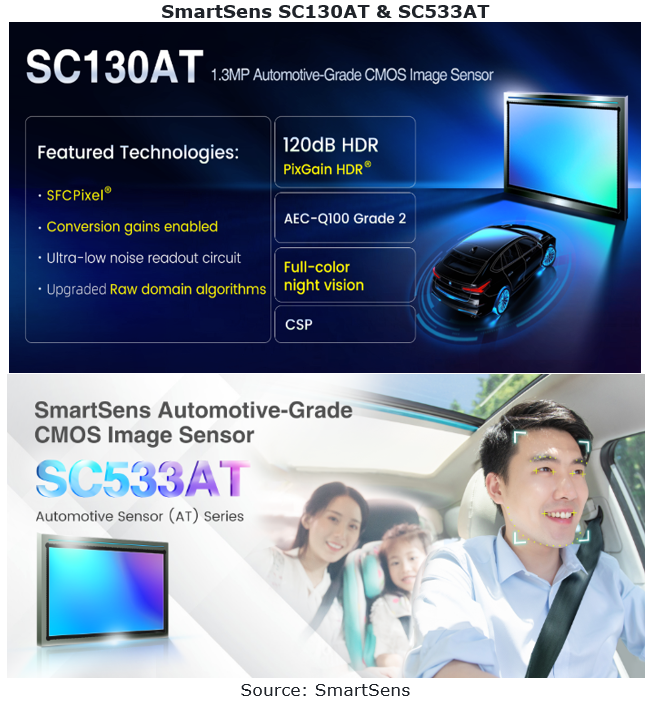
SmartSens’ new products released in 2023 include SC130AT (released in June 2023) and SC533AT (released in August 2023), which are expected to be mass-produced in Q4 2023.
SC130AT samples have been sent to customers. It is projected to come into mass production in Q4 2023. It features 1.3M (1304Hx984V) resolution, 120dB HDR, BSI, Rolling Shutter, frame rate of 30fps, pixel size of 3.75μm, and 1/3-inch optical format;
SC533AT samples have been sent to customers. It is projected to come into mass production in Q4 2023. It features 5.3M (2592Hx1944V) resolution, RGB-IR, BSI, Global Shutter, parasitic light sensitivity (PLS) 20000, frame rate of 60fps, pixel size of 2.2μm, and 1/2.53-inch optical format.
GalaxyCore, founded in 2003 and headquartered in Shanghai, concentrates efforts on layout in the aftermarket. Its products are largely used in driving recorders, reversing cameras, 360-degree surround view, rear view, etc. In the first half of 2023, GalaxyCore sold more than RMB100 million, or around 5.1% of its total revenue, in the aftermarket.
3. Automotive CIS resolution: take a giant leap forward from 8M to 17.4M.
At present, the resolution of mainstream automotive ADAS CISs has developed to 8M (typical products include ON Semiconductor AR0820AT and Sony IMX424). The detection range of 8M cameras is more than twice that of 1.2M cameras. It is expected that the detection range of 12M and 15M cameras will reach 400m and 500m, separately. The application of high-pixel automotive cameras will become a megatrend in the future.
In current stage 12M cameras are generally used to support driving recorder applications. Yet some companies are already deploying 12M cameras (Voyager Technology is expected to introduce a 12M camera in 2024, which uses OmniVision's CIS). As for 15M cameras, there is only a product released by Baidu Apollo together with Sony Semiconductor, Lianchuang Electronic, and Black Sesame technologies in May 2022 (presumably developed on the basis of Sony's non-vehicle-specific CIS), having yet to be implemented.
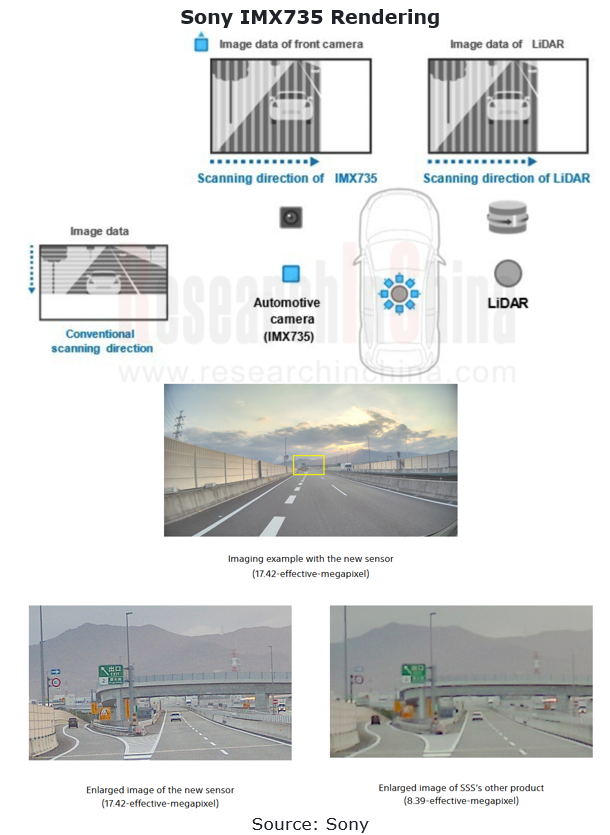
In September 2023, Sony announced IMX735, a new CMOS image sensor for intelligent driving, with 17.4M resolution (3017x5777). The improved saturation illumination of the new sensor at 17.42 effective megapixels (based on the image sensor effective pixel specification method), made possible by a proprietary pixel structure and unique exposure method, yields a wide dynamic range of 106 dB even when simultaneously employing high dynamic range (HDR) imaging and LED flicker mitigation. The dynamic range is even higher, at 130 dB, when using dynamic range priority mode.
Samples of this product are now available, with unit price of 30,000 yen. The production time is to be determined.
4. Automotive CIS HDR: from 140dB to 150dB.
HDR is one of the important technical parameters of CIS. The 140dB HDR front-view CISs in mass production include ON Semiconductor AR0820AT and OmniVision OX08B40. The 8M camera in NIO EC6, a model launched in September 2023, uses ON Semiconductor or OmniVision's CIS. The 8M products of the both offer 140dB HDR. With regard to Tier1s, FVC3, the third-generation front-view smart camera released by Freetech in August 2022, features 8M resolution, 140dB HDR, and frame rate of 30fps, and is expected to be mounted on Venucia models in 2023.
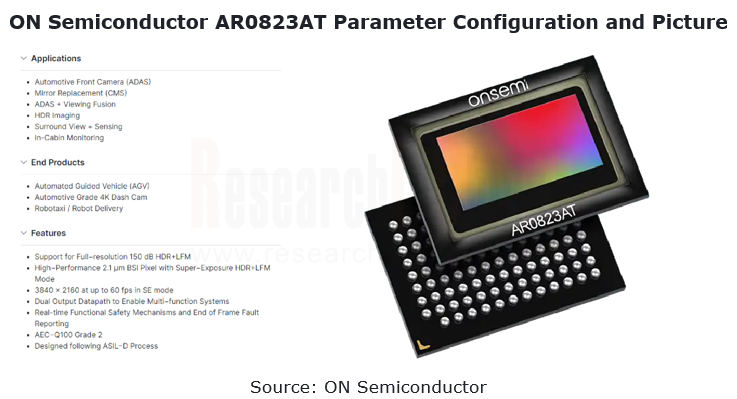
In October 2023, ON Semiconductor announced that the samples of AR0823AT, its 150dB HDR automotive CIS, has been available, and the mass production is scheduled to start in 2024. Parameter configuration is: 8.3MP (3840x2160), 150dB HDR, LFM, 1/1.8-inch, 2.1μm, 60fps, BSI, and Rolling Shutter.
5. TI and Maxim lead the serializer/deserializer (SerDes) market, and China’s local companies follow dual routes to pursue win-win results.
To meet the needs of ADAS and future high-level autonomous driving, data from vehicle cameras must be transmitted at high speed and without delay and loss. Automotive SerDes however has high requirements for electromagnetic environment, operating temperature environment, PPM, service life, safety, and reliability. And current SerDes solutions are essentially dedicated, which means the combined use of modules must use unified solutions of a chip vendor.
At present, players in the industry are led by: Texas Instruments (TI), Maxim Integrated, AI Micron, Inova Semiconductors and Rohm. Among them, TI and Maxim Integrated are monopolists in the global automotive display SerDes and automotive camera SerDes markets, so there is little room for local players in the Chinese market.
Key local SerDes companies in China are AI Micron and Norelsys, and some local Tier2s in the camera industry chain, such as Sunny Optical, have also stepped into the industry by cooperation and other ways.
AI Micron, established in 2017, has self-developed the first-generation products of AHDL (automotive high definition link) and real-time two-way communication protocols, which were mass-produced in 2020, and has shipped nearly one million units. The second-generation automotive SerDes was produced in quantities in March 2022, and marketing has started. With transmission rate up to 6Gbps, it is largely used in vehicles in 2023. At present, the main autonomous driving SerDes products are AIM 905X and AIM 905M, and the cockpit SerDes products include AIM 951 and AIM 955/957.
Norelsys was established in 2009, and its SerDes series products support the HSMT protocol (drafted by a total of 24 companies including chip vendors like Norelsys, China Academy of Information and Communications Technology, OEMs like FAW Group, and other suppliers in 2020). In April 2023, Norelsys released a new generation of automotive SerDes products, which deliver single-channel forward transmission rates ranging from 2Gbps to 12.8Gbps, and can support up to 15MP cameras and 4K@60Hz displays. Norelsys’ new-generation automotive SerDes series products are planned to be mass-produced for multiple mainstream models of several leading OEMs in China in the second half of 2023.
In 2021, Sunny Optical cooperated with Japan's Sony Semiconductor and Israeli chip company Valens Semiconductor to jointly launch next-generation MIPI A-PHY-compliant image sensor products and camera modules. According to their plan, the first vehicles using MIPI A-PHY components are expected to come into production in 2024.
Robot Manufacturers’ Device-Cloud Collaborative Hybrid Computing Deployment Solution Research Report, 2026
EAI Device-Edge-Cloud Collaboration Research: How to Deliver After Layering, Summary of the Ranking for 12 Robot Manufacturers
China’s shipments of humanoid robots are projected to reach 50,000 unit...
China Passenger Car HUD Industry Report, 2026
HUD Research: Installation Rate Exceeds 25% as Entry Price of P-HUD-Equipped Models Falls to RMB130,000
The China Passenger Car HUD Industry Report, 2026 released by ResearchInChina combs through HUD...
Passenger Car Electronic and Electrical Architecture (EEA) and Technology Supply Chain Construction Strategy Research Report, 2026-2027
Passenger Car EEA: The Next-Generation AI EEA Is Gaining Momentum, Enabling Vehicles to Achieve "Autonomous Perception - Autonomous Decision-Making - Autonomous Evolution"
Vehicle Architecture Is Ev...
Next-generation Central and Zonal Communication Network Topology and Chip Industry Research Report, 2026-2027
Research on Zonal Communication Topology: New Architectures Including 10 BASE-T1S+RCP, AVB/TSN Ethernet Are Under Rapid Development
Vehicle communication networks are mainly divided into in-vehicle n...
Software-Defined Vehicles in 2026: Software Supply Chain Panorama and Business Models Research
Research on Automotive Software Business Models: Exploration of Token Economy, AI Service Revenue Sharing and Other Businesses
Under the Trend of AI Agents: Exploration of Business Models Based on T...
New Energy Commercial Vehicle 800-1000V High-Voltage Platform & Supply Chain Panorama Research Report, 2026
Research on 800V Architecture of Commercial Vehicles: New Energy Penetration Rate Exceeds 35%, and 800V Full-Domain High-Voltage Architecture Rapidly Penetrates Heavy-Duty Trucks
Explosive Growth in ...
ADAS and Autonomous Driving Tier 1 Suppliers Research Report, 2026 – Chinese Companies
Intelligent Driving Industry Leap: From Widespread L2.9 Adoption toward Physical AI and New Full?Domain Mobility Ecosystem
As vehicle intelligence advances, the installations and penetration rate of...
Vehicle-Road-Cloud Integration and C-V2X Industry Report, 2026
Vehicle-Road-Cloud and C-V2X Research: with the three-tier promotion system of "top-level planning + mandatory pilot + evaluation binding", the industry turning point is approachingThis report focuses...
China OEM Data Capability Analysis Report, 2026
OEM Data Capability Research: 24 OEMs × 9 Capability Domains, Who Takes the Lead?
An L4 autonomous driving R&D and test vehicle can generate approximately 10TB of raw data per single day — data v...
Autonomous Driving Domain Controller and Central Computing Unit (CCU) Industry Report, 2026
Autonomous Driving Domain Controller (ADCU) Research: One-Chip CCU solutions are quickly available in vehicles
In China's passenger car market, autonomous driving systems involved in mass production ...
Automotive EMS and ECU Industry Research Report, 2026
Automotive EMS Research: The boundaries between EMS providers and Tier1 suppliers are becoming blurred, and the supply chain model is evolving from a linear chain to a networked structure
Mainstream ...
Automotive Microcontroller Unit (MCU) and Application Scenario Research Report, 2026
Automotive MCU Research: Increased demand for redundant security drives ASIL D-compliant MCU shipments to exceed 100 million units
In a vehicle EEA, MCUs are widely distributed in various functional ...
China Intelligent Cockpit Patent Analysis Report, 2026
Intelligent Cockpit Patent Research: Cockpit AI, In?vehicle Health, and Infotainment Are Upgrade to Scenario?based and Proactive Functions
From a patent perspective, this report explores the cutting?...
Research Report on Application of VLA Large Model in Automobiles and Robots, 2026
Research on Automotive and Robot VLA: Hybrid Architectures Become Mainstream, VLA Integrates with General World Models, and Reinforcement Learning Serves as Core Engine
Vision?Language?Action (VLA) m...
China Charging Infrastructure (Supercharging, Battery Swapping, V2G, etc.) and High-Performance Supercharging Battery Research Report, 2026
Charging and battery swapping research: as 5C+ supercharging vehicle models go into mass production, the pace of OEMs self-building supercharging networks quickens
800-1000V high-voltage platforms ar...
China Passenger Car Electronic Controlled Suspension Industry Report, 2026
Electronic Controlled Suspension Industry Research: As the First Year of Full Active Suspension Unfolds, Three Technical Routes Race Forward
1. Penetration Rate Surges Three Times, and Electronic Con...
Intelligent Driving SoC Research Report, 2026
Research on Intelligent Driving SoCs: Competition Focus Shifts to L3/L4 Embedded Hardware, and Computing Power of Flagship Vehicle Models Exceeds 1,000 TOPS
In terms of intelligent driving system in...
Automotive AI Large Model Technology Research Report, 2026
Automotive AI Large Model Research: Competition Shifts from "Who Has the Stronger Model" to "Who Boasts Higher Link Efficiency"
ResearchInChina released the Automotive AI Large Model Technology Resea...