Automotive Software Providers and Business Models Research Report, 2022
Research on software business models: four business forms and charging models of automotive software providers.
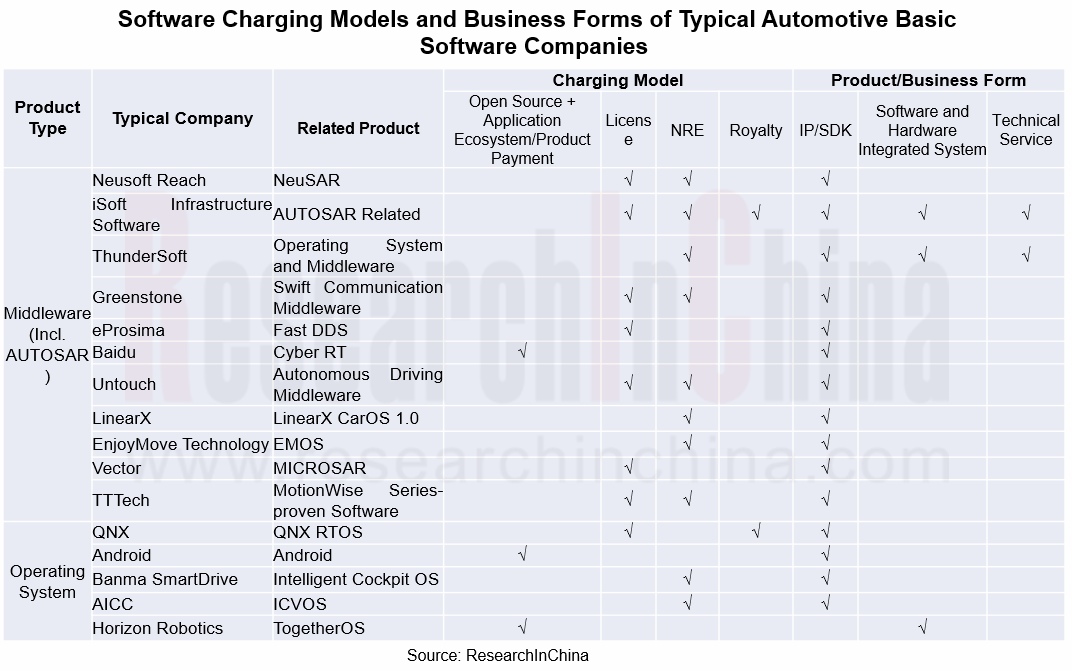
In an age of software-defined vehicles, automotive software booms, and providers step up their efforts to deploy various layers of software for a place in the software market. From the current layout of automotive software products and solutions, it can be seen that intelligent vehicle software business models include IP, solutions and technical services, and charging models are led by non-recurring engineering (NRE), software authorization/license, and royalty.
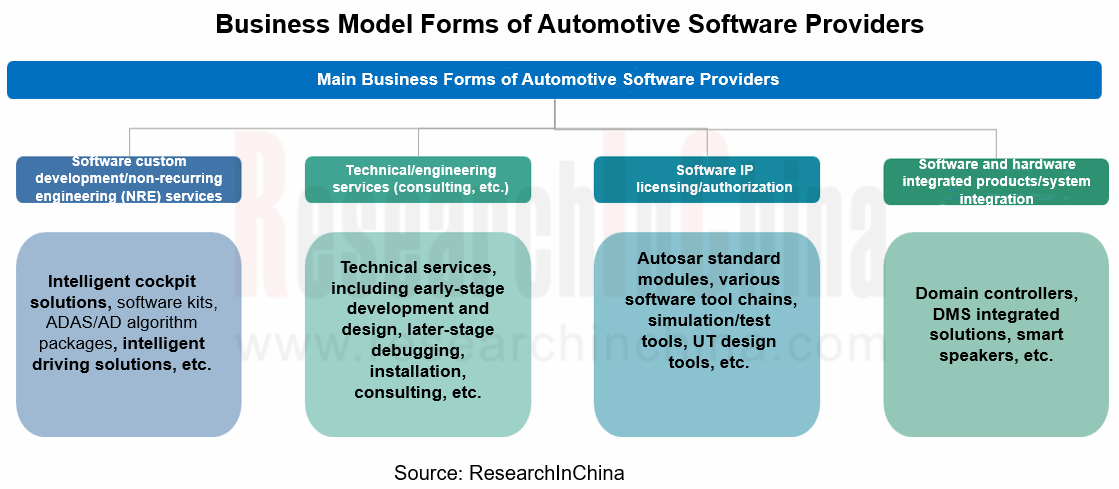
Through the lens of the product and solution layout of automotive software providers, currently their typical business forms are custom software development and design, technical services, software license/authorization, and system integration, varying slightly in charging models.
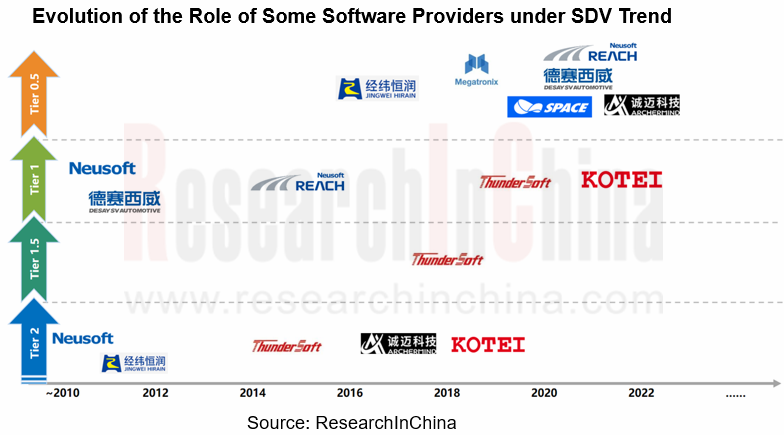
As software and hardware tend to be decoupled and layered, software becomes an independent core component product, and the automotive software industry chain is reshaped. The boundaries between Tier 1 and Tier 2 suppliers thus become ever more blurred, and even OEMs will develop their own hardware and software. Automotive software providers are transforming from Tier 2 into Tier 1 or even Tier 0.5 suppliers, with an increasingly high position in the industry chain.
The supply relationships between suppliers and automakers are changing as well. The conventional automotive supply chain has been broken, and the original chain-type "supply" model turns into a flat "cooperation" model. Players that have the ability to develop and integrate software and hardware are expected to become super suppliers, driving innovations and technology upgrades in the automotive industry.
Basic software layer: in the trend for modularization, standardization and platformization, suppliers and OEMs build closer relationships and more flexible cooperation models.
In service-oriented architecture (SOA), automotive basic software is an embedded software platform used to enable decoupling of software and hardware for automotive systems, and providing software and hardware support for automotive system services. It is the key to realization of vehicle intelligence.
In addition to chip and hardware, basic software is the most basic underlying capability in the entire industry chain. Major suppliers double down on development and innovation of automotive basic software products such as operating system and middleware. As well as large foreign providers such as Vector, ETAS and EB, quite a few local software providers in China like Neusoft Reach, ThunderSoft, Jingwei Hirain, and iSoft Infrastructure Software under China Electronics Technology Group Corporation are also working to deploy automotive basic software products, especially middleware products, most of which are AUTOSAR standard-compliant products, and hybrid platform software solutions based on CP and AP architectures.
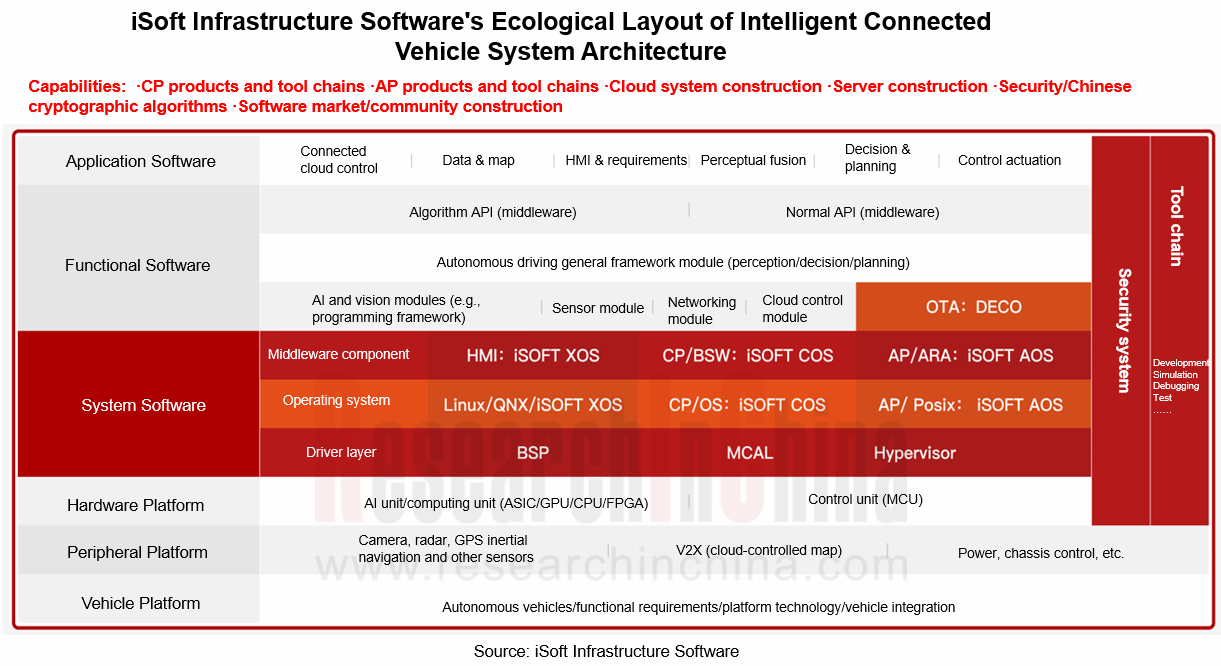
To meet the market demand in the trend for SDVs, iSoft Infrastructure Software provides AUTOSAR CP+AP integrated solution for the two scenarios, security domain and high-performance computing domain, and combines it with iSoft Cloud System to enable landing of intelligent connectivity. This solution is applicable to intelligent cockpit domain, vehicle control system domain and ADAS/AD domain. By standardizing the interfaces and architectures of different operating systems, underlying hardware, protocol software, etc., it enables service-oriented architecture. Meanwhile, for intelligent cockpit and ADAS/AD domains, iSoft Infrastructure Software is developing corresponding operating system kernels for a comprehensive layout of automotive basic software platform.
As concerns business model, iSoft Infrastructure Software positions itself as a Tier 2 supplier that adopts a model similar to VECTOR and concentrates on developing and applying basic software and tool chains. The "neutral" position allows the company to focus more on the R&D and application of vehicle basic software technology.
In 2018, Neusoft Reach introduced NeuSAR, China’s first self-developed automotive basic software platform product which complies with the latest AUTOSAR release. NeuSAR not only supports conventional ECU development but provides a wealth of basic software, middleware and development tools for software development based on domain control systems in new-generation E/E architectures. It is widely used in domain control systems such as autonomous driving, intelligent driving, chassis power, and body control in new-generation architectures, providing underlying software support for more personalized and intelligent application of the next-generation intelligent vehicles.
NeuSAR is composed of NeuSAR cCore, NeuSAR aCore, NeuSAR middleware, NeuSAR DS and NeuSAR tool chain. NeuSAR cCore subject to the latest AutoSAR Classic standard finds broad application in mass-produced ECUs of OEMs and many Tier 1 suppliers; NeuSAR aCore, the world's first commercialized AutoSAR Adaptive product, has been spawned and used in multiple autonomous driving domain controllers. The high compliance with the existing standards and the stability built through wide application make NeuSAR the preferred local AutoSAR product in the industry.
In 2020, under the guidance of Ministry of Industry and Information Technology, Neusoft Reach led the establishment of China Automotive Basic Software Ecosystem Committee (AUTOSEMO), aiming to help to create an independent controllable automotive basic software ecosystem.
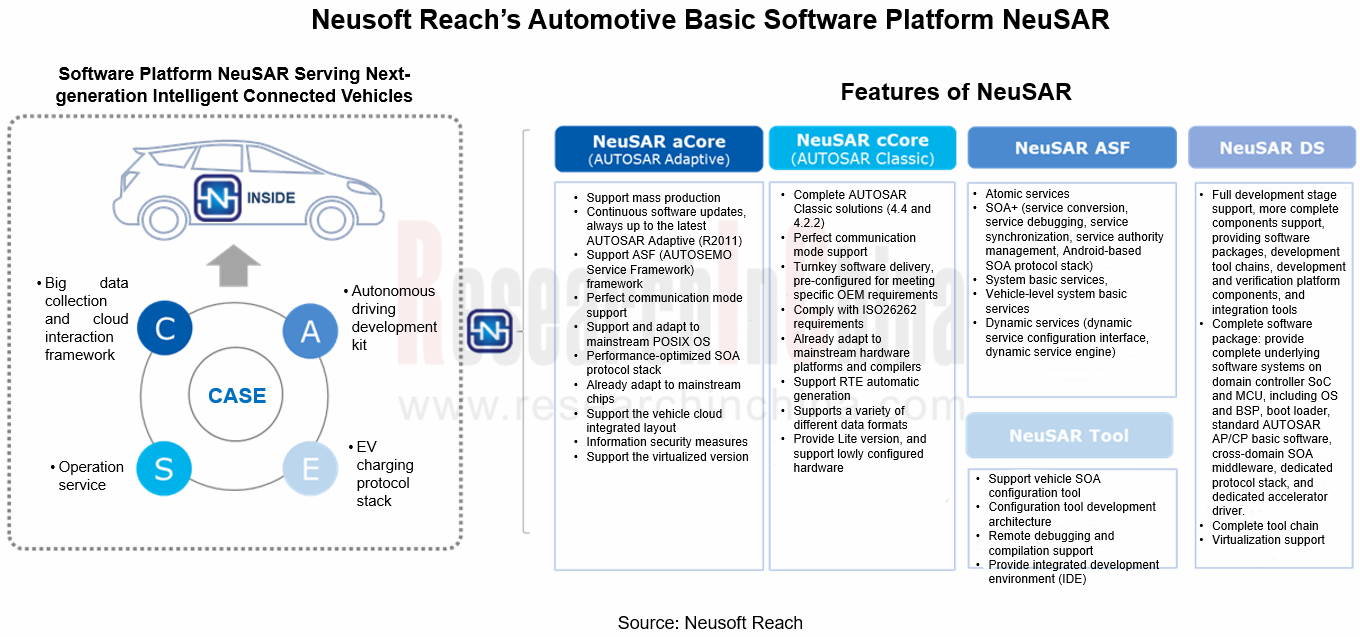
In the trend for "software-defined vehicles", automotive software industry will usher in layering and modularization, and a number of professional middleware module suppliers will be born. It is hard for automakers to complete R&D of full-chain software modules. OEMs will purchase software and hardware separately, and select hardware (chips) according to vehicle model position and price planning. They will also partner with basic software companies, mainly operating system and middleware providers, to build software architecture and adapt to chips.
Application software layer: to answer differentiated and individualized needs, conventional suppliers transform the development model from turnkey solution into bilateral in-depth cooperation.
Based on SOA (service-oriented architecture), the business model of SaaS (Software as a Service) is introduced. On the one hand, it provides users with an immersive entertainment space to meet their needs for emotional, personalized scenes and multimodal interaction. On the other hand, it offers self-development space to OEMs, creating infinite possibilities.
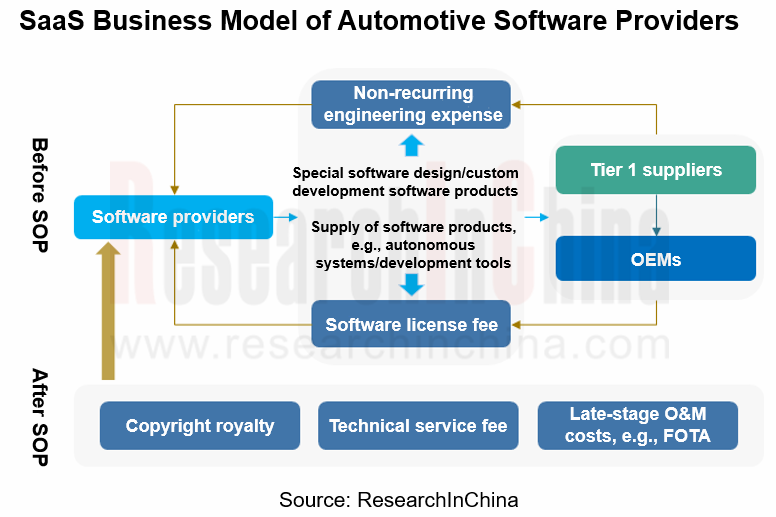
First of all, before mass production, automotive software revenue largely comes from non-recurring engineering project development fee and software license fee. Non-recurring engineering project development fee is that charged during development process from the special software design and custom development according to requirements of Tier 1 suppliers or OEMs to the final delivery of development results to customers. Software license fee is charged for the use of software products (systems or development tools) developed by software companies.
After mass production, the software charging model will turn into "royalty fees", "technical service fees" and FOTA-based software upgrade fees. Wherein, the royalty fees are the single vehicle copyright fees charged according to the number of functional module IPs used by customers, and the shipments.
For automotive software companies, they can also charge fees sustainably just like infrastructure services such as water and electricity. One example is the SaaS model.
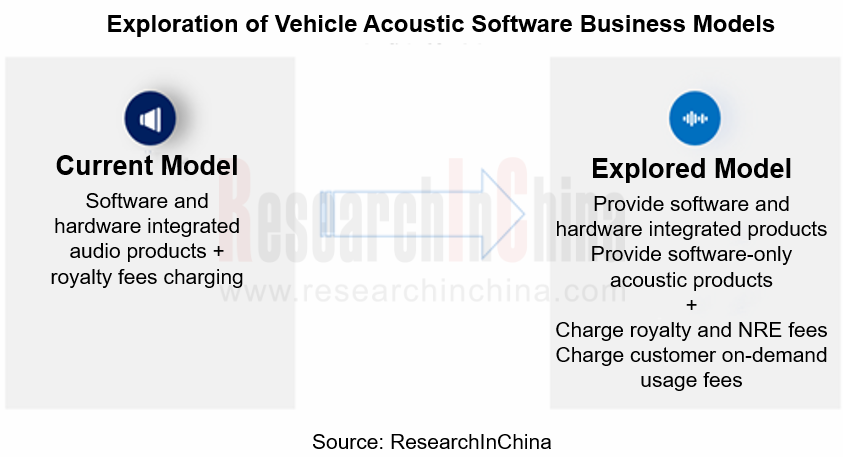
In the case of acoustic software OEM market, conventional automakers often choose products and toning services of acoustic components suppliers or electro-acoustic brands, while intelligent vehicle manufacturers tend to purchase products and services from acoustic components suppliers for the purpose of cost control, rapid iteration and standardized modular production, that is, a model that leaves automakers using their own or third-party toning modes for overall audio debugging
For example, in February 2022, Harman announced Software-Enabled Branded Audio, an on-demand software platform that offers consumers a user-friendly, affordable way to upgrade existing unbranded car audio experience with no additional hardware required.
Vehicle-cloud platform layer: under the new-generation infrastructures, enable the innovative model of vehicle-cloud co-construction and coordination.
As underlying infrastructures get improved, new-generation vehicle E/E architectures evolve, SOA-based design concept becomes widespread, cloud infrastructures are far more perfect, and cloud computing power becomes stronger, cloud computing has become a crucial productivity in the automotive industry. The vehicle-cloud integrated data drive will play a key role in the competition in the automotive industry.
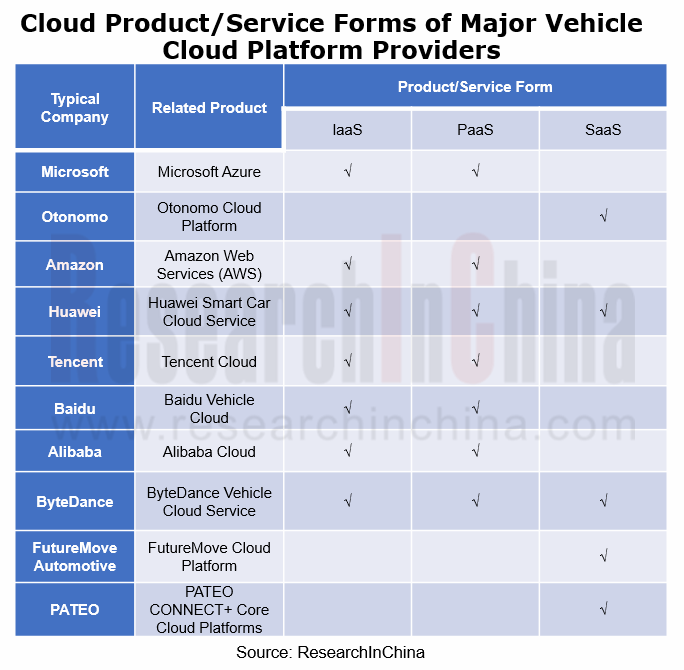
Vehicle cloud is a digital ecosystem platform for automakers to empower vehicle mobility and related intelligent services. Its service forms are divided into three types: IaaS, PaaS and SaaS. The IaaS layer is responsible for providing infrastructures related to computing, storage, network, CDN, security, disaster recovery and so forth in design, production and supply chain links; vehicle cloud services in the PaaS layer cover cloud platform architecture needed by after-sale links (such as call center, OTA, autonomous driving and telematics) and production design links (including analog, simulation, etc.); the SaaS layer involves sales and consumption of various function applications paid according to service time or amount of infrastructure.
At present, vehicle cloud service providers mainly include: public cloud providers that offer IaaS and Paas layers, such as Baidu Cloud, Tencent Cloud and Alibaba Cloud; those that cooperates with cloud platform service providers and provides SaaS services, including telematics service providers like PATEO and FutureMove Automotive. The former ones charge according to goods and services provided; the latter charge for services.
Cloud will be an effective supplement to vehicle, so specialized cloud solutions and digital platform tools will be gradually introduced. The complete layout of vehicle and cloud products will empower "vehicle-cloud integration" in the automotive industry. Whether from cost reduction and efficiency improvement or safety and reliability, OEMs will fail to meet the needs just by independent construction. They will be bound to forge closer partnerships with cloud service providers to open up new scene maps together and thus realize co-construction and enabling, a two-way process in which OEMs and cloud service providers walk and grow in the same pace in achieving development goals.
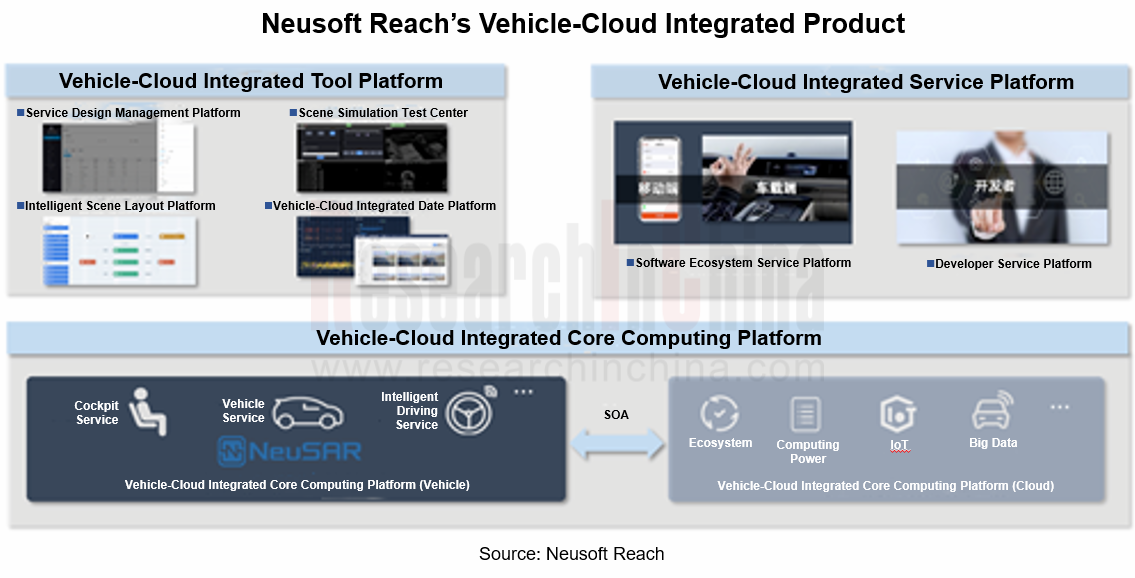
Neusoft Reach’s vehicle-cloud integrated platform is a self-developed intelligent software product for next-generation new E/E architectures. It is mainly composed of a vehicle-cloud integrated tool platform, a vehicle-cloud integrated core computing platform, and a vehicle-cloud integrated software ecosystem service platform, fully covering SOA-based design and development environment and runtime environment. The connection of in-vehicle capabilities and the reintegration of cloud big data and ecosystem service capabilities will quickly enable massive intelligent scene applications with a high degree of vehicle-cloud cooperation.
Neusoft Reach’s vehicle-cloud integrated product builds vehicle-cloud integrated intelligent vehicle digital bases based on the SOA design idea, and provides OEMs with full-stack SDV products and services, thereby improving brand value in the aspects of "uniqueness", "added value", and "evolvability".
Automotive Microcontroller Unit (MCU) and Application Scenario Research Report, 2026
Automotive MCU Research: Increased demand for redundant security drives ASIL D-compliant MCU shipments to exceed 100 million units
In a vehicle EEA, MCUs are widely distributed in various functional ...
China Intelligent Cockpit Patent Analysis Report, 2026
Intelligent Cockpit Patent Research: Cockpit AI, In?vehicle Health, and Infotainment Are Upgrade to Scenario?based and Proactive Functions
From a patent perspective, this report explores the cutting?...
Research Report on Application of VLA Large Model in Automobiles and Robots, 2026
Research on Automotive and Robot VLA: Hybrid Architectures Become Mainstream, VLA Integrates with General World Models, and Reinforcement Learning Serves as Core Engine
Vision?Language?Action (VLA) m...
China Charging Infrastructure (Supercharging, Battery Swapping, V2G, etc.) and High-Performance Supercharging Battery Research Report, 2026
Charging and battery swapping research: as 5C+ supercharging vehicle models go into mass production, the pace of OEMs self-building supercharging networks quickens
800-1000V high-voltage platforms ar...
China Passenger Car Electronic Controlled Suspension Industry Report, 2026
Electronic Controlled Suspension Industry Research: As the First Year of Full Active Suspension Unfolds, Three Technical Routes Race Forward
1. Penetration Rate Surges Three Times, and Electronic Con...
Intelligent Driving SoC Research Report, 2026
Research on Intelligent Driving SoCs: Competition Focus Shifts to L3/L4 Embedded Hardware, and Computing Power of Flagship Vehicle Models Exceeds 1,000 TOPS
In terms of intelligent driving system in...
Automotive AI Large Model Technology Research Report, 2026
Automotive AI Large Model Research: Competition Shifts from "Who Has the Stronger Model" to "Who Boasts Higher Link Efficiency"
ResearchInChina released the Automotive AI Large Model Technology Resea...
Intelligent Vehicle Cockpit Domain Controller Research Report, 2026
Cockpit domain controller research: L3 AIDV intelligent cockpit domain controllers are entering a boom period
Driven by multiple factors such as the continuous evolution of the automotive central int...
Automotive Acoustic System (Audio, Multi-Channel) Industry Report, 2026
Automotive Acoustics Research: Multiple Channels, AI Tuning, and Self-Developed Algorithms Drive the Transformation of High-End Cockpit Sound Fields
I. Automotive Audio Hardware Solutions with 6–9 S...
Autonomous Driving Sensor Chip Research Report, 2026
Research on Autonomous Driving Sensor Chips: Deeply Perceiving the Physical World, Sensor Chips Are Playing A “Leading Role” in Intelligence
In 2026, the autonomous driving sensor chip industr...
Passenger Car Corner Module and Wheel‑Side Control System Research Report, 2026
Wheel-side control research: the “last mile” chassis innovation
Wheel-side control dismantles the traditional drive, braking, steering, and suspension control of the chassis from a "centralized" styl...
Embodied Artificial Intelligence (& Humanoid Robot) MCU Research Report, 2026
Research on Humanoid Robot MCUs: Evolution from General-Purpose Control to High-Value Dedicated Chip Solutions Integrated with Edge AI Functions
MCU (Microcontroller Unit) refers to a compact integra...
Intelligent Vehicle Zone Control Unit (ZCU) Research Report, 2026
ZCU Research: Cross-domain integrated ZCUs are becoming the edge computing nodes of the next-generation zonal architecture
Currently, the mainstream zonal architecture is mainly the quasi-central + z...
Automotive Cybersecurity and Data Security Research Report, 2026
Cybersecurity & Data Security Research: Intelligent Connected Vehicles Enter the Era of “Systematic Offense-Defense and AI-Defined Security”.
Centering on the panorama of intelligent connect...
Report on Breakthrough Strategies of OEMs and ADAS Tier 1 Suppliers for Overseas Layout of Intelligent Driving, 2026
Regulatory Breakthrough, Local System Establishment, OEMs Competing for NOA Layout: Overall Trends of China’s Intelligent Driving Overseas Layout in 2026
Research on overseas intelligent driving layo...
OEMs and Tier1s’ Intelligent Cockpit Platform (Hardware and Software) Innovation Strategy Research Report, 2026
Intelligent Cockpit Platform Research: multi-dimensional cockpit system architecture reconstruction for multi-agent collaboration and proactive intelligent services
The intelligent cockpit software s...
Automotive AIOS Research Report, 2026
Automotive AIOS Research: Mass Production Solutions Are Implemented
Mass Production Solutions Are Implemented on A Small Scale.
In 2026, AIOS starts small-scale implementation, helping to improve v...
Automotive Telematics Service Provider (TSP) Research Report, 2026
TSP Research: Leading providers collectively turn to AI agents to provide all-scenario active services
Telematics Service Providers (TSPs) are the core hub of the telematics industry chain, connectin...